


Adobe is a subscription software leader serving creators, document users and enterprise marketing teams through Creative Cloud, Document Cloud and Experience Cloud. Creative products remain the largest revenue engine, while Acrobat, Firefly and enterprise workflows are becoming more important to user acquisition and long-term growth. That breadth gives Adobe several routes to monetize AI, though it also leaves the stock sensitive to new design platforms, slower ARR additions and leadership execution.
The latest quarter showed that demand remains durable even as the market questions the growth rate. Adobe Q3 FY2026 revenue reached $6.76 billion, up 13% year over year, and non-GAAP EPS rose 15% to $6.13. AI-first ARR grew more than 150%, though the $6.825 billion Q4 revenue-guidance midpoint sat just below the $6.84 billion consensus and kept the debate focused on conversion of free users into paid recurring revenue.
The ADBE stock forecast for 2026 now centers on two competing views:
- The AI monetization and recurring-growth case: Firefly, Acrobat AI Assistant and GenStudio could convert more than 1 billion monthly users into paid workflows, reaccelerating ARR and supporting a higher multiple.
- The competition and execution case: Free and lower-priced AI tools could slow paid additions, while executive turnover delays the strategy needed to restore investor confidence.
This guide breaks down the ADBE stock forecast, 2026 price scenarios, key risks and analyst outlooks, drawing on Adobe's September 10, 2026 Q3 FY2026 earnings release, quarterly filing and market data through September 11, plus how to trade ADBE stock futures on BingX TradFi with USDT collateral.
Top 5 Things for Adobe Investors to Know in September 2026
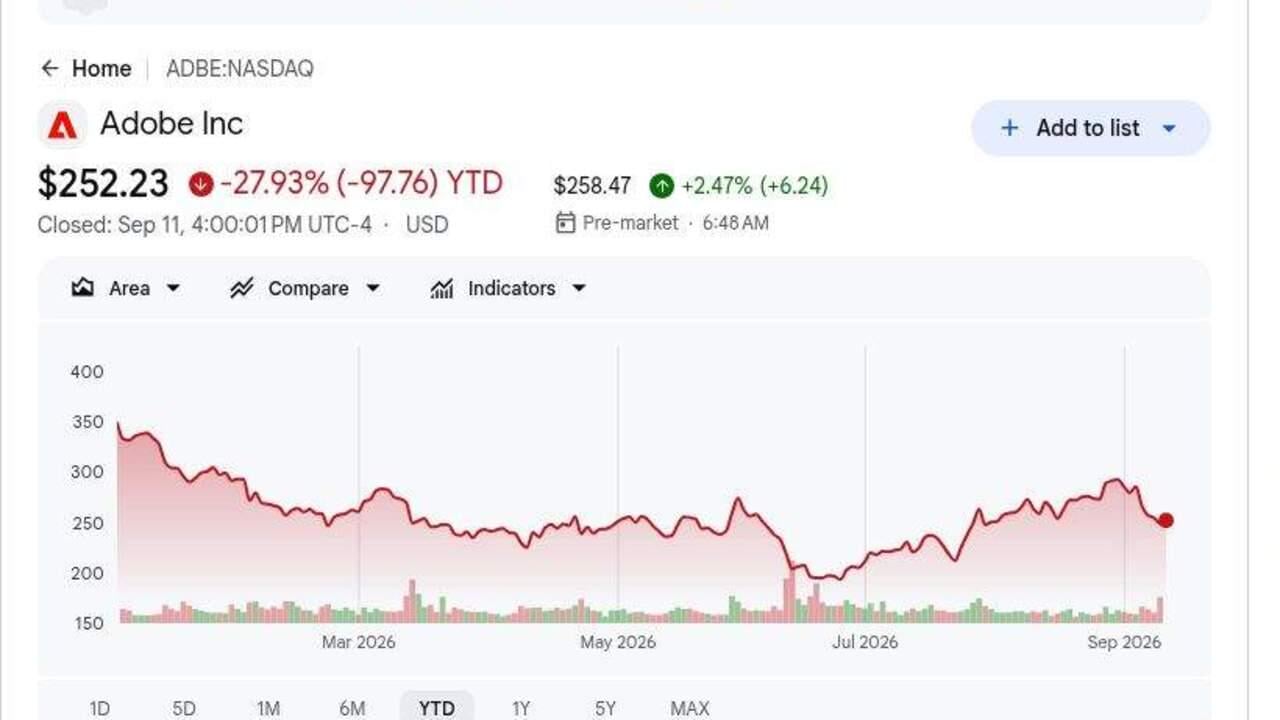
- ADBE closed at $252.23 on September 11 and was down 28% YTD: Shares remained far below prior-cycle highs despite a Q3 revenue beat. The gap shows that concerns around generative AI competition and recurring-revenue growth still weigh on valuation.
- Q3 revenue reached $6.76 billion, up 13%: Revenue beat the $6.69 billion FactSet consensus, while subscription revenue rose about 14% to $6.58 billion. Adobe's large recurring base remains an important defense against lower-cost creative competitors.
- AI-first ARR grew more than 150% as monthly users passed 1 billion: Adobe also reached more than 100 million freemium creative users, up over 70%. The key test is whether that reach converts into paid subscriptions without weakening net-new ARR.
- FY2026 revenue guidance rose to $26.576 billion to $26.626 billion: The new midpoint is about $153 million above the prior midpoint. Non-GAAP EPS guidance also increased to $24.45 to $24.50, showing continued cost leverage.
- Q4 revenue guidance of $6.80 billion to $6.85 billion was mixed: The $6.825 billion midpoint was slightly below the $6.84 billion consensus, while the $6.325 EPS midpoint exceeded the $6.31 estimate. Faster revenue growth remains the more important signal than another margin-driven EPS beat.
What Is Adobe (ADBE)?
Adobe is a global software company built around subscription products for creating, editing, managing and measuring digital content. Creative Cloud includes Photoshop, Illustrator, Premiere Pro and Firefly, Document Cloud centers on Acrobat and PDF workflows, and Experience Cloud helps enterprises manage marketing, analytics and customer journeys. Subscription revenue supplied $6.58 billion of Q3's $6.76 billion total, making renewal, pricing and product engagement the central economic engines. The model produces high gross margins and recurring cash flow, though generative AI has lowered barriers for rival creative tools.
Adobe's long-term direction combines generative and agentic AI with a wider freemium acquisition funnel. Firefly is embedded across Creative Cloud and Adobe Express, Acrobat AI Assistant extends paid document workflows, and GenStudio connects content production with enterprise marketing. The company passed 1 billion monthly active users in Q3, including more than 100 million freemium creative users, and AI-first ARR grew more than 150% year over year. Anil Chakravarthy is scheduled to become chief executive on December 1, making conversion of that reach into durable paid ARR the central strategic test.
Adobe (ADBE) Q3 FY2026 Earnings Overview: Revenue, EPS and Growth Drivers
Adobe delivered record Q3 revenue of $6.76 billion versus $6.69 billion expected, non-GAAP EPS of $6.13 versus $6.08 expected, total ARR of $27.50 billion and record operating cash flow of $2.52 billion. AI-first ARR grew more than 150%, and management raised FY2026 revenue to $26.576 billion–$26.626 billion, though the Q4 revenue midpoint remained slightly below consensus.
Read More: Adobe (ADBE) Q3 FY2026 Earnings Overview: $6.76B Revenue Beat Drives a 1.37% Price Rally
|
Financial Metric |
Guidance / Consensus |
Reported / Actual |
Surprise |
|
Q3 FY2026 revenue |
$6.69B FactSet consensus |
$6.76B |
Beat. $70M above consensus and up 13% YoY. |
|
Q3 non-GAAP diluted EPS |
$6.08 FactSet consensus |
$6.13 |
Beat. $0.05 above consensus and up 15% YoY. |
|
Q3 GAAP diluted EPS |
$4.18 one year earlier |
$4.62 |
Improved. Increased 11% YoY. |
|
Total ending ARR |
— |
$27.50B |
Expanded. AI-first ARR grew more than 150% YoY. |
|
Q3 operating cash flow |
$2.20B one year earlier |
$2.52B |
Record. Increased about 15% YoY. |
|
Q3 subscription revenue |
$5.79B one year earlier |
$6.58B |
Grew. Increased about 14% YoY. |
|
Q4 FY2026 revenue outlook |
$6.84B consensus |
$6.80B–$6.85B |
Mixed. $6.825B midpoint sat slightly below consensus. |
|
FY2026 revenue outlook |
Prior $26.40B–$26.50B |
$26.576B–$26.626B |
Raised. Midpoint increased by about $153M. |
|
FY2026 non-GAAP EPS outlook |
Prior $24.20–$24.30 |
$24.45–$24.50 |
Raised. Midpoint increased by $0.225. |
- Revenue of USD 6.76 billion beat consensus by USD 70 million: Sales rose 13% from USD 5.99 billion a year earlier, showing that core subscriptions continue to grow despite AI disruption concerns. The result supports a stronger revenue and earnings base.
- Non-GAAP EPS of USD 6.13 beat by USD 0.05 and rose 15%: Operating income reached USD 2.97 billion, allowing profit to grow faster than revenue. That shows Adobe is still generating operating leverage.
- Subscription revenue of USD 6.58 billion grew about 14%: Subscriptions supplied more than 97% of total revenue. Renewals and paid-user conversion therefore remain more important than product sales.
- Operating cash flow reached a record USD 2.52 billion: Adobe used USD 2.23 billion to repurchase 9.5 million shares. Strong cash generation supports buybacks and improves per-share earnings leverage.
- FY2026 targets moved higher despite mixed Q4 revenue guidance: Revenue now targets USD 26.576 billion to USD 26.626 billion and non-GAAP EPS targets USD 24.45 to USD 24.50. Q4's USD 6.825 billion revenue midpoint remained slightly below consensus.
Adobe (ADBE) 2026 Investment Outlook: $350 Bull Case vs. $190 Bear Case
The 2026 outlook depends on whether operating evidence can justify the valuation implied by the current share price. The following ranges are BingX Academy editorial scenarios rather than Wall Street forecasts.
The Bull Case: Strong AI Adoption Pushes ADBE Toward USD 350
The Bull Case assumes Firefly, Express and Acrobat AI features convert more of Adobe's 1 billion monthly users into paid plans. AI-first ARR growth stays above 150%, subscription revenue remains in double-digit growth and the incoming CEO provides a clear plan for stronger net-new ARR.
A move toward USD 350 would require Q4 revenue near the upper end of USD 6.80 billion to USD 6.85 billion, faster paid conversion and operating margin near 44%. Higher ARR estimates would strengthen the case.
The Base Case: Steady Subscription Growth Keeps ADBE Between USD 260 and USD 310
The Base Case assumes Creative Cloud, Acrobat and Experience Cloud retain their installed bases, while freemium AI expands reach faster than paid ARR. Revenue continues growing at a low-double-digit rate, while buybacks support EPS.
Under this scenario, ADBE could trade mainly between USD 260 and USD 310. FY2026 revenue within guidance, AI-first ARR growth above 100% and stable cash flow would support the range. A Q4 revenue miss or weaker paid conversion would cap the upper end.
The Bear Case: Slower Growth Pulls ADBE Toward USD 190
The Bear Case assumes AI competitors capture more creative workflows while Adobe spends more to defend its user base. Freemium users convert more slowly, pricing power weakens and leadership changes delay product or sales decisions.
A move toward USD 190 would become more likely if revenue growth falls below 10%, AI-first ARR slows sharply or FY2027 guidance disappoints. Lower earnings estimates and a weaker valuation multiple would add further pressure.
ADBE Stock Price Forecasts for 2026 By Wall Street Analysts
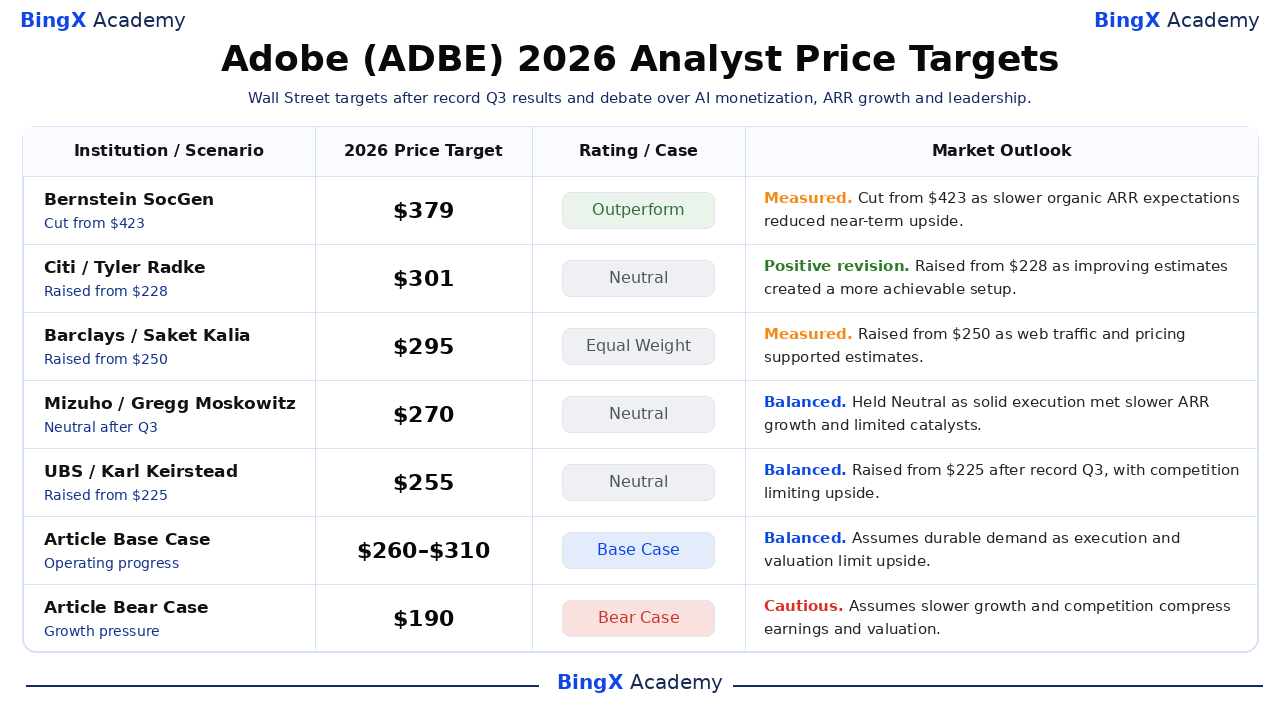
These five dated actions are sorted from highest to lowest and show how analysts weigh growth, competition, margin and valuation. They are third-party reference points rather than price promises. The final Base and Bear rows are BingX Academy editorial scenarios.
|
Institution / Scenario |
2026 Price Target |
Rating / Case |
Market Outlook |
|
Bernstein SocGen / Mark Moerdler |
$379 |
Outperform |
Measured. June 12: cut from $423 as the firm retained a positive long-term view after Q2, though slower organic ARR expectations reduced the valuation case. |
|
Citi / Tyler Radke |
$301 |
Neutral |
Positive revision. September 1: raised from $228 as the firm raised its target before Q3 as improving estimates created a more achievable setup, while retaining a neutral rating. |
|
Barclays / Saket Kalia |
$295 |
Equal Weight |
Measured. September 3: raised from $250 as strong web traffic and pricing supported estimates, though limited Q4 pricing benefit kept the rating balanced. |
|
Mizuho / Gregg Moskowitz |
$270 |
Neutral |
Balanced. September 11: maintained as q3 execution remained solid, while slower ARR growth and limited near-term catalysts constrained the re-rating case. |
|
UBS / Karl Keirstead |
$255 |
Neutral |
Balanced. September 11: raised from $225 as the target increased after record Q3 results, though competitive and pricing concerns kept the rating at Neutral. |
|
Article Base Case |
$260–$310 |
Base Case |
Balanced. Assumes durable demand as execution and valuation limit upside. |
|
Article Bear Case |
$190 |
Bear Case |
Cautious. Assumes slower growth and competition compress earnings and valuation. |
How to Trade Adobe (ADBE) Stock on BingX
Trade Adobe's AI-monetization, subscription-growth and leadership-transition outlook using BingX TradFi and BingX AI tools. Because ADBE can react sharply to earnings, guidance and product updates, traders should define both the catalyst and risk limits before entering a position.
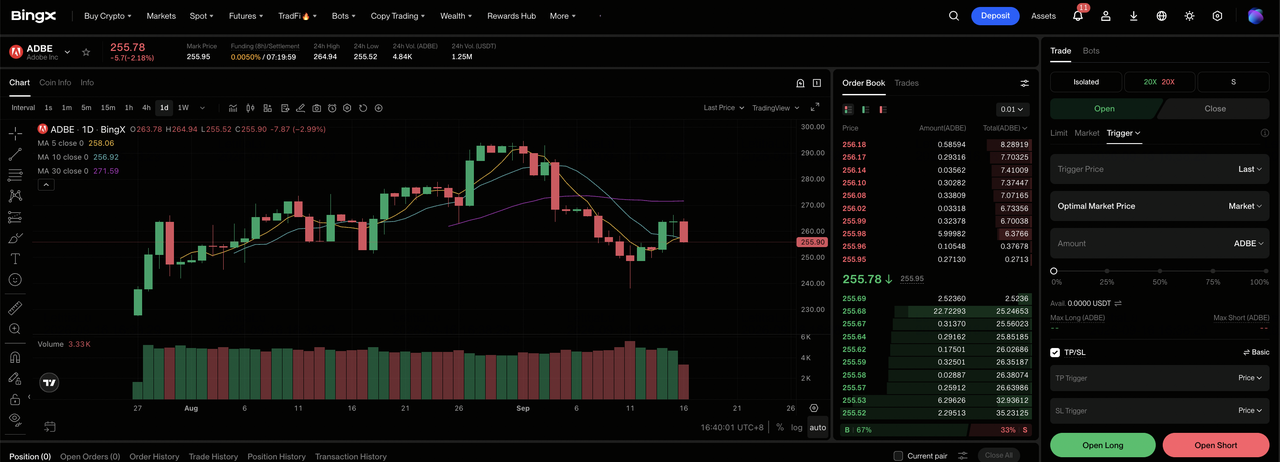
Step 1: Access BingX TradFi. Sign up and navigate to the specialized TradFi section on the BingX exchange dashboard.
Step 2: Select Adobe (ADBE). Search for and select the ADBE-USDT perpetual futures contract.
Step 3: Choose your direction. Select Open Long if growth and margins support the Bull Case. Select Open Short if competition or execution weakens expected per-share economics.
Step 4: Select leverage and margin mode. Choose Isolated or Cross-Margin based on your risk tolerance. The stock's 2026 volatility shows why conservative leverage and clear position sizing are important.
Step 5: Execute strict risk protocols. Set Take-Profit and Stop-Loss (TP/SL) levels before or immediately after entering the trade. ADBE can react quickly to results, guidance, analyst revisions and industry news.
Top 5 Risks to Watch for Adobe Investors in 2026
Adobe's outlook depends on demand, AI monetization, execution and valuation. These risks can affect earnings, cash flow and the multiple assigned to the stock.
- AI competition could slow paid growth: Adobe has more than 1 billion monthly users, but lower-cost tools could weaken conversion and slow growth from the USD 27.50 billion ARR base. That would pressure revenue expectations and valuation.
- Freemium growth may outpace monetization: Adobe has more than 100 million freemium creative users. If infrastructure and support costs rise faster than paid conversion, margins and free cash flow could weaken.
- Leadership changes could slow execution: Anil Chakravarthy becomes CEO on December 1 after Shantanu Narayen's long tenure, while the CFO role has also changed. Strategic delays could reduce confidence in FY2027 growth targets.
- Slower ARR growth could compress valuation: Subscription revenue represents more than 97% of total sales. Even modest renewal or pricing pressure could weaken revenue visibility and the earnings multiple.
- Buybacks cannot fully offset slower growth: Adobe spent USD 2.23 billion repurchasing 9.5 million shares in Q3. If revenue slows, a lower share count may not be enough to offset multiple compression.
Final Thoughts: Should You Invest in Adobe in 2026?
Adobe remains a highly profitable subscription franchise with $27.50 billion of ARR, $2.52 billion of quarterly operating cash flow and more than 1 billion monthly users. Those figures provide a strong base, though the stock still needs evidence that AI reach can restore durable paid growth. Q4 revenue and paid conversion should show whether the freemium strategy is creating durable value.
The Bull Case supports $350 if growth translates into stronger per-share earnings. The Bear Case points to $190 if competition, margin or execution pressure weakens estimates. Conservative traders may wait for the next revenue, recurring-growth and margin updates before increasing exposure. That evidence offers a clearer basis for choosing between the two scenarios and controlling position size.
Risk Reminder: Trading and investing in equities like ADBE involves a high risk of capital loss. Earnings misses, guidance changes, competition, valuation shifts and leveraged trading can produce rapid losses. Conduct independent research before allocating capital.
Related Reading
- AppLovin (APP) Price Prediction 2026: Can AXON Growth Push APP Toward $600?
- Figma (FIG) Price Prediction 2026: $36.00 AI Launchpad or Overvalued Post-IPO Hangover Trap?
- CrowdStrike (CRWD) Price Prediction 2026: Can AI Security and Falcon Flex Push CRWD Toward $280?
- Microsoft (MSFT) Stock Outlook for 2026: Can Azure AI and Copilot Growth Drive MSFT Stock to $550+?
- Cisco (CSCO) Stock Price Outlook for 2026: Can AI Growth and Splunk Drive CSCO Back to $90?
