
RTX Corporation (RTX) supplies aircraft engines, aviation systems, missiles and air defenses to airlines, aircraft manufacturers and governments. Its installed aerospace equipment generates recurring maintenance demand, while Tomahawk and AMRAAM production agreements expand the defense opportunity. Supplier throughput, engine repair costs and working-capital recovery determine whether growing orders translate into sustainable earnings and cash returns.
The latest quarter showed broad sales growth while cash conversion weakened. RTX Corporation Q3 2026 revenue rose 11% to $24.965 billion, with Raytheon sales increasing 14%. Adjusted EPS reached $2.26, including $0.25 of tariff-cost recovery, while free cash flow fell 47%. The Q4 test is whether higher deliveries can sustain earnings without relying on recovery benefits.
The RTX stock forecast for 2026 now centers on two competing views:
- The recurring aftermarket growth case: Engine maintenance demand and higher missile output could strengthen recurring earnings if factories convert contracted orders into deliveries without disproportionate working-capital investment.
- The earnings-quality and cash pressure case: Tariff recoveries could overstate repeatable profit growth if engine compensation, supplier bottlenecks and slower customer payments absorb the cash generated by higher sales.
This guide breaks down the RTX stock forecast, 2026 price scenarios, key risks and analyst outlooks, drawing on RTX Corporation’s October 20 Q3 2026 earnings release, quarterly filing and October 26 market data, plus how to buy RTX Stocks on BingX TradFi with USDT or USDC.
Top 5 Things for RTX Corporation Investors to Know in October 2026
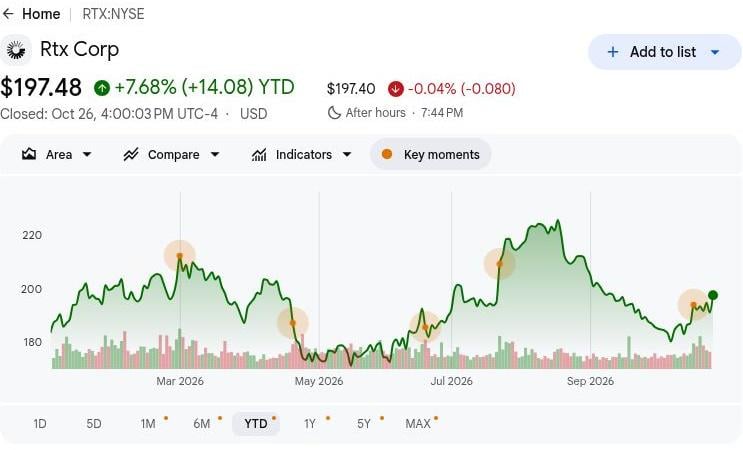
- RTX closed at $197.48 on October 26, up 7.68% YTD: Shares remain below their $226.88 annual high, making the $250 bull scenario dependent on sustained earnings growth. Further upside will require stronger aftermarket demand, missile deliveries, and cash generation beyond one-time tariff recovery benefits.
- Q3 revenue increased 11% to $24.965 billion. Sales rose from $22.478 billion a year earlier and $24.708 billion in Q2, while organic growth reached 12%. Strong commercial aerospace and defense demand supported expansion despite divestiture-related effects.
- Backlog reached $340 billion as commercial and defense demand strengthened: Quarterly awards exceeded $81 billion, providing substantial visibility into future revenue. Converting these orders into profitable deliveries will depend on manufacturing capacity, supplier performance, and contract execution.
- Tomahawk and AMRAAM contracts expand RTX's defense opportunities: Multi-year production awards totaling approximately $37 billion strengthen missile production visibility. Successful deliveries and favorable contract economics could support sustained defense revenue and earnings growth.
- Cash reserves of $9.173 billion support capacity expansion: RTX invested $1.964 billion in capital expenditures during the first nine months, supporting engine production, maintenance, and missile manufacturing. Strong liquidity provides investment flexibility, while improved cash conversion remains essential to long-term shareholder returns.
What Is RTX Corporation (RTX)?
RTX Corporation is an aerospace and defense company that develops equipment, propulsion and services for commercial aviation and military customers. Its three businesses combine Collins Aerospace aircraft systems, Pratt & Whitney engines, and Raytheon missiles, sensors and air defenses. Products including GTF engines, Patriot systems and Tomahawk missiles support airlines, aircraft manufacturers and government fleets. The company generates revenue through equipment deliveries, maintenance and long-duration contracts, with $176 billion of commercial backlog and $164 billion of defense backlog illustrating its customer mix.
RTX Corporation’s growth strategy focuses on expanding aftermarket services, increasing missile output, and improving manufacturing productivity. In 2026, Pratt & Whitney signed an agreement with Vietjet for engines powering 44 additional Airbus A320neo-family aircraft, alongside a 12-year EngineWise maintenance agreement. The company is also investing more than $100 million across three American repair sites to expand GTF maintenance capacity and improve turnaround times. With September 30 backlog reaching $340 billion, these initiatives aim to convert customer commitments into recurring service income and profitable deliveries, with returns depending on parts availability and factory throughput.
Read More: Top Defense Stocks to Buy in 2026: Primes, Missiles, Drones, Space, and AI-Enabled Warfare
RTX Corporation (RTX) Q3 2026 Earnings Overview: Aerospace Growth Lifts Earnings Despite Weaker Cash
RTX Corporation reported Q3 2026 revenue of $24.965 billion, up 11% year over year and 1% sequentially, supported by commercial aftermarket activity and higher defense deliveries across its three businesses. Adjusted EPS increased 33% to $2.26, including $0.25 of tariff-cost recovery, while free cash flow declined 47% to $2.119 billion. With backlog at $340 billion and full-year free-cash-flow guidance raised to $9.0 billion to $9.2 billion, future returns depend on repeatable margins, delivery execution and stronger cash conversion.
|
Financial Metric |
Guidance / Consensus |
Reported / Actual |
Surprise |
|
Net sales |
$22.478B Q3 2025 |
$24.965B |
Improved. Up 11% YoY. |
|
Adjusted EPS |
$1.70 Q3 2025 |
$2.26 |
Higher. Up 33% YoY. |
|
GAAP diluted EPS |
$1.41 Q3 2025 |
$1.89 |
Higher. Up 34% YoY. |
|
Operating cash flow |
$4.639B Q3 2025 |
$2.868B |
Lower. Down 38% YoY. |
|
Free cash flow |
$4.025B Q3 2025 |
$2.119B |
Lower. Down 47% YoY. |
|
Raytheon sales |
$7.045B Q3 2025 |
$8.031B |
Expanded. Up 14% YoY. |
|
Contract backlog |
$289B Q2 2026 |
$340B |
Expanded. Up $51B sequentially. |
|
FY2026 adjusted EPS |
7.10–7.25 prior |
7.65–7.75 |
Raised. Midpoint increased $0.525. |
- Q3 revenue increased 11% to $24.965 billion. Revenue increased 1% sequentially alongside annual growth, reflecting stronger customer demand across aerospace and defense. Sustained airline maintenance demand and missile deliveries will be important to maintaining earnings momentum.
- Pratt & Whitney revenue rose 10% to $9.231 billion. Commercial aftermarket sales increased 21%, driven primarily by higher GTF maintenance volume. Continued engine servicing and military demand could support earnings, although repair costs and original-equipment mix influence profitability.
- Adjusted EPS climbed 33% to $2.26 despite cash pressure. Tariff recovery added $0.25, while Pratt recorded a $363 million customer-bankruptcy charge. Higher sales supported profitability, but recurring margin improvement will be important as recovery benefits normalize.
- Maintenance investment expanded Pratt & Whitney’s repair capabilities. The company expanded GTF capacity through announced investments at three American maintenance sites. The investments support engine servicing, with returns depending on repair throughput and customer demand.
- Contract backlog reached $340 billion at September 30. The pipeline supports future deliveries, although revenue recognition depends on manufacturing schedules and available components. Increasing output, protecting contract margins, and collecting customer payments will be important to future earnings growth.
RTX Corporation (RTX) 2026 Investment Outlook: $250 Bull Case vs. $175 Bear Case
RTX Corporation’s 2026 outlook depends on whether higher aftermarket activity and missile production can deliver recurring earnings and cash. A $340 billion backlog supports demand visibility, while tariff recoveries and weaker quarterly cash conversion make underlying profitability central to valuation. The following editorial scenarios reflect how manufacturing throughput and engine costs could shape performance through December 2026.
The Bull Case: Aftermarket Growth and Cash Recovery Push RTX Toward $250
Faster engine servicing and missile deliveries would give RTX a direct route to stronger recurring earnings and cash generation. Pratt & Whitney’s Q3 aftermarket sales increased 21%, while Raytheon sales rose 14%, establishing two operating supports beyond tariff recovery. Converting those increases into repeatable margins would strengthen earnings while the installed aircraft fleet continues generating maintenance demand.
The $250 scenario would gain support if adjusted EPS reaches the $7.75 guidance ceiling and free cash flow approaches $9.2 billion. Recovering Pratt reported profitability without additional material inspection charges would help translate delivery growth into stronger shareholder returns.
The Base Case: Steady Aerospace Demand Keeps RTX Between $200 and $225
Continued aftermarket and defense growth could keep RTX’s earnings progressing even if quarterly cash conversion improves gradually. Q3 revenue increased 11%, helping offset a 47% decline in free cash flow against the prior-year comparison. The base case assumes demand persists, producing moderate operating growth while leaving engine costs and working-capital requirements unresolved.
A $200 to $225 range would fit adjusted EPS within $7.65 to $7.75 and delivery of the $9.0 billion cash-flow floor. Better collections would support the upper end, while higher repair costs could absorb enough progress to limit upside.
The Bear Case: Slower Servicing and Higher Costs Pull RTX Toward $175
Slower commercial servicing would expose RTX more fully to engine-related costs and the loss of tariff-recovery support. Pratt & Whitney supplied 21% aftermarket growth, while its reported operating profit fell 19% following a customer-bankruptcy charge. If customer demand weakens or inspection work increases, RTX could lose that earnings cushion before manufacturing investments deliver sufficient productivity gains.
The $175 scenario would become more likely if aftermarket growth slows alongside free cash flow missing the $9.0 billion guidance floor. Missile production would then need to contribute more simply to stabilize earnings, leaving less support for valuation expansion.
RTX Stock Price Forecasts for 2026 By Wall Street Analysts
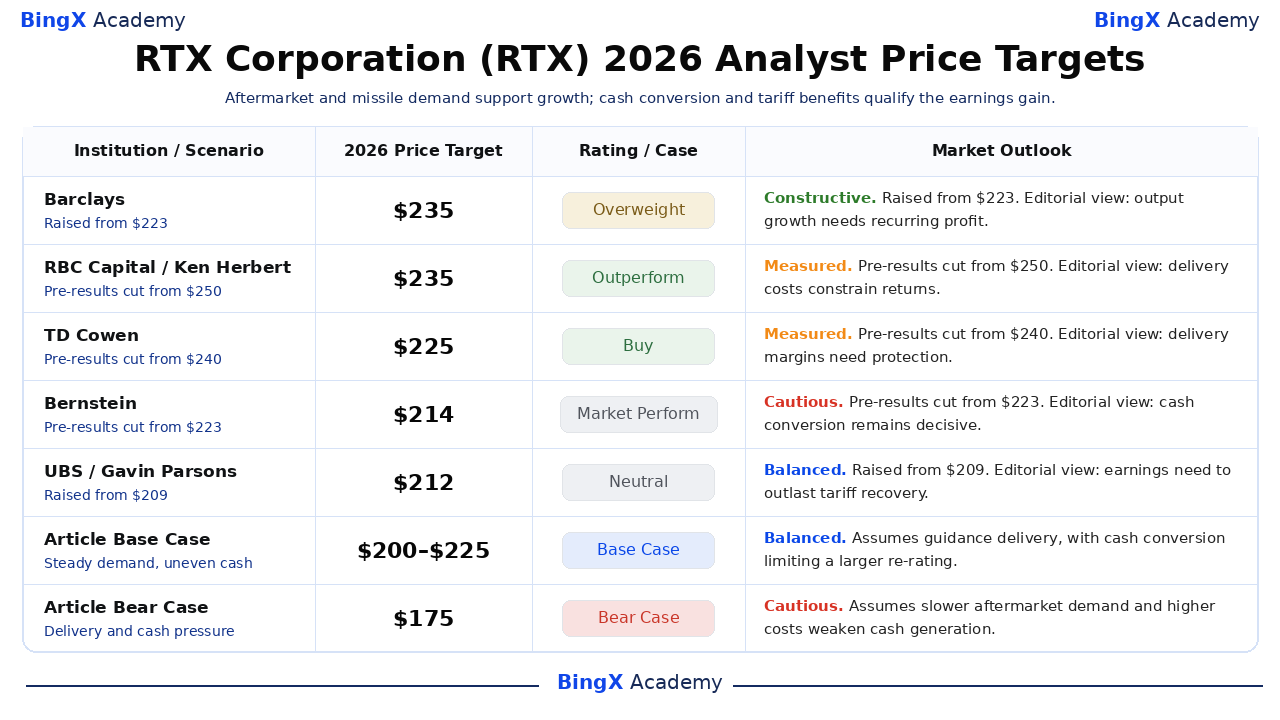
These named, dated targets refer to NYSE-listed RTX shares and generally cover roughly 12 months, extending beyond December 2026. The $212 to $235 range includes three explicitly labeled pre-results actions; business interpretations are editorial, not attributed analyst explanations. The final two rows are this article’s separate year-end scenarios.
|
Institution / Scenario |
2026 Price Target |
Rating / Case |
Market Outlook |
|
Barclays |
$235 |
Overweight |
Constructive. October 21, 2026: Raised from $223; maintained Overweight. Editorial view: higher output must produce recurring profit. |
|
RBC Capital |
$235 |
Outperform |
Measured. October 15, 2026: Pre-results cut from $250; maintained Outperform. Editorial view: demand remains exposed to delivery costs. |
|
TD Cowen |
$225 |
Buy |
Measured. October 9, 2026: Pre-results cut from $240; maintained Buy. Editorial view: engine and missile deliveries must protect margins. |
|
Bernstein |
$214 |
Market Perform |
Cautious. October 15, 2026: Pre-results cut from $223; maintained Market Perform. Editorial view: cash conversion matters beyond backlog. |
|
UBS |
$212 |
Neutral |
Balanced. October 21, 2026: Raised from $209; maintained Neutral. Editorial view: stronger earnings must outlast tariff recovery benefits. |
|
Article Base Case |
200–225 |
Base Case |
Balanced. Assumes steady aftermarket and defense demand, with repair costs limiting cash conversion through December 2026. |
|
Article Bear Case |
$175 |
Bear Case |
Cautious. Assumes slower servicing and higher engine costs weaken earnings and cash generation. |
How to Buy RTX Corporation (RTX) Stock on BingX
Buy and hold RTX Corporation shares through BingX Stocks Trading using USDT or USDC, subject to listing and account eligibility. RTX offers exposure to aircraft engines, aviation systems, missiles and air-defense technology. Eligible users can size holdings according to their investment goals without using leverage or paying perpetual funding fees.
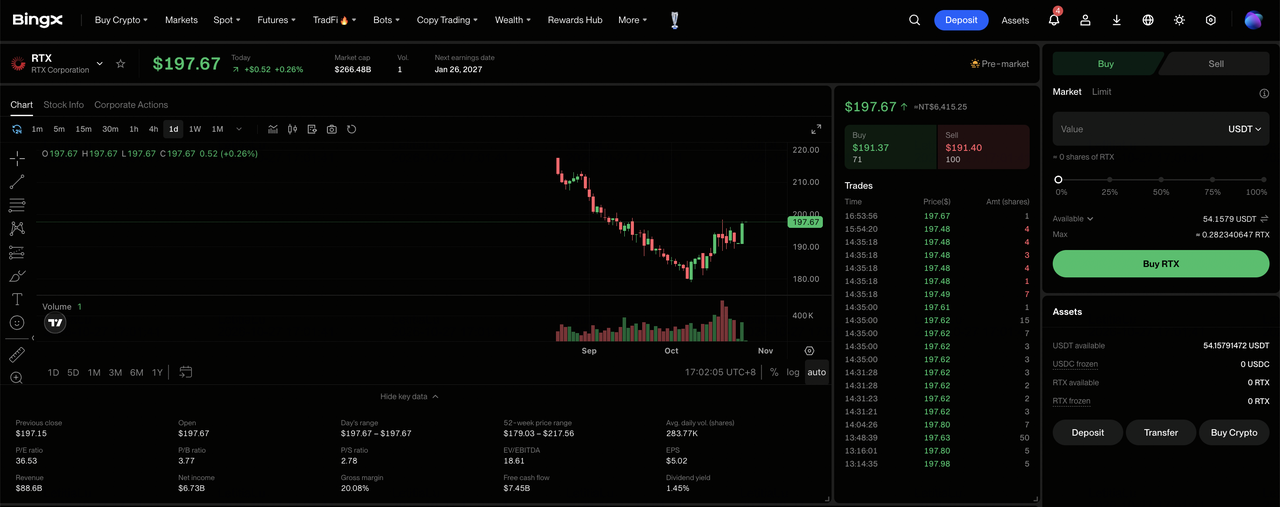
Step 1: Access BingX Stocks Trading. Sign up or log in to BingX, complete the required identity verification, and navigate to “TradFi > Stocks”. Accept the Stock Trading Risk Disclosure if accessing the product for the first time.
Step 2: Prepare USDT or USDC. Ensure your Spot Account has sufficient funds for the purchase. Transfer USDT or USDC from your Fund Account or Wealth Account if needed. Review the selected stock’s minimum order amount and fractional eligibility before choosing the investment size.
Step 3: Select RTX Corporation (RTX). Open the Stocks market, search for RTX Corporation (RTX), and confirm that the share is available to your account. Review the company identity, current share price, trading session and available order types.
Step 4: Buy RTX Corporation Shares. Select “Buy”, enter an allowed investment amount or share quantity, and choose a supported market or limit order. Market orders use available prices during supported sessions, while limit orders require the specified price or better and sufficient liquidity to execute.
Step 5: Review and Manage Your Holdings. Open “Stocks > Positions” to monitor your RTX shares and unrealized profit or loss. Use All Orders to review transactions or sell shares when needed. T+1 settlement generally affects when sale proceeds become withdrawable, rather than when purchased shares can be sold.
Top 5 Risks to Watch for RTX Corporation Investors in 2026
RTX Corporation’s installed engine base, expanding defense backlog, and recurring service relationships support its earnings outlook. However, weaker flight activity, engine costs, supplier delays, and investment demands could pressure profitability and shareholder returns.
- Weaker aftermarket demand could pressure revenue: Q3 Pratt aftermarket sales increased 21%, supported by GTF maintenance volume across its fleet. Lower shop visits or airline service spending could reduce earnings and operating margins.
- Higher engine costs could constrain margins: Q3 Pratt reported operating profit fell 19% to $608 million following a customer-bankruptcy charge. Higher inspection and repair costs could weaken profitability if servicing and equipment deliveries grow more slowly.
- Missile delivery delays could limit revenue growth: Q3 defense backlog reached $164 billion, but production requires available components and customer approvals. Delayed supplier shipments, factory output, or export approvals could reduce future revenue visibility.
- Maintenance investment could weaken shareholder returns: RTX announced over $100 million for American repair facilities, supporting GTF maintenance capacity. Slow repair throughput or additional parts shortages could limit cash generation and reduce investment returns.
- Weaker cash conversion could pressure valuation: RTX’s Q3 free cash flow reached $2.119 billion, down 47% despite revenue growth. Slower collections, weaker delivery margins, or rising engine costs could reduce returns and trigger share-price declines.
Final Thoughts: Should You Invest in RTX Corporation in 2026?
RTX Corporation’s $24.965 billion in quarterly revenue and $340 billion backlog demonstrate demand across commercial aviation and defense, although orders still require profitable delivery. Pratt aftermarket servicing and Raytheon missile programs provide earnings support, while maintenance investments create opportunities to improve throughput and recurring returns. Sustaining that growth will depend on repeatable margins beyond tariff recoveries and stronger cash conversion.
The $250 bull case assumes faster aftermarket growth, profitable missile deliveries, and upper-end cash generation. The $200 to $225 base case reflects steady demand, while the $175 bear case accounts for repair costs and weaker conversion. With RTX closing at $197.48 on October 26, investors should watch whether higher deliveries translate into sustainable cash returns.
Risk Reminder: RTX Corporation’s aerospace and defense backlog does not eliminate investment risk. Slower engine servicing, higher repair costs, or missile delivery delays could reduce earnings and cash generation. Investors should assess valuation, cash conversion, and their risk tolerance before buying RTX shares.
Related Reading
- Top Defense Stocks to Buy in 2026: Primes, Missiles, Drones, Space, and AI-Enabled Warfare
- Top Space Stocks to Buy Ahead of SpaceX IPO
- SpaceX (SPCX) Price Prediction 2026: Can AI Cloud Revenue Growth Push SPCX Toward $200?
- Firefly Aerospace (FLY) Price Prediction 2026: Can Launch and Defense Growth Push FLY Toward $55?
- Lockheed Martin (LMT) Price Prediction 2026: Can Record Backlog Push LMT Toward $700?
- Planet Labs (PL) Price Prediction 2026: Can Defense Demand Push PL Toward $35?
