MP Materials (MP) is building a U.S. rare-earth supply chain from mined ore to separated materials, metals and finished permanent magnets. Mountain Pass provides the upstream resource, while the Independence facility and planned 10X campus move the company into higher-value manufacturing. This vertical integration creates strategic exposure to transportation, robotics, defense and aerospace, though execution remains sensitive to rare-earth prices, policy support and magnet qualification.
MP Material Q2 2026 showed faster materials growth and improving earnings. Revenue reached $108.49 million, up 89% year over year and above the $96.89 million cited consensus, while adjusted EBITDA improved from a $12.535 million loss to positive $28.493 million. NdPr sales climbed 127% to 1,006 metric tons, though Magnetics revenue fell 17% during the production ramp.
The MP stock forecast for 2026 now centers on two competing views:
- The domestic magnet-scale case: higher NdPr output, price protection, General Motors qualification and the 10X expansion move MP toward a more valuable and defensible downstream earnings mix.
- The ramp and pricing case: magnet start-up costs, policy dependence and volatile rare-earth prices delay free-cash-flow conversion even as materials volumes improve.
This guide breaks down the MP stock forecast, 2026 price scenarios, key risks and analyst outlooks, drawing on MP Materials' August 6 Q2 2026 earnings release, quarterly filing and market data through September 15, plus how to trade MP stock futures on BingX TradFi with USDT collateral.
Top 5 Things for MP Materials Investors to Know in September 2026
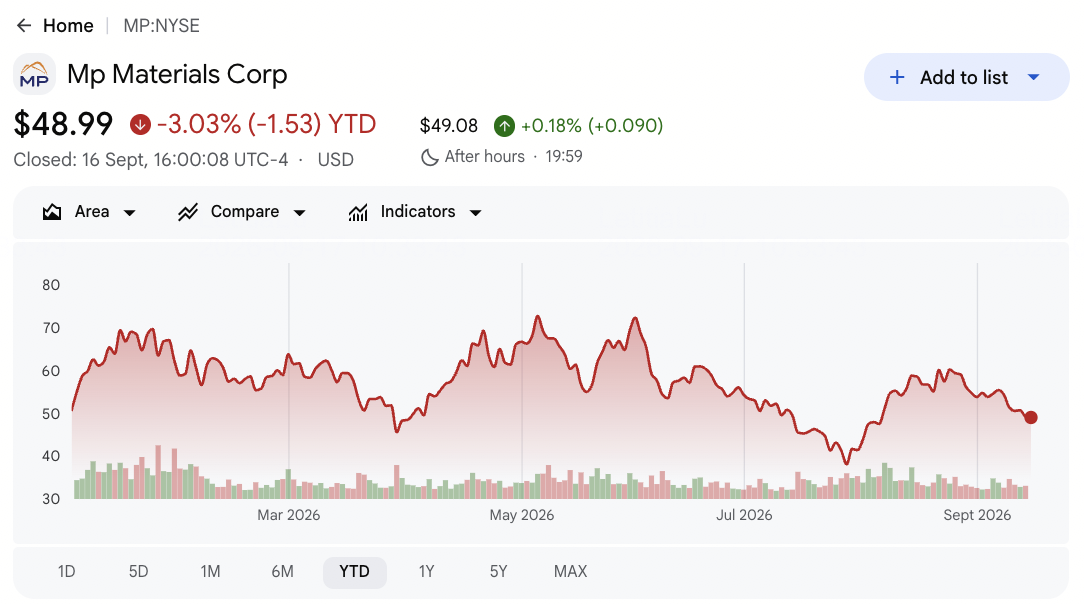
- MP closed at $49.17 after falling 2.67% YTD: Shares remained nearly 51% below the $100.25 52-week high. The pullback reflects a shift from policy-driven enthusiasm toward proof that magnet capacity can generate durable margins and cash flow.
- Q2 revenue reached $108.49 million, up 89%: Revenue beat the $96.89 million consensus by about $11.6 million. Separated NdPr sales and stronger pricing offset the end of concentrate shipments, giving investors a clearer view of domestic processing economics.
- NdPr sales rose 127% to 1,006 metric tons: Production increased 41% to 840 metric tons, showing that Stage II separation is scaling. Inventory movements also contributed, so sustainable output and conversion economics still matter.
- Price-protection income added $17.58 million: U.S. government support helped Materials adjusted EBITDA reach $32.505 million. Investors still need to separate policy-linked income from underlying market pricing when judging repeatable profitability.
- 10X, General Motors and Apple define the downstream growth test: Independence qualification and planned commercial shipments connect MP's resource base to finished magnets. The larger 10X campus and Apple program beginning in 2027 could broaden scale and customer exposure.
What Is MP Materials (MP)?
MP Materials owns and operates the Mountain Pass rare-earth mine and processing site in California. The company produces rare-earth concentrate, separated neodymium-praseodymium (NdPr) oxide and metal, then uses those materials to manufacture permanent magnets at Independence in Fort Worth, Texas. NdPr combines neodymium and praseodymium, two rare-earth elements used to make high-strength permanent magnets for electric motors. Its Materials segment monetizes mining, separation and metal production, while Magnetics covers precursor products and finished magnets. These components are essential to electric motors used across vehicles, industrial equipment, robotics, defense and aerospace.
The strategy is to reduce U.S. reliance on foreign rare-earth processing through domestic vertical integration. A U.S. Department of War partnership includes price protection, financing and support for additional separation and magnet capacity. General Motors is the anchor customer for Independence, Apple has committed to U.S.-made recycled magnets beginning in 2027, and 10X is planned as a larger Texas manufacturing campus. MP also announced a Saudi joint venture and a long-term gadolinium offtake agreement with an American aerospace and defense customer, expanding beyond NdPr.
Read More: Top Energy Stocks and ETFs to Buy in 2026: The AI Power Crunch Meets Geopolitical Volatility
MP Materials (MP) Q2 2026 Earnings Overview: NdPr Growth, Positive EBITDA and Magnet Ramp
MP Materials reported $108.49 million of revenue versus $96.89 million expected, with 89% growth supported by separated NdPr products. Adjusted diluted EPS was a $0.01 loss, in line with consensus and $0.12 better year over year, while adjusted EBITDA improved by $41.028 million to positive $28.493 million. Materials revenue rose 155% to $95.629 million, though Magnetics revenue fell 17% to $16.524 million as Independence moved through qualification and start-up.
Read More: MP Materials (MP) Q2 FY2026 Earnings Overview: $108.5M Revenue Growth Drives a 7.62% Price Rally
|
Financial Metric |
Guidance / Consensus |
Reported / Actual |
Surprise |
|
Q2 2026 revenue |
$96.89M consensus |
$108.49M; +89% YoY |
Beat. About $11.6M above consensus as NdPr pricing and volume improved. |
|
Q2 adjusted diluted EPS |
-$0.01 consensus |
-$0.01 |
In line. Improved by $0.12 YoY as adjusted EBITDA turned positive. |
|
Q2 GAAP diluted loss per share |
-$0.19 prior year |
-$0.11 |
Improved. The per-share loss narrowed by $0.08. |
|
Q2 net loss |
-$30.872M prior year |
-$20.296M |
Improved. Higher Materials profit offset magnet start-up costs. |
|
Q2 adjusted EBITDA |
-$12.535M prior year |
$28.493M |
Improved. The year-over-year swing reached $41.028M. |
|
Materials Segment revenue |
$37.532M prior year |
$95.629M; +155% |
Accelerated. Separated NdPr replaced concentrate sales. |
|
Magnetics Segment revenue |
$19.861M prior year |
$16.524M; -17% |
Declined. Mix shifted during the Independence ramp. |
|
NdPr production |
597 metric tons prior year |
840 metric tons |
Expanded. Production grew 41%. |
|
NdPr sales |
443 metric tons prior year |
1,006 metric tons |
Expanded. Sales volume increased 127%. |
|
Price protection income |
No prior-year income |
$17.580M |
Added. Policy support strengthened Materials profitability. |
- Revenue of $108.49 million beat consensus by about $11.6 million: Sales rose 89%, showing that separated products can replace concentrate revenue. Sustained growth now depends on production, pricing and downstream demand staying aligned.
- Adjusted EPS of negative $0.01 matched consensus: The loss improved by $0.12 year over year as stronger volume and price protection helped per-share results. Further improvement depends on a more consistent Magnetics contribution.
- Adjusted EBITDA improved by $41.028 million to $28.493 million: The swing showed clear operating leverage, though $17.58 million came from price-protection income. Investors still need to track policy-adjusted profitability and cash conversion.
- Materials revenue rose 155% to $95.629 million: NdPr oxide and metal revenue reached $94.434 million as sales volume more than doubled. The mix shift supports MP's strategy of capturing more value through domestic processing.
- NdPr sales rose 127% as Magnetics revenue fell 17%: Strong upstream execution contrasts with a downstream business still in qualification. Commercial shipments, regulatory testing and customer acceptance must improve before the full mine-to-magnet model contributes durable earnings.
MP Materials (MP) 2026 Investment Outlook: $95 Bull Case vs. $35 Bear Case
MP's 2026 outlook depends on whether strong rare-earth processing growth can translate into a profitable magnet business. Materials currently provides most of the earnings support, while Independence, 10X and customer qualification determine how much value the downstream strategy can add.
The Bull Case: Strong Magnet Growth Pushes MP Toward $95
The Bull Case assumes Independence enters commercial production on schedule, General Motors qualification converts into volume and the 10X campus advances without major cost overruns. NdPr production stays above 800 metric tons per quarter, price protection supports Materials economics and Apple adds another major demand channel.
A move toward $95 would require Magnetics revenue to reverse its 17% decline and adjusted EBITDA to remain positive beyond government income. On-time shipments, higher segment margins and clear 10X construction progress would strengthen the case.
The Base Case: Steady Materials Growth Keeps MP Between $60 and $75
The Base Case assumes separated NdPr volume keeps growing and policy support limits downside, while magnet start-up costs remain elevated during the commercial ramp. Materials provides most near-term earnings as Independence qualification progresses gradually and 10X remains a longer-term opportunity.
MP could trade mainly between $60 and $75. Positive adjusted EBITDA, stable NdPr pricing and customer qualification would support the range. Magnet delays or lower policy-linked income would limit the upper end.
The Bear Case: Magnet Delays Pull MP Toward $35
The Bear Case assumes rare-earth pricing weakens while Independence shipments slip and 10X requires more capital than planned. Materials margins decline, Magnetics remains below scale and customer concentration limits pricing power.
A move toward $35 would become more likely if adjusted EBITDA turns negative, NdPr output falls or commercial magnet volumes miss schedules. Lower earnings estimates and weaker free cash flow would add further pressure.
MP Stock Price Forecasts for 2026 By Wall Street Analysts
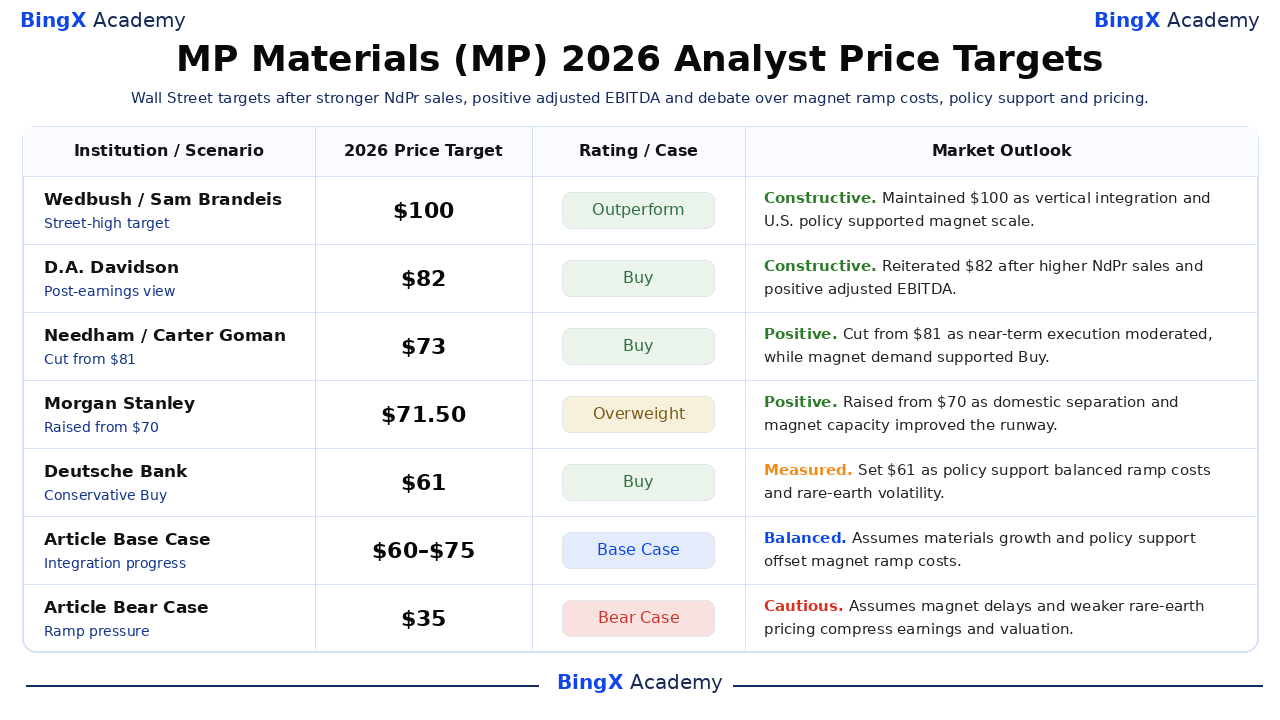
Selected analyst targets range from $60 to $100 and show wide disagreement over the value of policy support, downstream manufacturing and near-term ramp costs. Several firms reduced targets without abandoning positive ratings. The dated actions below separate the Street's twelve-month targets from the article's independent Base and Bear scenarios.
|
Institution / Scenario |
2026 Price Target |
Rating / Case |
Market Outlook |
|
Wedbush |
$100 |
Outperform |
Constructive. May 8: maintained a Street-high view as vertical integration and U.S. policy supported magnet capacity. |
|
D.A. Davidson |
$82 |
Buy |
Constructive. August 24: reiterated Buy after higher NdPr sales and positive adjusted EBITDA. |
|
Needham |
$73 |
Buy |
Positive. July 22: cut from $81 as near-term execution moderated, while magnet demand supported Buy. |
|
Morgan Stanley |
$71.50 |
Overweight |
Positive. July 8: raised from $70 as domestic separation and magnet capacity improved the runway. |
|
Deutsche Bank |
$61 |
Buy |
Measured. July 9: set a conservative target balancing policy support against ramp costs and pricing. |
|
JPMorgan |
$60 |
Overweight |
Measured. July 29: cut from $75 as near-term estimates reset while strategic value remained. |
|
Article Base Case |
$60-$75 |
Base Case |
Balanced. Assumes Materials growth and policy support offset magnet ramp costs. |
|
Article Bear Case |
$35 |
Bear Case |
Cautious. Assumes magnet delays and weaker pricing compress earnings and valuation. |
How to Trade MP Materials (MP) Stock on BingX
Trade MP Materials' NdPr, magnet-production and policy-support outlook using BingX TradFi and BingX AI tools. Because MP can react sharply to rare-earth prices and government announcements, define the catalyst and risk limits first.
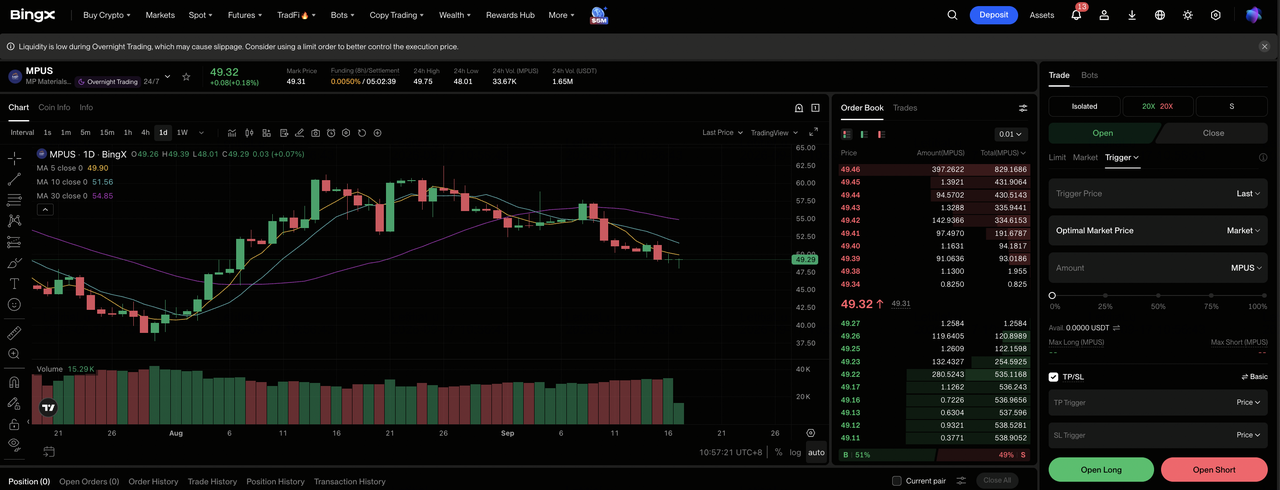
Step 1: Access BingX TradFi. Sign up and navigate to the specialized TradFi section on the BingX exchange dashboard.
Step 2: Select MP Materials (MP). Search for and select the MP-USDT perpetual futures contract.
Step 3: Choose your direction. Select Open Long if magnet qualification and Materials growth validate the Bull Case. Select Open Short if delays and pricing pressure validate the Bear Case.
Step 4: Select leverage and margin mode. Choose Isolated or Cross-Margin based on your risk tolerance. MP's $37.81-$100.25 52-week range supports conservative leverage.
Step 5: Execute strict risk protocols. Set Take-Profit and Stop-Loss (TP/SL) levels before or immediately after entering the trade.
Top 5 Risks to Watch for MP Investors in 2026
MP Materials faces commodity, execution, policy and financing risks as it expands from rare-earth materials into magnets. These factors can affect earnings, cash flow and the strategic premium assigned to the stock.
- Lower rare-earth prices could pressure margins: Stronger pricing supported Q2 revenue alongside higher sales volume. A reversal would reduce Materials earnings and leave less cash for Independence, 10X and additional processing capacity.
- Government support could change over time: Price protection contributed $17.58 million of Q2 income and improves near-term economics. Changes to funding, procurement or ownership priorities could reduce both direct support and MP's strategic premium.
- Magnet qualification could take longer than planned: Magnetics revenue fell 17% to $16.524 million during the production ramp. Delayed testing or customer acceptance would postpone operating leverage and keep start-up costs ahead of sales.
- Large customers increase execution risk: General Motors anchors Independence, while Apple demand begins later. Changes in schedules, specifications or volumes could affect utilization, revenue timing and returns on magnet capacity.
- 10X could require more capital than expected: The new campus brings construction, equipment and financing risk before revenue begins. Cost overruns could pressure free cash flow and reduce the value created by stronger Materials operations.
Final Thoughts: Should You Invest in MP in 2026?
MP Materials delivered a stronger Q2, with $108.49 million of revenue, 1,006 metric tons of NdPr sales and positive $28.493 million adjusted EBITDA. Those numbers show that domestic separation is scaling. Magnetics revenue of $16.524 million and ongoing qualification show that the downstream thesis is still developing.
The Bull Case requires Independence and 10X to translate strategic support into repeatable magnet margins, supporting $95. The Bear Case follows delayed qualification, weaker rare-earth prices and capital pressure toward $35. Conservative traders may wait for commercial magnet shipments, clearer customer utilization and positive adjusted EBITDA excluding unusual policy income before assigning the downstream platform a premium multiple.
Risk Reminder: Trading and investing in equities like MP involves a high risk of capital loss. Commodity prices, industrial policy, construction, customer qualification, valuation and leverage can produce rapid losses. Conduct independent research before allocating capital.
Related Reading
- Top Energy Stocks and ETFs to Buy in 2026: The AI Power Crunch Meets Geopolitical Volatility
- Top AI Energy Stocks to Buy in 2026: Nuclear, Gas, Fuel Cells, and the AI Power Buildout
- Top Defense Stocks to Buy in 2026: Primes, Missiles, Drones, Space, and AI-Enabled Warfare
- Occidental Petroleum (OXY) Price Prediction 2026: Can Oil and Deleveraging Push OXY Toward $85?
- ExxonMobil (XOM) Price Prediction 2026: Can Oil and Production Growth Push XOM Toward $205?
- Bloom Energy (BE) Price Prediction 2026: Can AI Data-Center Power Push BE Toward $350?
