


Aehr Test Systems (AEHR) makes test and burn-in equipment that screens chips before costly packaging or deployment. Its FOX wafer-level and Sonoma package-level platforms support power semiconductors, while AI processors and silicon photonics are expanding the opportunity. A small number of production ramps still drive a large share of prospective sales, so customer qualification, installation and acceptance determine when orders become earnings.
The latest quarter showed a rebound in deliveries and orders without full cash conversion. Aehr Test Systems fiscal Q4 2026 revenue rose 33.7% to $18.835 million, bookings reached $60.7 million and GAAP net income turned positive at $1.4 million. Yet full-year sales fell to $50.0 million and operating cash flow remained negative. Accepted shipments and collections must improve to support the much larger fiscal 2027 revenue guide.
The AEHR stock forecast for 2026 now centers on two competing views:
- The AI production-conversion case: FOX and Sonoma deliveries support the $130 million to $150 million fiscal 2027 guide and sustained profitability.
- The customer-timing and cash-conversion case: Concentrated ramps slip while operating cash use persists, leaving valuation ahead of results.
This guide breaks down the AEHR stock forecast, 2026 price scenarios, risks and analyst outlooks, drawing on Aehr's July 14 fiscal Q4 release and market data through October 19, plus how to trade AEHR stock futures on BingX TradFi with USDT collateral.
Top 5 Things for Aehr Test Systems Investors to Know in October 2026
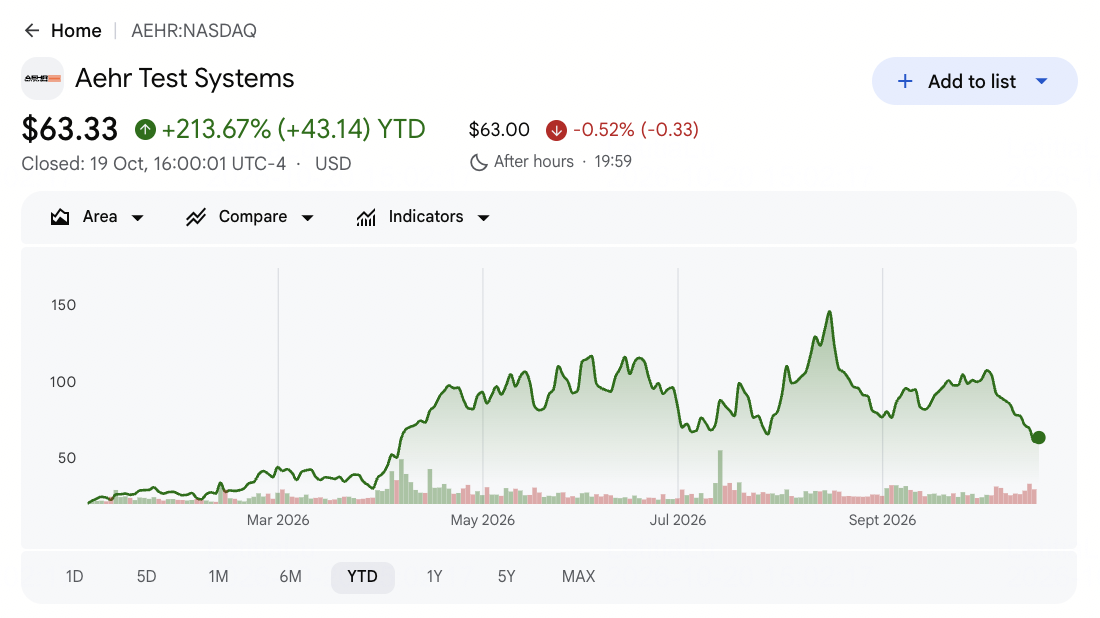
- AEHR closed at $63.33 after rising 213.67% year to date: The October 19 NASDAQ close is a reference price, not a live quote. Shares remained far below their $147.40 August 14 high, showing how quickly enthusiasm for AI test equipment can reverse when investors question the timing of revenue conversion.
- Fiscal Q4 revenue climbed 33.7% to $18.835 million: The result compared with $14.089 million a year earlier, while adjusted diluted EPS improved from a $0.01 loss to $0.11 profit. The quarterly rebound proves production activity can lift earnings, although the full fiscal year still contracted.
- Record $60.7 million bookings dwarf Q4 sales: Backlog stood at $80.6 million on May 29 and effective backlog reached $100.6 million including later bookings. The scale gives management visibility, but shipment, installation and customer acceptance must occur before those orders can become recognized sales and cash.
- The $130 million to $150 million FY2027 guide sets a steep hurdle: Against fiscal 2026 revenue of $50.0 million, the range implies roughly 160% to 200% growth. Management also targets non-GAAP net income equal to 18% to 22% of revenue, which requires volume to reach the income statement efficiently.
- Two AI follow-on orders sharpen the delivery test: An August 12 FOX-XP order totaled $22 million for a lead AI processor, while October 7 Sonoma follow-ons were about $6 million for a second processor program. Both announcements planned equipment deliveries over the next six months. The latter program expects production in calendar 2027, so its timing cannot be treated as immediate 2026 revenue.
What Is Aehr Test Systems (AEHR)?
Aehr sells semiconductor test and burn-in systems to manufacturers and test partners that find early failures before chips enter expensive packages or end systems. FOX-XP processes multiple wafers or die with WaferPak and DiePak contactors; FOX-CP serves single-wafer applications. Sonoma and Tahoe test packaged devices, including high-power processors. Systems, accessories and related services connect revenue to customer qualification, production capacity and screening needs across data centers, automobiles, industrial power and photonics.
Aehr is expanding its AI semiconductor testing business through major customer orders and new production programs. Its lead AI processor customer placed a $22 million FOX-XP follow-on order in August 2026, while a hyperscale AI customer ordered $41 million in Sonoma systems in April, followed by approximately $6 million in October for its next-generation processor. The company is also expanding into silicon photonics, with FOX-XP systems supporting optical interconnects for AI data centers. These orders strengthen Aehr's production pipeline, with future revenue growth depending on timely equipment deliveries, customer acceptance, and sustained demand.
Read More: Top AI Chip Manufacturing Stocks to Buy in 2026: TSMC, ASML, and Advanced Chipmaking
Aehr Test Systems (AEHR) Fiscal Q4 2026 Earnings Overview: Record Bookings Drive Strong FY2027 Growth Outlook
Aehr Test Systems reported Q4 FY2026 revenue of $18.835 million, up 33.7% year over year, while non-GAAP diluted EPS improved to $0.11 from a $0.01 loss. Record bookings of $60.7 million lifted quarter-end backlog to $80.6 million, reaching $100.6 million after subsequent orders. Management projected FY2027 revenue of $130 million to $150 million, implying 160% to 200% growth from FY2026. Strong AI semiconductor testing demand supports the outlook, with equipment deliveries, customer acceptance, and cash conversion now central to achieving those targets.
|
Financial Metric |
Guidance / Consensus |
Reported / Actual |
Surprise |
|
Q4 FY2026 revenue |
$14.089M a year earlier |
$18.835M |
Grew. Up 33.7% year over year. |
|
Q4 non-GAAP diluted EPS |
-$0.01 a year earlier |
$0.11 |
Improved. Up $0.12 per share. |
|
Q4 GAAP diluted EPS |
-$0.10 a year earlier |
$0.04 |
Improved. Swung to a profit. |
|
Q4 GAAP operating loss |
$3.204M loss a year earlier |
$1.206M loss |
Narrowed. Loss fell by $1.998M. |
|
Q4 bookings |
— |
$60.7M |
Record. Orders exceeded Q4 sales threefold. |
|
Backlog at May 29 |
— |
$80.6M |
Built. Effective backlog later reached $100.6M. |
|
FY2026 operating cash flow |
— |
-$3.3M |
Negative. Cash conversion lagged bookings. |
|
FY2027 revenue outlook |
FY2026 actual $50.0M |
130M–150M |
Higher. Implies roughly 160%–200% growth. |
- Q4 revenue rose 33.7% to $18.835 million: Sales advanced from $10.313 million in the prior quarter, indicating faster deliveries. The increase validates the AI production ramp, but full-year revenue of $50.0 million, down from $59.0 million, shows one strong quarter has yet to restore annual scale.
- GAAP diluted EPS recovered to $0.04: Aehr lost $0.10 per share a year earlier, while non-GAAP EPS rose from a $0.01 loss to $0.11 profit. Yet GAAP operating loss was $1.206 million and a $1.846 million tax benefit supported net profit. Recurring operating earnings remain the test.
- Record $60.7 million bookings built a $100.6 million effective backlog: May 29 backlog was $80.6 million; the larger figure includes later bookings. That visibility supports fiscal 2027 guidance, but equipment revenue depends on delivered and accepted systems, so orders can lead earnings by several quarters.
- FY2027 revenue guidance implies 160% to 200% growth: The $130 million to $150 million range compares with fiscal 2026's $50.0 million. Management's 18% to 22% non-GAAP net-income target demands leverage. Shipped FOX and Sonoma systems, rather than more pilot evaluations, must close this gap.
- Fiscal 2026 operating cash use was $3.3 million: Cash and restricted cash reached $116.5 million at May 29, up from $37.1 million at February 27, supporting the ramp. The balance alone does not prove customer cash conversion; collections and working capital must improve as backlog becomes sales.
Aehr Test Systems (AEHR) 2026 Investment Outlook: $110 Bull Case vs. $35 Bear Case
Aehr's 2026 outlook depends on how quickly its record bookings and expanding AI customer programs convert into revenue and positive operating cash flow. The $100.6 million effective backlog supports management's ambitious FY2027 growth outlook, while customer acceptance timing, equipment deliveries, and manufacturing scale remain the key variables shaping the stock's valuation.
The Bull Case: Strong AI Burn-In Demand Pushes AEHR Toward $110
The Bull Case assumes Aehr's lead AI processor customer accepts its $22 million FOX-XP follow-on order within six months, while Sonoma shipments expand across hyperscaler programs. Higher production volume could spread fixed costs across more revenue, turning Q4's $1.206 million GAAP operating loss into sustained profitability and supporting the $130 million to $150 million FY2027 revenue outlook.
A move toward $110 would require the November 2 fiscal Q1 report to confirm accepted shipments, reaffirm FY2027 guidance, and show stronger customer collections. Improving operating cash flow and additional production orders would further support a higher valuation.
The Base Case: Steady Backlog Conversion Keeps AEHR Between $55 and $80
The Base Case assumes Aehr gradually converts its $80.6 million quarter-end backlog, with subsequent orders lifting effective backlog to $100.6 million. FOX-XP production expands at existing customers, while another major supplier remains in evaluation and Sonoma's second processor program ramps in calendar 2027. Revenue grows from the $50.0 million FY2026 base, although shipment timing may create uneven profitability.
AEHR could trade between $55 and $80 if the November report maintains FY2027 guidance and confirms steady deliveries. Faster collections or a second FOX-XP production award could support the upper end, while shipment delays or continued cash outflows would pressure the range.
The Bear Case: Delayed AI Equipment Deliveries Pull AEHR Toward $35
The Bear Case assumes major FOX-XP or Sonoma orders face installation delays or slower customer acceptance, postponing revenue recognition. Q4 bookings of $60.7 million exceeded sales of $18.835 million by more than threefold, so delayed production ramps could weaken operating leverage and prolong cash consumption despite a strong order backlog.
A move toward $35 would become more likely if the November fiscal Q1 report reduces the $130 million to $150 million FY2027 outlook or planned six-month AI shipments slip. Continued operating losses and weaker cash conversion could further pressure valuation.
AEHR Stock Price Forecasts for 2026 By Wall Street Analysts
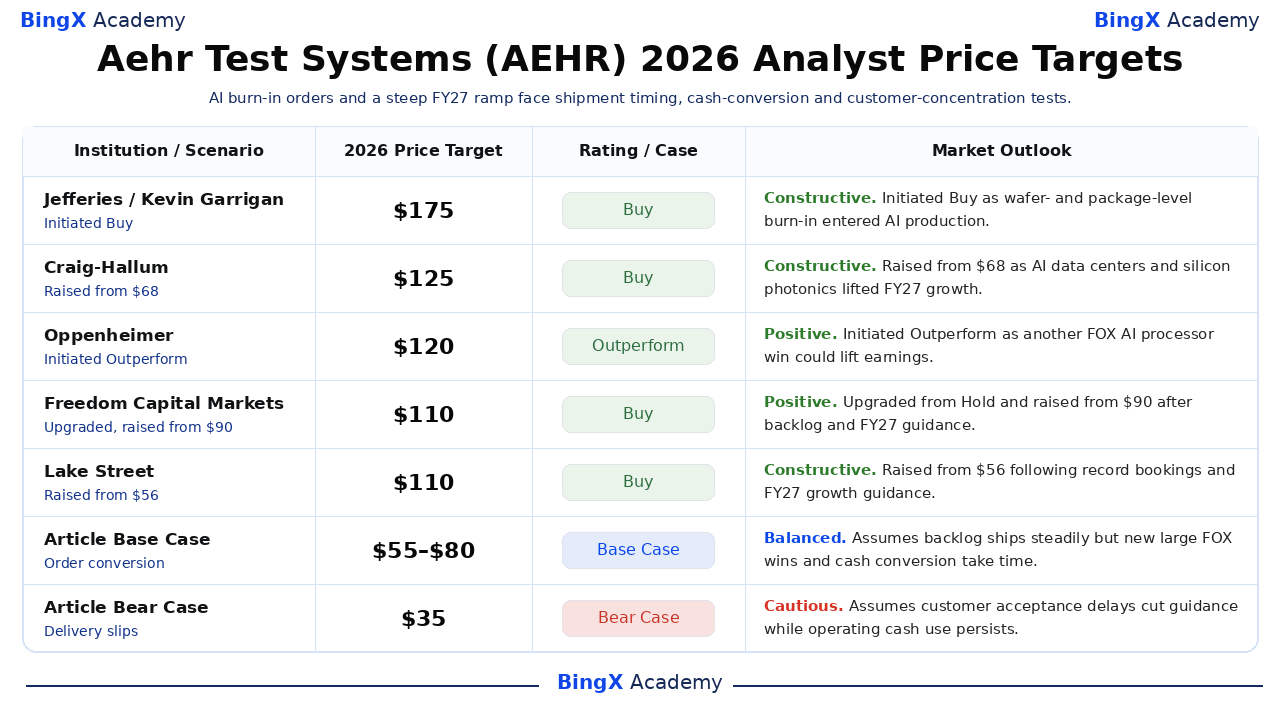
Five dated analyst actions range from $110 to $175, all above Aehr's $63.33 October 19 close. These are institution targets with distinct horizons, not guaranteed end-2026 outcomes. Jefferies emphasized qualified AI production while Oppenheimer considered a second FOX customer. The article's Base and Bear rows are separate editorial scenarios.
|
Institution / Scenario |
2026 Price Target |
Rating / Case |
Market Outlook |
|
Jefferies |
$175 |
Buy |
Constructive. August 14: initiated coverage because Aehr offers wafer- and package-level burn-in qualified for AI production. |
|
Craig-Hallum |
$125 |
Buy |
Constructive. July 15: raised from $68 as FY2027 growth is expected from AI data centers and silicon photonics. |
|
Oppenheimer |
$120 |
Outperform |
Positive. September 10: initiated coverage; another FOX high-volume AI processor customer could raise the earnings ceiling. |
|
Freedom Capital Markets |
$110 |
Buy |
Positive. July 16: upgraded from Hold and raised from $90 after backlog and FY2027 guidance improved visibility. |
|
Lake Street |
$110 |
Buy |
Constructive. July 15: raised from $56 following record bookings and FY2027 growth guidance. |
|
Article Base Case |
55–80 |
Base Case |
Balanced. Assumes backlog ships steadily but new large FOX wins and cash conversion take time. |
|
Article Bear Case |
$35 |
Bear Case |
Cautious. Assumes customer acceptance delays cut guidance while operating cash use persists. |
How to Trade Aehr Test Systems (AEHR) Stock on BingX
Trade Aehr's AI burn-in outlook using BingX TradFi and BingX AI tools. AEHR can react sharply to November 2 results and large orders, so define the catalyst and risk limits before a position.
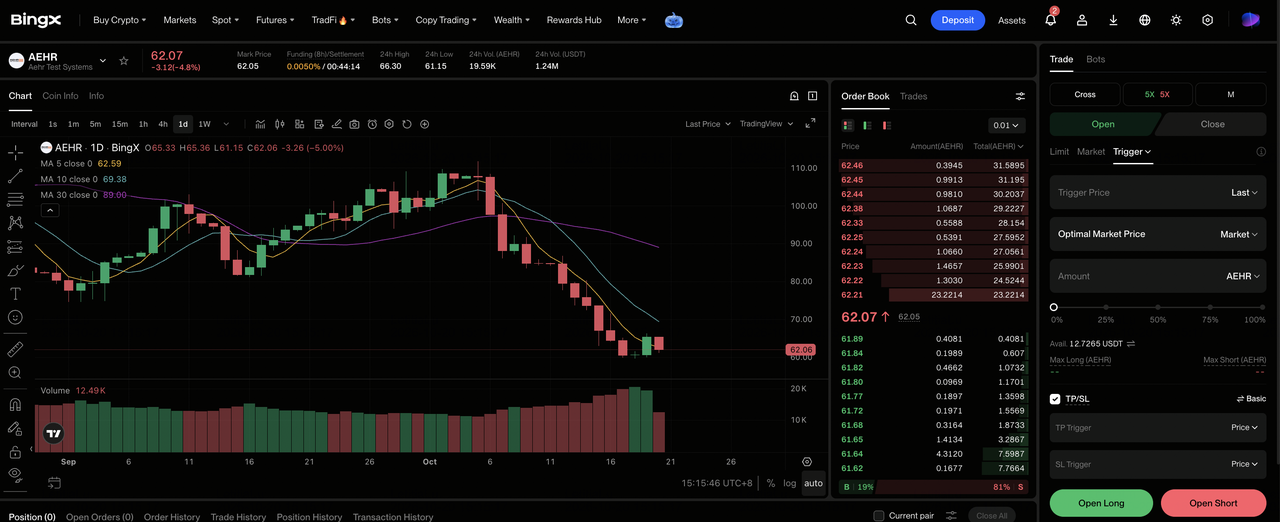
Step 1: Access BingX TradFi. Sign up and navigate to the specialized TradFi section on the BingX exchange dashboard.
Step 2: Select Aehr Test Systems (AEHR). Search for and select the AEHR-USDT perpetual futures contract.
Step 3: Choose your direction. Select Open Long if you expect FOX-XP and Sonoma deliveries to support guidance. Select Open Short if customer acceptance slips or the FY2027 revenue plan is reduced.
Step 4: Select leverage and margin mode. Choose Isolated or Cross-Margin based on your risk tolerance. AEHR's 213.67% year-to-date gain and retreat from its August high make conservative leverage and clear position sizing important.
Step 5: Execute strict risk protocols. Set Take-Profit and Stop-Loss (TP/SL) levels before or immediately after entering the trade. AEHR can react quickly to earnings guidance, FOX deliveries, silicon-photonics orders and major AI customer qualification updates.
Top 5 Risks to Watch for Aehr Test Systems Investors in 2026
A few equipment programs can dominate Aehr's quarterly results, changing future earnings and the value investors assign to those earnings.
- A $130 million to $150 million guide depends on delivery: The range requires roughly 160% to 200% growth from fiscal 2026 sales. Qualification or acceptance delays can shift large system revenue into later quarters, weakening earnings estimates and AEHR's valuation.
- Lead-customer concentration magnifies schedule changes: The $22 million FOX-XP follow-on came from one AI processor customer, while Sonoma depends on a hyperscaler. If either reduces capacity plans, fewer systems ship and fixed costs spread across less revenue, pressuring per-share profit.
- Negative cash conversion can outlast bookings growth: Fiscal 2026 operations used $3.3 million despite strong Q4 orders. More inventory or receivables during the ramp could keep cash flow negative as sales rise, limiting valuation support from the $116.5 million cash balance.
- A second FOX customer remains an evaluation: Management described pilot activity with another top-tier AI processor supplier, not booked high-volume production. Failure to qualify would leave growth more dependent on the incumbent customer and narrow the earnings ceiling assumed by bullish investors.
- A 213.67% YTD rise leaves a volatile valuation: The October 19 close of $63.33 remains below the $147.40 August high. Expectations can reset quickly; a guide qualification or semiconductor capex pullback could compress the price assigned to future sales.
Final Thoughts: Should You Invest in Aehr Test Systems in 2026?
Record $60.7 million bookings and $100.6 million effective backlog substantiate Aehr's fiscal 2027 growth plan. The $22 million FOX-XP and roughly $6 million Sonoma follow-ons show production programs advancing. Yet the latest year delivered only $50.0 million of sales and used $3.3 million of operating cash; Q4 GAAP net profit included a tax benefit despite an operating loss. Accepted delivery and cash collection are the decisive bridge.
The $110 bull case needs accepted shipments, operating earnings and a reaffirmed $130 million to $150 million fiscal 2027 revenue guide. Delays and a guide reset support the $35 bear case; the $55 to $80 base range allows steadier conversion. Conservative investors can watch the scheduled November 2 fiscal Q1 release for revenue, cash movement, shipment timing and the second FOX evaluation before treating backlog as recurring earnings power.
Risk Reminder: Trading and investing in AEHR involves a high risk of capital loss. Concentrated customer programs, semiconductor equipment cycles and AEHR-USDT perpetual leverage, funding and liquidation can amplify losses. Conduct independent research before allocating capital.
Related Reading
- TSMC (TSM) Price Prediction 2026: Can Record AI Demand Lift TSM Stock to $527?
- Coherent (COHR) Price Prediction 2026: Can AI Optics Demand Push COHR Toward $500?
- KLA (KLAC) Price Prediction 2026: Can AI Process-Control Demand Push KLAC Toward $325?
- Lam Research (LRCX) Stock Forecast 2026: Can AI and Memory Demand Push LRCX Toward $390?
- ASML Holding (ASML) Price Prediction 2026: Can EUV Demand Push ASML Toward $2,500?
