Figma (FIG) provides a browser-based platform where designers, developers, product managers and marketers build digital products together. Figma Design remains the core collaborative canvas, while FigJam, Dev Mode, Slides, Sites, Make and newer AI tools extend the platform from ideation into code, publishing and content production. That broader workflow creates more ways to monetize each organization, though it also leaves the stock sensitive to generative-AI competition, seat demand and the cost of running AI features.
Its latest quarter showed rapid adoption alongside a widening profitability debate. Figma Q2 2026 revenue reached $370.1 million, up 48% year over year and about $18.1 million above consensus, while adjusted EPS of $0.08 doubled the $0.04 estimate. Net dollar retention reached 136%, though GAAP operating loss widened to $117.3 million and free-cash-flow margin fell to 14%, making investment discipline central to the outlook.
The FIG stock forecast for 2026 now centers on two competing views:
- The AI platform case: Figma converts more enterprise users to paid AI credits, expands beyond designers and sustains revenue growth above conventional software peers.
- The disruption and margin case: AI lowers design barriers but compresses paid seats, raises infrastructure costs and weakens the cash-flow profile needed to support a premium multiple.
This guide breaks down the FIG stock forecast, 2026 price scenarios, key risks and analyst outlooks, drawing on Figma's August 5 Q2 2026 earnings release, quarterly filing and market data through September 9, plus how to trade FIG stock futures on BingX TradFi with USDT collateral.
Top 5 Things for Figma Investors to Know in September 2026
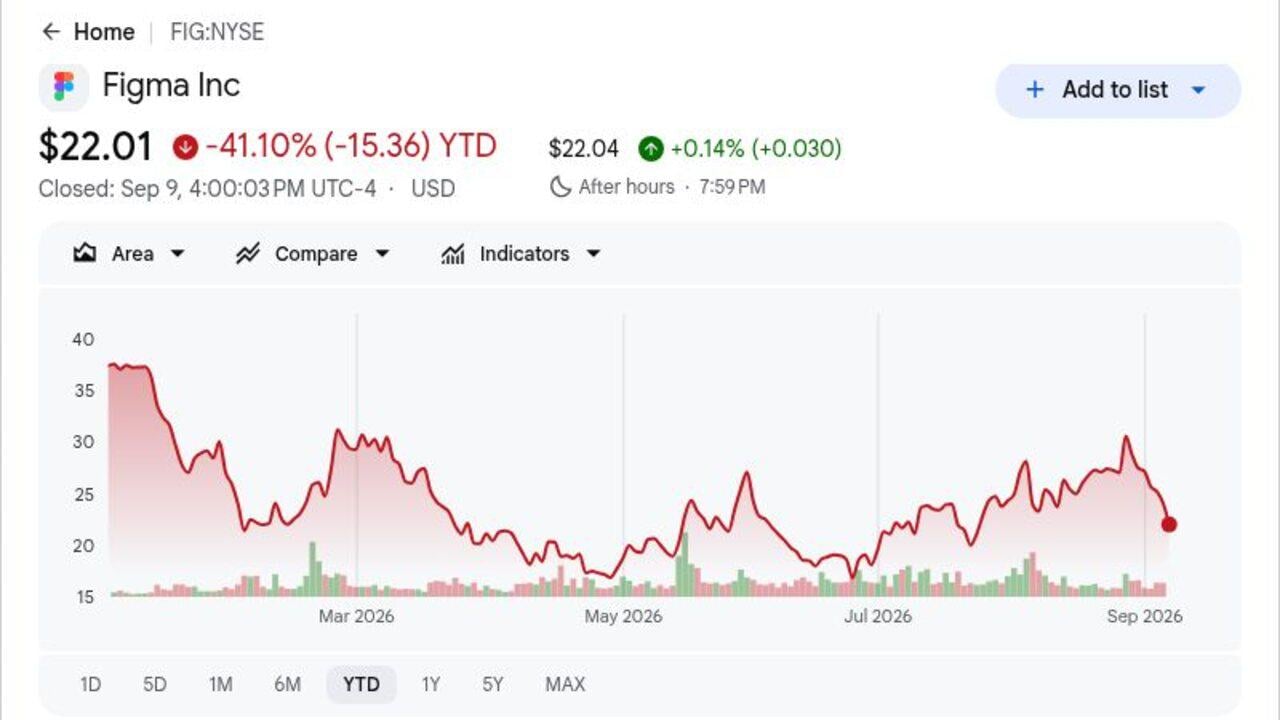
- FIG closed at $22.01 after falling 41.10% YTD: The close sat below the $33 IPO price even though Q2 revenue expanded 48%. Investors are demanding much clearer proof that Figma can convert AI usage into durable cash flow.
- Q2 revenue reached $370.1 million and beat consensus by about $18.1 million: Growth accelerated to 48% year over year for a third consecutive quarter, while adjusted EPS of $0.08 topped the $0.04 estimate. The beat confirms healthy demand across the platform, though it did not settle the cost debate.
- Net dollar retention reached 136% as customers expanded usage: The measure indicates existing customers spent 36% more after churn and contraction, supported by additional seats, products and AI credits. More than half of paid customers above $10,000 in annual recurring revenue used Figma's agent weekly by late July.
- FY2026 revenue guidance rose to $1.463 billion to $1.467 billion: The $1.465 billion midpoint exceeded the prior Street view of about $1.437 billion by $28 million. Management's higher outlook supports the growth case, though a 14% free-cash-flow margin leaves less room for execution mistakes.
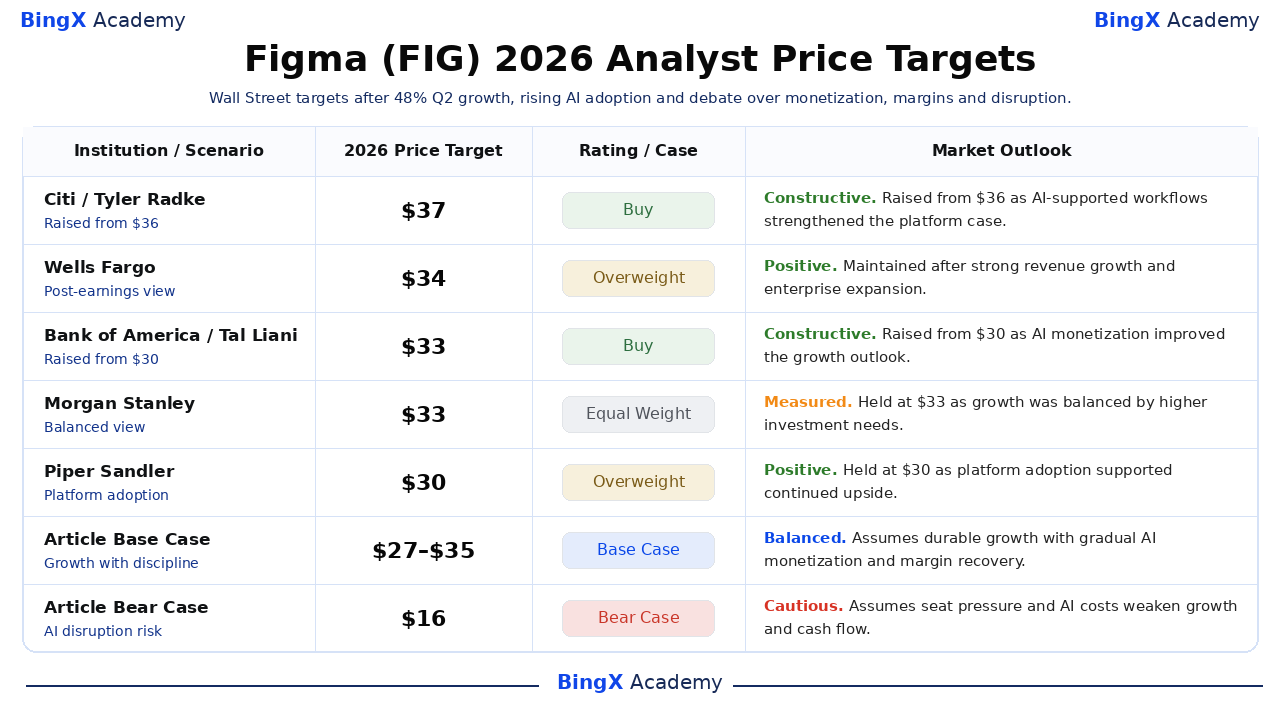
- Five recent analyst targets span $30 to $37: Citi's $37 target sits 68% above the reference close, while Piper Sandler's $30 view implies 36% upside. The range captures meaningfully different institutional assumptions about AI monetization and future paid-seat compression risks.
What Is Figma (FIG)?
Figma is a cloud software company built around multiplayer collaboration for digital-product development. Figma Design combines interface design, prototyping and design systems in one browser workspace, while FigJam supports brainstorming. Dev Mode connects specifications to engineering, and Slides, Sites, Make, Buzz and Draw extend the platform into presentations, publishing, code and branded content. Revenue comes mainly from professional, organization and enterprise subscriptions, with usage-based AI credits adding another path.
Figma's long-term strategy is to become the shared system of record for product creation rather than a design-only application. It connects designers, developers, product managers and marketers, with AI creation and workflow automation widening the user base. Figma says 95% of the Fortune 500 used its products as of March 2025, with named customers including Microsoft, Netflix, Airbnb, Atlassian, GitHub, Stripe and Zoom. Integrations with OpenAI, Google and Anthropic also connect design context to major AI ecosystems.
Figma (FIG) Q2 2026 Earnings Overview: Revenue Growth, AI Adoption and Margin Pressure
Figma delivered Q2 2026 revenue of $370.1 million versus roughly $352 million expected, adjusted EPS of $0.08 versus $0.04 expected and 48% annual growth. Net dollar retention reached 136%, while more than 50% of paid customers above $10,000 in ARR used Figma's agent weekly. Management raised FY2026 revenue guidance to $1.463 billion to $1.467 billion, though a $117.3 million GAAP operating loss and 14% free-cash-flow margin showed the cost of product and AI investment.
|
Financial Metric |
Guidance / Consensus |
Reported / Actual |
Surprise |
|
Q2 2026 revenue |
$352M consensus |
$370.1M |
Beat. About $18.1M above consensus; up 48% YoY. |
|
Q2 adjusted EPS |
$0.04 consensus |
$0.08 |
Beat. Double the consensus estimate. |
|
Q2 GAAP operating result |
$2.0M income a year earlier |
$117.3M loss |
Declined. AI and platform investment increased costs. |
|
Net dollar retention |
— |
136% |
Strong. Existing customers expanded spending by 36% net. |
|
Free-cash-flow margin |
24% a year earlier |
14% |
Compressed. Investment outpaced cash-flow growth. |
|
Enterprise AI-agent usage |
— |
More than 50% |
Expanded. Weekly use among paid customers above $10K ARR. |
|
FY2026 revenue outlook |
$1.437B consensus |
$1.463B–$1.467B |
Raised. Midpoint exceeds consensus by about $28M. |
- Revenue of $370.1 million grew 48% and beat consensus by $18.1 million: Growth accelerated for a third straight quarter, showing that the product-development platform is still expanding despite fears that generative AI could replace portions of design work. Sustaining that pace would support a higher revenue multiple.
- Adjusted EPS of $0.08 doubled the $0.04 estimate: The result showed non-GAAP earnings can remain positive during aggressive product investment. GAAP operating loss nevertheless reached $117.3 million, so investors must distinguish adjusted profitability from the economic cost of stock compensation and development.
- Net dollar retention of 136% showed 36% customer expansion: Additional seats, products and AI credits more than offset churn and contraction. That expansion matters because it supports growth without relying entirely on new logos, though AI-driven seat consolidation could test retention in future periods.
- Free-cash-flow margin fell 10 percentage points to 14%: The prior-year margin was 24%, and increased computing and product costs absorbed part of the revenue growth. A durable re-rating requires AI credit revenue and falling inference costs to rebuild cash conversion rather than simply increase usage.
- The $1.465 billion guidance midpoint topped consensus by about $28 million: Management lifted its range to $1.463 billion to $1.467 billion after the revenue beat. Delivery would validate near-term demand, though the larger investment question remains whether growth can translate into expanding GAAP margins.
Figma (FIG) 2026 Investment Outlook: $45 Bull Case vs. $16 Bear Case
The 2026 debate turns on whether Figma's 48% growth and 136% retention can outweigh lower cash conversion and AI disruption fears. Upside requires proof that AI credits and broader workflows improve revenue per customer without eroding seat demand.
The Bull Case: Strong AI Adoption and Platform Expansion Push FIG Toward $45
The Bull Case assumes Figma expands beyond design into coding, marketing, and broader collaborative workflows, with AI credits creating an additional revenue stream. Revenue growth stays above 35%, net retention remains near 130%, and lower model costs improve the economics of Figma Make and other AI tools.
A move toward $45 would require FY2026 revenue near or above the $1.467 billion guidance ceiling, recovering free-cash-flow margins, and stronger paid AI usage across enterprise customers. Continued adoption among developers and marketers would provide the clearest confirmation.
The Base Case: Steady Platform Growth Keeps FIG Between $27 and $35
The Base Case assumes Figma’s core collaboration products remain strong while AI features require continued investment. Expansion within existing customers supports growth, but slower cash-flow improvement and some pressure on traditional design seats limit further valuation expansion.
Under this scenario, FIG could trade mainly between $27 and $35. Revenue near the $1.465 billion midpoint, retention above 125%, and stable adjusted profitability would support the range, while weaker AI-credit conversion would cap the upside.
The Bear Case: AI Competition and Margin Pressure Pull FIG Toward $16
The Bear Case assumes generative AI tools reduce demand for some traditional design seats faster than Figma can offset with developer, marketer, and usage-based revenue. Higher inference costs and continued platform spending would keep profitability under pressure.
A move toward $16 would become more likely if retention falls below 120%, revenue guidance is cut, or free-cash-flow margin drops into single digits. Stronger competition from Adobe, Canva, or AI-native creation tools could add further pressure.
FIG Stock Price Forecasts for 2026 By Wall Street Analysts
These five dated institutional actions span $30 to $37 and are sorted from highest to lowest. They reflect different views of growth and margins. The final Base and Bear rows are BingX Academy editorial scenarios rather than Wall Street forecasts or guaranteed outcomes.
|
Institution / Scenario |
2026 Price Target |
Rating / Case |
Market Outlook |
|
Citi |
$37 |
Buy |
Constructive. August 7: raised from $36 as AI-supported structured workflows strengthened the long-term platform case. |
|
Wells Fargo |
$34 |
Overweight |
Positive. August 6: maintained after strong revenue growth and enterprise expansion supported the opportunity. |
|
Bank of America |
$33 |
Buy |
Constructive. August 19: raised from $30 as AI monetization improved the growth outlook. |
|
Morgan Stanley |
$33 |
Equal Weight |
Measured. August 6: maintained as rapid growth was balanced by higher investment needs and execution risk. |
|
Piper Sandler |
$30 |
Overweight |
Positive. August 6: maintained as platform adoption and AI products supported continued upside. |
|
Article Base Case |
$27–$35 |
Base Case |
Balanced. Assumes durable growth with gradual AI monetization and margin recovery. |
|
Article Bear Case |
$16 |
Bear Case |
Cautious. Assumes seat pressure and AI costs weaken growth and cash flow. |
How to Trade Figma (FIG) Stock on BingX
Trade Figma's AI-monetization, enterprise-expansion and margin outlook using BingX TradFi and BingX AI tools. Because FIG can react sharply to product announcements, guidance and software-sector sentiment, traders should define both the catalyst and risk limits before entering a position. Stock perpetual futures use leverage and can magnify both gains and losses. They do not provide ownership, voting rights or dividends, and liquidation can occur when margin becomes insufficient.
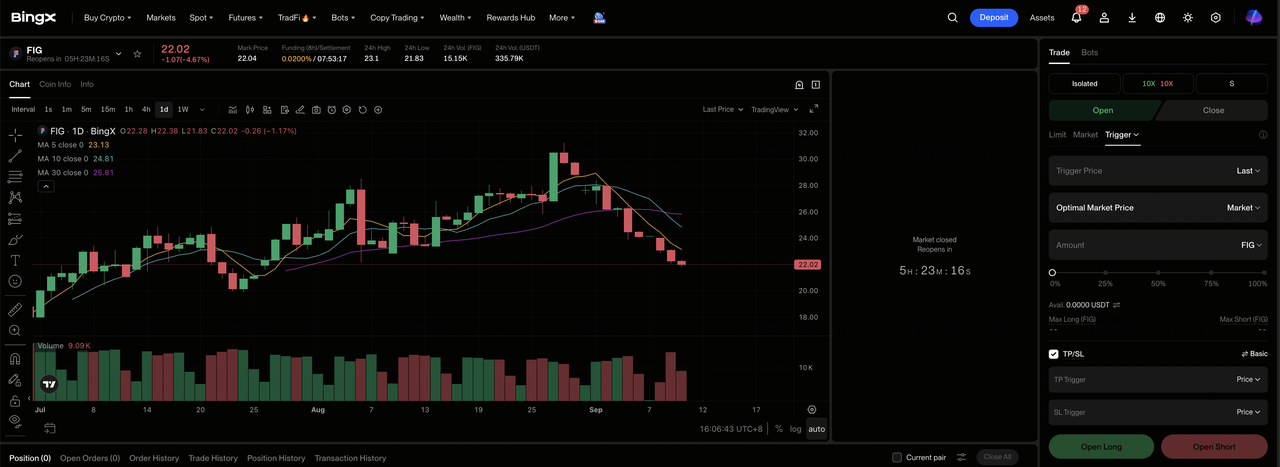
Step 1: Access BingX TradFi. Sign up and navigate to the specialized TradFi section on the BingX exchange dashboard.
Step 2: Select Figma (FIG). Search for and select the FIG-USDT perpetual futures contract.
Step 3: Choose your direction. Select Open Long if AI credits, enterprise expansion and margins support higher estimates. Select Open Short if seat compression or product costs weaken growth and cash conversion.
Step 4: Select leverage and margin mode. Choose Isolated or Cross-Margin based on your risk tolerance. The 41.10% YTD decline shows why conservative leverage and clear position sizing are important.
Step 5: Execute strict risk protocols. Set Take-Profit and Stop-Loss (TP/SL) levels before or immediately after entering the trade. FIG can react quickly to earnings, AI releases, guidance, retention and software-sector valuation changes.
Top 5 Risks to Watch for Figma Investors in 2026
Figma’s AI expansion creates a larger growth opportunity, but it can also pressure paid seats, infrastructure costs, cash conversion, profitability and valuation.
- AI could reduce demand for paid design seats: Net retention was 136%, but if smaller teams can complete more work with AI, companies may cut conventional design seats before usage-based revenue fully replaces them. That would slow expansion revenue from existing customers.
- A 14% free-cash-flow margin leaves less room for cost pressure: Higher inference, hosting and development costs could prevent strong revenue growth from translating into better cash generation. Another decline from the prior 24% margin would raise concerns about operating leverage.
- A $117.3 million GAAP operating loss keeps profitability under pressure: Heavy stock compensation and product investment widen the gap between adjusted earnings and shareholder economics. If dilution remains high without faster cash-flow growth, investors may assign Figma a lower revenue multiple.
- Competition spans Adobe, Canva and AI-native products: Rivals can pressure pricing, customer acquisition and product differentiation, forcing Figma to spend more to defend its collaborative advantage. Lower switching costs could also weaken retention.
- Limited public-market history can amplify volatility: Lockup expirations, insider sales and changes in institutional ownership can add selling pressure even when operating results remain solid. A larger tradable float may weigh on the stock until new supply is absorbed.
Final Thoughts: Should You Invest in Figma in 2026?
Figma's operating momentum is increasingly clear. Revenue grew 48%, net dollar retention reached 136% and enterprise AI-agent adoption passed 50% among larger paid customers. The company also raised full-year revenue guidance, showing that collaborative product development continues to attract spending even as generative AI changes how design work is completed.
The Bull Case requires AI credits and platform expansion to rebuild cash-flow leverage, while the Bear Case centers on seat compression, competition and sustained GAAP losses. Conservative traders may wait for free-cash-flow margin to stabilize, retention to remain above 125% and paid AI usage to show that growth is becoming more efficient.
Risk Reminder: Trading and investing in equities like FIG involves a high risk of capital loss. AI competition, usage-cost volatility, post-IPO supply and leverage can amplify losses. Conduct independent research before allocating capital.
Related Reading
- Palantir (PLTR) Stock Price Prediction 2026: Can 149% U.S. Commercial Growth Push PLTR Toward $255?
- AppLovin (APP) 2026 Price Prediction: Can AXON 2.0 and E-Commerce Spark a $750 Rebound?
- Alphabet (GOOGL) Price Prediction 2026: Can 82% Cloud Growth and AI Push GOOGL Stock to $430?
- Snap Inc. (SNAP) Price Prediction 2026: Can Advertising and Subscription Growth Push SNAP Toward $10?
- Reddit (RDDT) Price Prediction 2026: Can AI Data Opportunities Push RDDT Toward $300?
