


Applied Digital (APLD) designs, develops, owns and operates high-density data centers for artificial intelligence, machine learning and other accelerated-computing workloads. Its Polaris Forge and Delta Forge campuses turn low-cost power and purpose-built cooling into long-term leased capacity for hyperscalers. The shift from crypto hosting toward AI infrastructure creates a larger contracted opportunity, while making the stock sensitive to construction schedules, customer concentration and project financing.
Applied Digital Fiscal Q4 2026 showed how quickly the model is changing. Revenue increased 407% to $258.7 million, HPC Hosting generated $203.0 million and adjusted EBITDA reached $42.4 million versus $1.0 million a year earlier. Applied Digital ended the year with 1.4 GW of contracted critical IT load and $36 billion of base-term lease revenue, although $5.0 billion of debt and a $110.6 million GAAP loss keep funding discipline central.
The APLD stock forecast for 2026 now centers on two competing views:
- The AI-campus delivery and backlog-conversion case: on-time AI Factory delivery and stable project financing could convert $36 billion of contracted revenue into recurring rent and improving operating leverage.
- The financing and construction case: delivery delays, expensive debt or equity dilution could slow rent growth and reduce the per-share value of the contracted backlog.
This guide breaks down the APLD stock forecast, 2026 price scenarios, key risks and analyst outlooks, drawing on Applied Digital's July 27 fiscal Q4 2026 earnings release, 10-K and market data through September 18, plus how to trade APLD stock futures on BingX TradFi with USDT collateral.
Top 5 Things for Applied Digital Investors to Know in September 2026
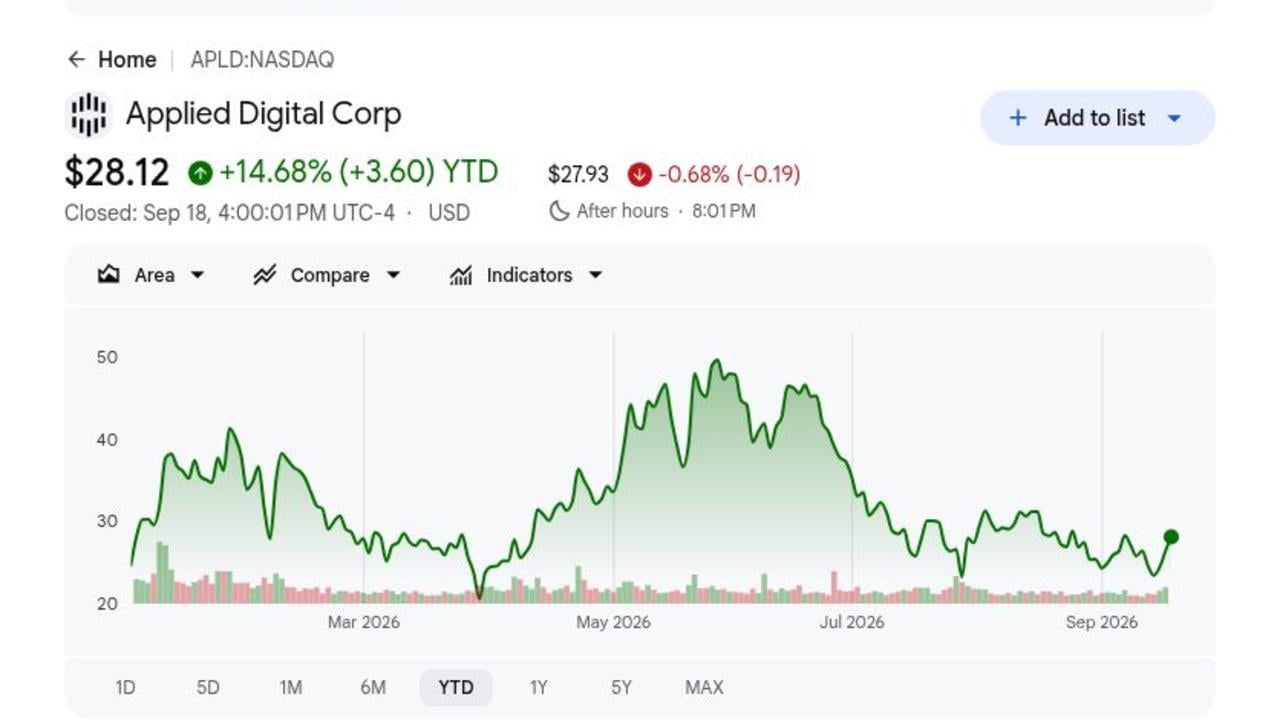
- APLD closed at $28.12 on September 18 after gaining 14.68% in 2026: The gain shows that investors are rewarding Applied Digital's AI data-center buildout, though the stock now needs project delivery to justify further upside. Five selected analyst targets range from $58 to $90.
- Fiscal Q4 revenue reached $258.7 million, up 407%: The quarter included $152.4 million of tenant fit-out services and $44.1 million of base rent. The mix shows Applied Digital is moving from development work toward recurring AI-campus revenue.
- HPC Hosting generated $203.0 million of revenue: The segment also produced $26.2 million of operating profit and now exceeds the legacy Data Center Hosting business, which generated $37.3 million from 286 MW of crypto-hosting capacity.
- Five campuses support 1.4 GW and $36 billion of base-term contracts: Renewal options could raise total contract value to $86 billion. The backlog provides long-term visibility, though revenue still depends on delivering Polaris Forge and Delta Forge buildings on schedule.
- Applied Digital held $4.2 billion of cash against $5.0 billion of debt: The company has used secured project financing, including $2.15 billion and $1.59 billion note offerings, to fund construction. Liquidity is substantial, but interest costs and refinancing terms will determine how much lease economics reach shareholders.
What Is Applied Digital (APLD)?
Applied Digital is a U.S. digital-infrastructure developer that combines site selection, power procurement, design, construction and operations for high-performance computing (HPC) customers. Its AI Factory campuses use high-density electrical systems, closed-loop cooling and modular building designs to support GPU clusters. The company earns tenant fit-out fees, base rent, recoveries and hosting revenue. It also operates 286 MW of crypto-mining hosting capacity, which supplies cash flow as the larger HPC portfolio moves into service.
The long-term strategy centers on repeating the Polaris Forge campus model across multiple power-rich U.S. markets. CoreWeave leases capacity at Polaris Forge 1, while another investment-grade hyperscaler signed long-term agreements across Delta Forge 1, Polaris Forge 3 and Delta Forge 2. Applied Digital is also working with Base Electron on roughly 1.2 GW of potential natural-gas generation and separated its cloud-services business into ChronoScale, allowing management to concentrate capital and operations on owned data centers.
Read More: Top High-Performance Computing (HPC) Stocks to Watch in 2026: Accelerated Computing Market Leaders
Applied Digital (APLD) Q4 FY2026 Earnings Overview: AI Factory Revenue Scales as Financing Needs Rise
Applied Digital reported fiscal Q4 revenue of $258.7 million, up 407%, adjusted diluted EPS of $0.04 versus a $0.03 loss a year earlier, adjusted EBITDA of $42.4 million versus $1.0 million and HPC Hosting revenue of $203.0 million. Full-year revenue reached $611.3 million, while year-end cash and restricted cash totaled $4.2 billion against $5.0 billion of debt. The central tradeoff is rapid contracted growth versus the capital required to deliver it.
Read More: Applied Digital (APLD) Q4 FY2026 Earnings News: $18.7M Revenue Beat Offset by Wider GAAP Loss
|
Financial Metric |
Guidance / Consensus |
Reported / Actual |
Surprise |
|
Q4 FY2026 revenue |
Q4 FY2025: $51.1M |
$258.7M |
Grew. Up 407% year over year. |
|
Q4 adjusted diluted EPS |
Q4 FY2025: -$0.03 |
$0.04 |
Improved. Returned to adjusted profitability. |
|
Q4 GAAP net loss |
Q4 FY2025: $53.1M loss |
$110.6M loss |
Widened. Stock compensation and growth costs increased. |
|
Q4 adjusted EBITDA |
Q4 FY2025: $1.0M |
$42.4M |
Improved. New HPC rent and fit-out activity scaled. |
|
Q4 HPC Hosting revenue |
— |
$203.0M |
Expanded. Included $44.1M of base rent. |
|
FY2026 revenue |
FY2025 base implies 167% growth |
$611.3M |
Grew. AI Factory revenue changed company scale. |
|
Contracted critical IT load |
— |
1.4GW |
Expanded. Five campuses support $36B base revenue. |
|
Cash and restricted cash |
— |
$4.2B |
Strong. Balanced against $5.0B of debt. |
- Revenue of $258.7 million grew 407%: Services revenue rose 308% to $208.2 million, led by $152.4 million of tenant fit-out work tied to HPC campus delivery. The result shows how quickly construction and leasing activity are scaling.
- Adjusted EPS improved to $0.04: Adjusted net income reached $12.9 million versus a $7.6 million loss a year earlier. The improvement shows stronger operating scale before the full impact of GAAP stock compensation.
- HPC Hosting revenue reached $203.0 million: Base rent contributed $44.1 million and tenant recoveries added $6.5 million. The mix is beginning to shift from construction-related revenue toward recurring lease income.
- Adjusted EBITDA increased to $42.4 million from $1.0 million: Net operating income reached $39.9 million, showing that live buildings can generate positive property-level economics even while consolidated losses remain high.
- $4.2 billion of liquidity supports 1.4 GW of contracted construction: The cash balance is substantial, though $5.0 billion of debt and multiple campuses under development keep financing costs and delivery timing central to per-share returns.
Applied Digital (APLD) 2026 Investment Outlook: $90 Bull Case vs. $18 Bear Case
Applied Digital's 2026 outlook depends on whether its contracted AI data-center pipeline can move into live capacity on schedule without excessive financing or dilution. The upside comes from converting backlog into recurring rent, while construction timing and capital costs remain the main risks.
The Bull Case: On-Time AI Data Center Delivery Pushes APLD Toward $90
The Bull Case assumes Polaris Forge and Delta Forge buildings enter service on schedule, turning 1.4 GW of contracts into base rent and property-level operating income. The $36 billion base-term backlog and repeat hyperscaler awards would then support better financing terms and lower execution risk.
A move toward $90 would require construction milestones to stay intact, live capacity to expand beyond 175 MW and lease-backed financing to avoid heavy equity issuance. Rising base rent, positive consolidated free cash flow and more investment-grade customers would strengthen the case.
The Base Case: Steady Backlog Conversion Keeps APLD Between $40 and $60
The Base Case assumes contracted projects continue moving into service, though high interest expense, stock compensation and staggered campus openings slow per-share earnings growth. Tenant fit-out revenue remains uneven while recurring rent becomes a larger share of revenue.
Under this scenario, APLD could trade mainly between $40 and $60. On-time 2027 openings, stable construction budgets and debt funding tied to signed leases would support the range. Delays across multiple campuses or materially higher financing costs would weaken the upper end.
The Bear Case: Project Delays and Higher Funding Costs Pull APLD Toward $18
The Bear Case assumes campuses slip, customers change deployment schedules or capital markets demand higher returns. Applied Digital would then carry construction spending and interest expense for longer before contracted rent begins.
A move toward $18 would become more likely if live capacity stalls near 175 MW, project debt rises materially above lease-backed needs or equity issuance accelerates. Contracted revenue could remain large, but slower delivery and more dilution would pressure per-share value.
APLD Stock Price Forecasts for 2026 By Wall Street Analysts
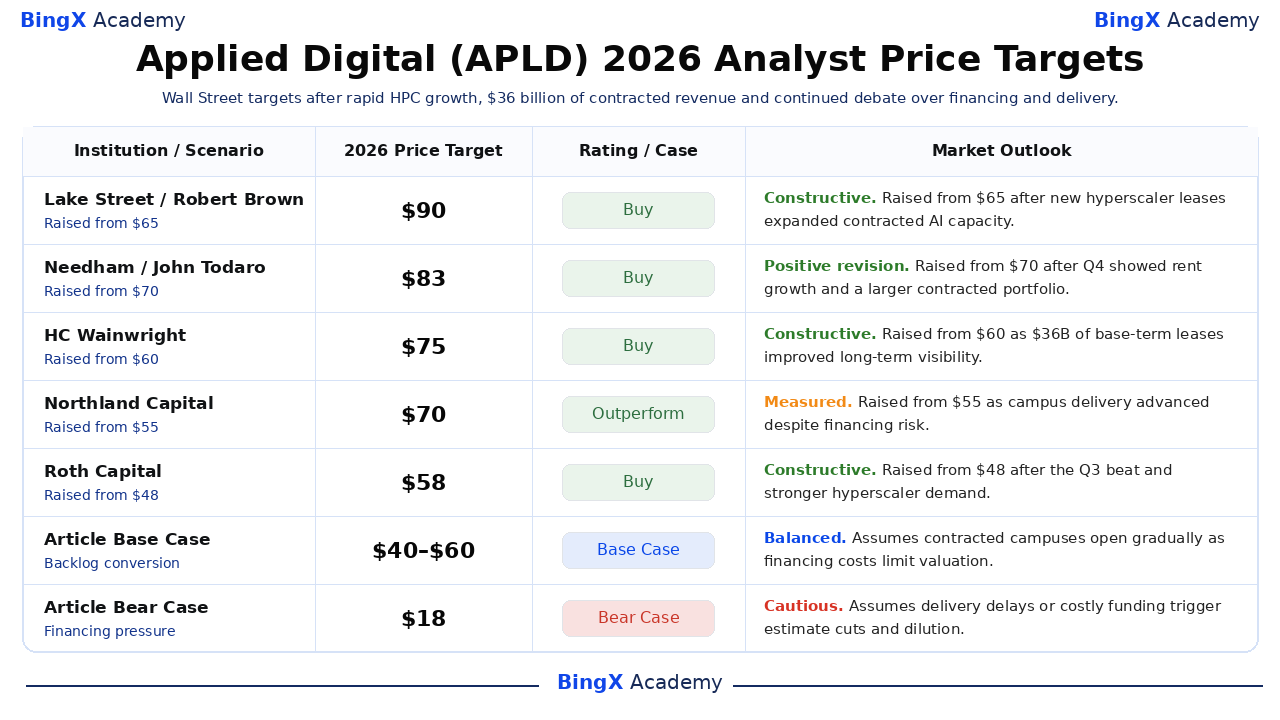
These dated third-party actions show a wide $58 to $90 target range, reflecting different assumptions about construction, financing and lease conversion. Article scenarios remain explicitly separate from Wall Street targets. Each target is a reference point based on the firm’s stated assumptions, not a guaranteed outcome or the article’s own forecast.
|
Institution / Scenario |
2026 Price Target |
Rating / Case |
Market Outlook |
|
Lake Street |
$90 |
Buy |
Constructive. June 9: raised from $65 after a new hyperscaler lease expanded contracted capacity. |
|
Needham |
$83 |
Buy |
Positive revision. July 28: raised from $70 after Q4 showed rent growth and backlog expansion. |
|
HC Wainwright |
$75 |
Buy |
Constructive. July 29: raised from $60 as $36 billion of leases improved visibility. |
|
Northland Capital |
$70 |
Outperform |
Measured. July 28: raised from $55 as delivery advanced despite financing risk. |
|
Roth Capital |
$58 |
Buy |
Constructive. April 9: raised from $48 after the Q3 beat and hyperscaler demand. |
|
Article Base Case |
$40 to $60 |
Base Case |
Balanced. Assumes backlog converts gradually as financing costs limit valuation. |
|
Article Bear Case |
$18 |
Bear Case |
Cautious. Assumes delays or costly funding trigger cuts and dilution. |
How to Trade Applied Digital (APLD) Stock on BingX
Trade Applied Digital's AI-campus delivery, contracted-backlog and financing outlook using BingX TradFi and BingX AI tools. Because APLD can react sharply to lease announcements, construction milestones and financing terms, traders should define both the catalyst and risk limits before entering a position.
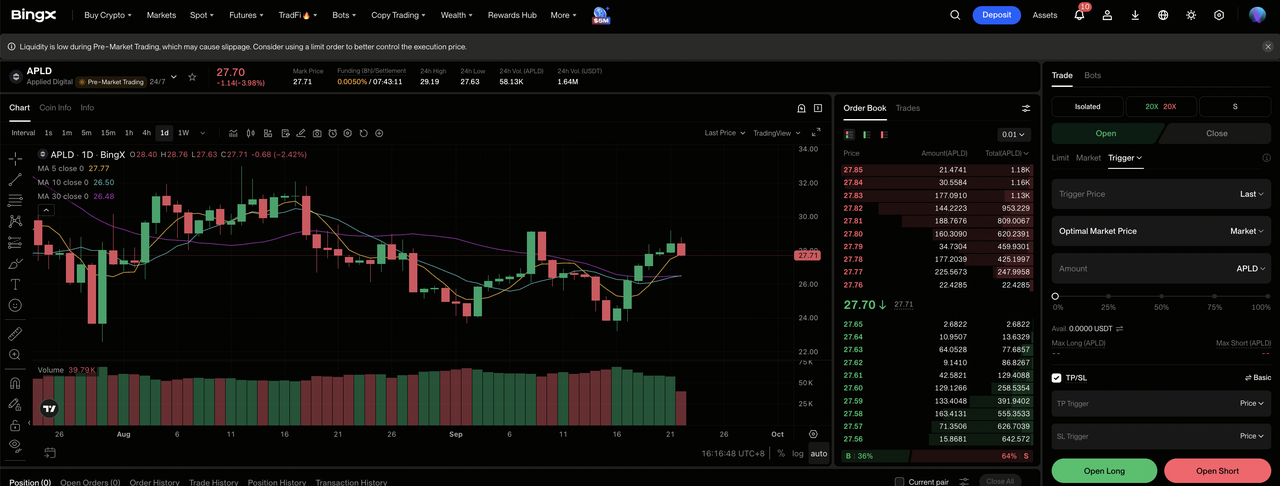
Step 1: Access BingX TradFi. Sign up and navigate to the specialized TradFi section on the BingX exchange dashboard.
Step 2: Select Applied Digital (APLD). Search for and select the APLD-USDT perpetual futures contract.
Step 3: Choose your direction. Select Open Long if you expect on-time campuses and rising base rent. Select Open Short if you expect delivery delays, expensive financing or dilution.
Step 4: Select leverage and margin mode. Choose Isolated or Cross-Margin based on your risk tolerance. The 14.68% YTD gain despite rapid revenue growth shows why conservative leverage and clear position sizing are important.
Step 5: Execute strict risk protocols. Set Take-Profit and Stop-Loss (TP/SL) levels before or immediately after entering the trade. APLD can react quickly to customer leases, financing, construction milestones, power availability and earnings.
Top 5 Risks to Watch for Applied Digital Investors in 2026
Applied Digital's signed leases improve visibility, but major execution risks still stand between contract value and per-share cash flow. These risks can affect financing needs, project returns and valuation.
- Construction delays could postpone years of rent: Five campuses remain at different development stages. Missed delivery dates would extend interest and construction costs before lease revenue begins.
- Customer concentration could amplify deployment changes: Three newer leases come from the same investment-grade hyperscaler, while CoreWeave remains central at Polaris Forge 1. A delay or contract change from one major customer could affect utilization and revenue timing.
- Financing costs could absorb project returns: Applied Digital ended May with $5.0 billion of debt and has issued secured notes at 6.75% to 7.00%. Higher interest costs leave less project cash flow available to equity holders.
- Stock compensation and dilution could weaken per-share growth: Q4 stock-based compensation increased by $116.8 million and contributed to the $110.6 million GAAP loss. More equity issuance could reduce the benefit of higher revenue and property income on a per-share basis.
- Power and permitting constraints could limit expansion: The additional 1.7 GW being marketed still requires grid access, generation, permits and community support. Delays could prevent planned capacity from becoming leaseable infrastructure.
Final Thoughts: Should You Invest in Applied Digital in 2026?
Applied Digital has moved from a development story toward a contracted AI data center platform, with $258.7 million of quarterly revenue, 1.4 GW under lease and $36 billion of base-term contract value. Its first 175 MW of Polaris Forge capacity shows that management can move projects into service. The remaining question is how efficiently that operating progress converts into sustainable free cash flow per share.
The Bull Case needs repeated on-time delivery and disciplined funding to support $90. The Bear Case reflects delays, higher interest expense and dilution that pull APLD toward $18. Conservative traders may watch live megawatts, base rent, property-level NOI, project debt, customer concentration and share count before treating the backlog as equivalent to realized value.
Risk Reminder: Trading and investing in equities like APLD involves a high risk of capital loss. Construction, financing, customer concentration, power availability, dilution and leveraged trading can produce rapid losses. Conduct independent research before allocating capital.
Related Reading
- Top AI Data Center Stocks to Buy in 2026: Cloud Servers and AI Compute Infrastructure
- Top High-Performance Computing (HPC) Stocks to Watch in 2026: Accelerated Computing Market Leaders
- Top AI Compute and GPU Stocks to Buy in 2026: The Shift to Inference and Custom Silicon
- CoreWeave (CRWV) Stock Outlook and Price Prediction 2026: Is CRWV a Good Investment?
- NVIDIA (NVDA) Price Prediction 2026: Can AI Infrastructure Growth Drive NVDA Toward $420?
