
SLB (SLB) is a global energy-technology company supplying reservoir characterization, drilling, completions, production systems, digital software and integrated services. International and offshore activity remain central to the business, while ChampionX, SLB OneSubsea, Digital and Data Center Solutions are broadening the revenue mix. That diversification creates new growth routes, though results remain sensitive to producer spending, regional access, project timing and integration execution.
The latest quarter showed improving sequential momentum against weaker year-over-year profitability. SLB Q2 2026 revenue reached $8.972 billion, up 3% sequentially and 5% year over year, while adjusted EPS of $0.55 exceeded the $0.51 consensus. Adjusted EBITDA margin expanded 83 basis points sequentially to 21.2%, though EBITDA remained 7% below the prior year. The investment case depends on converting geographic and portfolio breadth into higher cash flow.
The SLB stock forecast for 2026 now centers on two competing views:
- The international, digital and data-center growth case: Offshore activity, ChampionX integration, 18% Digital growth and the planned Kelvion acquisition could widen SLB's earnings base and push the stock toward $75.
- The disruption and capital-allocation case: Middle East interruptions, lower underlying revenue excluding ChampionX and execution on a $4.1 billion acquisition could weaken margins and pull shares toward $45.
This guide breaks down the SLB stock forecast, 2026 price scenarios, key risks and analyst outlooks, drawing on SLB's July 24 Q2 2026 earnings release, quarterly filing and market data through September 15, plus how to trade SLB stock futures on BingX TradFi with USDT collateral.
Top 5 Things for SLB Investors to Know in September 2026
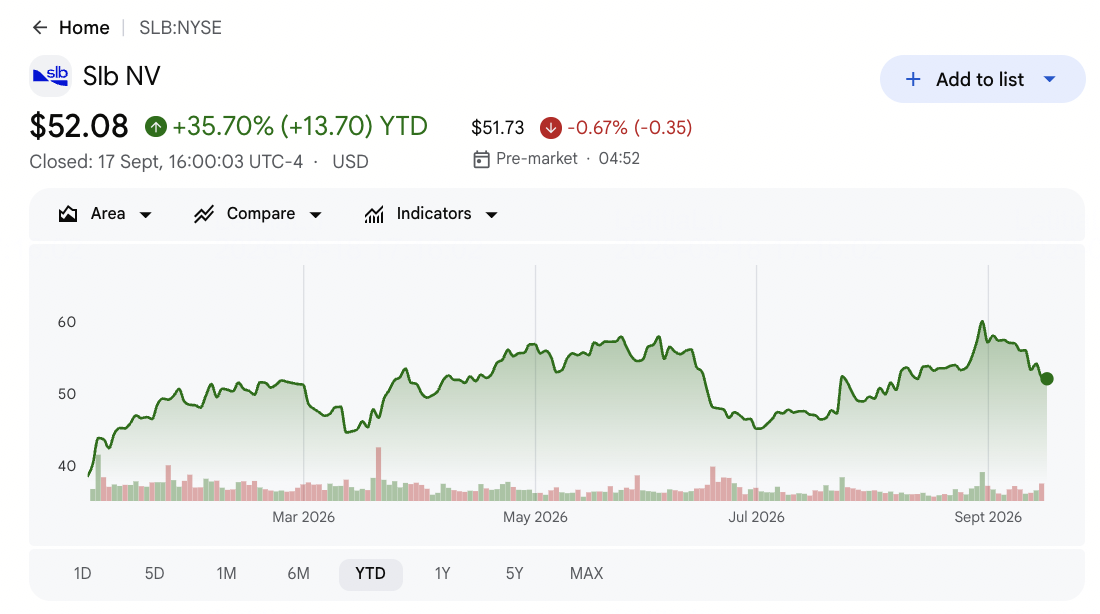
- SLB closed at $52.08 on September 17 and was up 35.70% YTD: Shares remained about 10% below the $60.46 52-week high. The rally reflects stronger energy sentiment and diversification hopes, though the $61 to $72 analyst target range leaves less upside after the YTD move.
- Q2 revenue reached $8.972 billion and beat consensus by about $302 million: Revenue rose 3% sequentially and 5% year over year. ChampionX contributed $870 million, while organic revenue declined 5%, showing that acquisition growth still masks softer underlying activity.
- Adjusted EPS of $0.55 beat consensus by $0.04: Adjusted EBITDA reached $1.899 billion and margin improved 83 basis points sequentially to 21.2%. EPS still fell 26% year over year, showing that profitability has not fully recovered.
- Digital revenue rose 18% to $697 million: International Digital sales increased 14%, while North American Data Center Solutions revenue rose 80%. These businesses add less commodity-sensitive growth, though they remain much smaller than SLB's core oilfield operations.
- The $4.1 billion Kelvion deal targets $4.5 billion to $5.0 billion of 2028 data-center revenue: The transaction includes $3.4 billion of cash and about $700 million of assumed debt. SLB expects $700 million to $800 million of combined adjusted EBITDA by 2028, making integration and returns the key tests.
What Is SLB (SLB)?
SLB is one of the world's largest energy-services and technology companies. It supplies tools, equipment, software and expertise used to characterize reservoirs, construct wells, complete and stimulate production, manage subsea developments and optimize producing assets. Customers include national oil companies, international producers and independents across more than 100 countries. Revenue depends on customer capital spending, offshore project awards, equipment deliveries and operational access in major producing regions.
SLB's long-term direction combines core oilfield leadership with digital, production and infrastructure businesses. ChampionX adds production chemicals and artificial lift, SLB OneSubsea expands subsea exposure, and the Delfi platform and NVIDIA relationship support industrial AI workflows. The planned Kelvion purchase adds cooling and heat-transfer equipment to Data Center Solutions and more than doubles SLB's revenue opportunity per gigawatt of delivered capacity. The strategy can diversify cash flow, though it adds integration and capital-allocation risk.
Read More: Oil Stocks vs. Natural Gas Stocks vs. Energy ETFs in 2026: Which Is the Better Investment?
SLB (SLB) Q2 2026 Earnings Overview: Revenue, EPS and International Recovery
SLB delivered Q2 revenue of $8.972 billion versus $8.67 billion expected, adjusted EPS of $0.55 versus $0.51 expected, adjusted EBITDA of $1.899 billion and operating cash flow of $1.36 billion. Digital revenue grew 18% to $697 million, North America revenue rose 36% to $2.244 billion and management guided to 3%–4% sequential Q3 revenue growth. The quarter improved sequentially, though organic revenue and year-over-year earnings remained under pressure.
Read More: SLB (SLB) Q2 FY2026 Earnings Overview: $8.97B Revenue Beat Drives a 11.01% Price Rally
|
Financial Metric |
Guidance / Consensus |
Reported / Actual |
Surprise |
|
Q2 2026 revenue |
$8.67B consensus |
$8.972B |
Beat. About $302M above consensus and up 5% YoY. |
|
Q2 adjusted diluted EPS |
$0.51 consensus |
$0.55 |
Beat. $0.04 above consensus, though down 26% YoY. |
|
Q2 GAAP diluted EPS |
$0.74 one year earlier |
$0.52 |
Declined. Down 30% YoY and up 4% sequentially. |
|
Q2 adjusted EBITDA |
$2.051B one year earlier |
$1.899B |
Mixed. Down 7% YoY and up 7% sequentially. |
|
Q2 adjusted EBITDA margin |
20.3% in Q1 2026 |
21.20% |
Expanded. Increased 83 bps sequentially. |
|
Q2 operating cash flow |
— |
$1.36B |
Positive. Supported $716M of free cash flow. |
|
Q2 Digital revenue |
$591M one year earlier |
$697M |
Grew. Increased 18% YoY and 9% sequentially. |
|
Q2 North America revenue |
$1.655B one year earlier |
$2.244B |
Grew. Increased 36% YoY with ChampionX support. |
|
Q3 2026 revenue outlook |
Q2 actual of $8.972B |
Up 3%–4% sequentially |
Guided. Implies roughly $9.24B–$9.33B. |
- Revenue of $8.972 billion beat consensus by roughly $302 million: North America increased 4% sequentially, Latin America rose 12% and Europe and Africa advanced 6%. Those gains more than offset a 4% decline in Middle East and Asia revenue.
- Adjusted EPS of $0.55 exceeded consensus by $0.04: The figure rose 6% sequentially yet declined 26% year over year. The comparison shows improving near-term execution without a complete recovery in earnings power, cash conversion or the prior-year margin structure.
- Adjusted EBITDA margin expanded 83 basis points to 21.2%: Adjusted EBITDA increased 7% sequentially to $1.899 billion. Margin remained 284 basis points below the prior year, leaving more recovery needed before the stock can rely on operating leverage.
- Operating cash flow reached $1.36 billion and free cash flow reached $716 million: Cash generation improved as activity and collections strengthened. Higher second-half free cash flow is important because dividends, repurchases and the Kelvion transaction all compete for capital.
- Q3 revenue guidance calls for 3%–4% sequential growth: The range implies roughly $9.24 billion–$9.33 billion, with about 75 basis points of additional adjusted EBITDA margin expansion discussed on the call. Delivery would support recovery despite unresolved Middle East disruption.
SLB (SLB) 2026 Investment Outlook: $75 Bull Case vs. $45 Bear Case
SLB's 2026 outlook depends on whether stronger international activity, ChampionX integration and faster Digital and data-center growth can offset regional disruption and weaker organic revenue. The Kelvion deal adds another growth path, though integration and cash returns remain key tests.
The Bull Case: Strong International Growth Pushes SLB Toward $75
The Bull Case assumes Latin America, Europe, Africa and offshore activity continue offsetting Middle East disruption. ChampionX synergies improve Production Systems economics, Digital keeps growing at a double-digit rate and Kelvion gives Data Center Solutions a credible path toward $4.5 billion to $5.0 billion of revenue by 2028.
A move toward $75 would require Q3 revenue near $9.33 billion, about 75 basis points of sequential EBITDA-margin expansion and stronger second-half free cash flow. Evidence that Kelvion can reach $700 million to $800 million of 2028 adjusted EBITDA without weakening shareholder returns would strengthen the case.
The Base Case: Steady International Growth Keeps SLB Between $58 and $68
The Base Case assumes core international activity remains resilient and ChampionX supports North American growth, while Middle East recovery stays uneven. Digital and data-center revenue expand, though integration costs and Kelvion investment keep cash flow from rising as quickly as revenue.
Under this scenario, SLB could trade mainly between $58 and $68. Sequential revenue growth of 3% to 4%, improving EBITDA margin and free cash flow above $1 billion in a stronger quarter would support the range. Organic revenue declines or slower integration progress would cap the upper end.
The Bear Case: Weaker Energy Spending Pulls SLB Toward $45
The Bear Case assumes Middle East disruption continues while lower commodity prices reduce producer spending elsewhere. ChampionX and Kelvion add debt, integration costs and execution demands before expected synergies fully reach earnings.
A move toward $45 would become more likely if Q3 revenue misses guidance, EBITDA margin falls below 20% or free cash flow weakens despite higher reported sales. Lower customer spending and a weaker valuation multiple would add further pressure.
SLB Stock Price Forecasts for 2026 By Wall Street Analysts
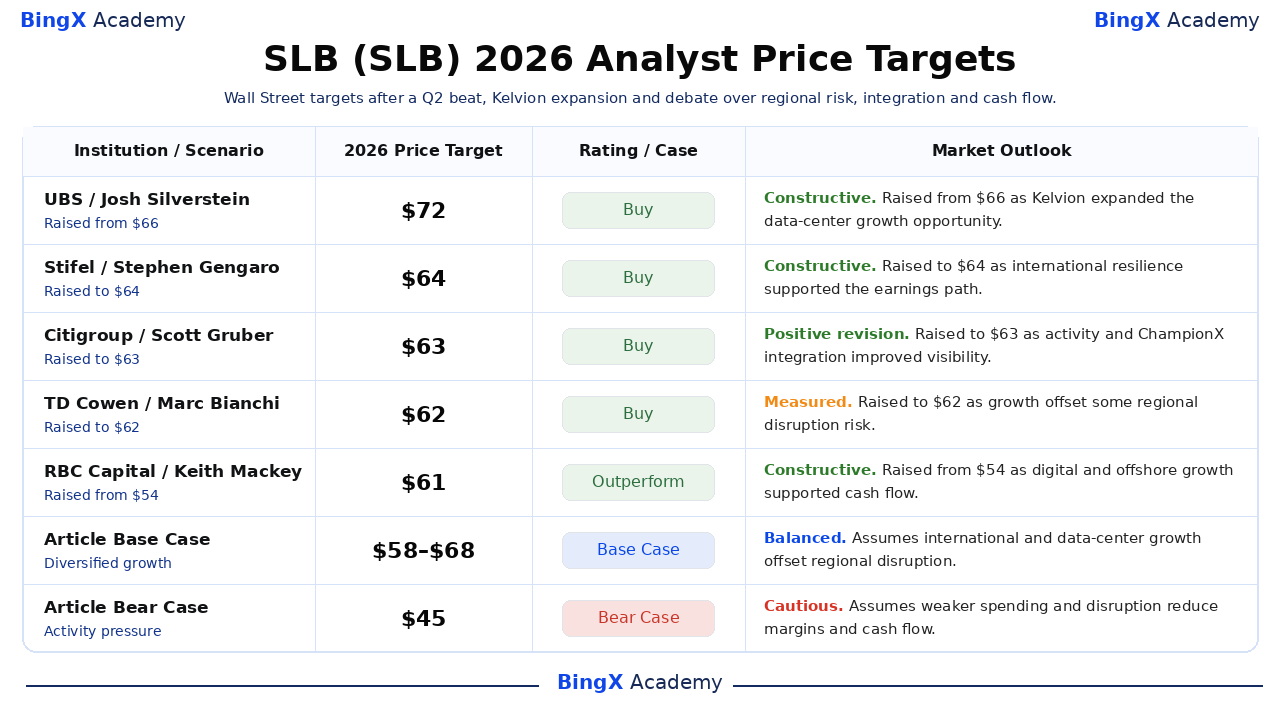
Wall Street remains constructive on SLB's international, digital and production portfolio, and Kelvion has raised the ceiling for data-center exposure. These dated targets are third-party reference points rather than price promises. The Base and Bear rows are BingX Academy editorial scenarios.
|
Institution / Scenario |
2026 Price Target |
Rating / Case |
Market Outlook |
|
UBS / Josh Silverstein |
$72 |
Buy |
Constructive. September 1: raised from $66 as Kelvion expanded the data-center growth opportunity. |
|
Stifel / Stephen Gengaro |
$64 |
Buy |
Constructive. June 18: raised to $64 as international resilience supported the earnings path. |
|
Citigroup / Scott Gruber |
$63 |
Buy |
Positive revision. July 1: raised to $63 as activity and ChampionX integration improved visibility. |
|
TD Cowen / Marc Bianchi |
$62 |
Buy |
Measured. July 1: raised to $62 as growth offset some regional disruption risk. |
|
RBC Capital / Keith Mackey |
$61 |
Outperform |
Constructive. June 16: raised from $54 as digital and offshore growth supported cash flow. |
|
Article Base Case |
$58–$68 |
Base Case |
Balanced. Assumes international and data-center growth offset regional disruption. |
|
Article Bear Case |
$45 |
Bear Case |
Cautious. Assumes weaker spending and disruption reduce margins and cash flow. |
How to Trade SLB (SLB) Stock on BingX
Trade SLB's international-activity, ChampionX and data-center outlook using BingX TradFi and BingX AI tools. Because SLB can react sharply to oil prices, regional conflict, earnings and acquisitions, traders should define both the catalyst and risk limits before entering a position.
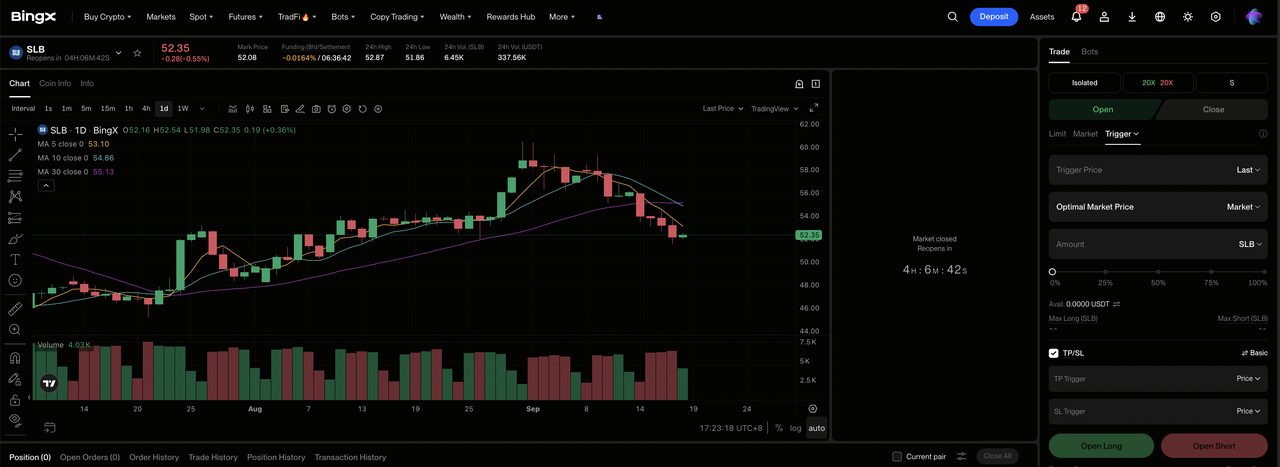
Step 1: Access BingX TradFi. Sign up and navigate to the specialized TradFi section on the BingX exchange dashboard.
Step 2: Select SLB (SLB). Search for and select the SLB-USDT perpetual futures contract.
Step 3: Choose your direction. Select Open Long if international growth and margin recovery support the Bull Case. Select Open Short if disruption or weaker spending reduces expected cash flow.
Step 4: Select leverage and margin mode. Choose Isolated or Cross-Margin based on your risk tolerance. The 41.22% YTD gain shows why conservative leverage and clear position sizing are important.
Step 5: Execute strict risk protocols. Set Take-Profit and Stop-Loss (TP/SL) levels before or immediately after entering the trade. SLB can react quickly to commodity prices, field access, guidance and acquisition developments.
Top 5 Risks to Watch for SLB Investors in 2026
SLB's value depends on customer activity, regional execution, margins and capital allocation. These risks can affect free cash flow and the valuation assigned to the stock.
- Middle East disruption could reduce high-value activity: Middle East and Asia revenue fell 14% year over year to $2.572 billion. Continued limits on mobilization or customer operations could pressure revenue before costs adjust.
- Acquisition growth can hide weaker organic demand: Reported revenue rose 5%, while revenue excluding ChampionX declined 5%. If underlying activity stays soft, more of the earnings case will depend on acquisition synergies.
- Kelvion adds significant capital-allocation risk: SLB will pay $3.4 billion in cash and assume about $700 million of debt. Integration delays or weaker data-center demand could reduce returns and limit buybacks.
- Customer spending still depends on commodity prices: Lower oil prices or weaker project economics can delay drilling and production awards. Lower utilization would pressure margins and cash flow even if Digital continues growing.
- A broader portfolio increases execution complexity: ChampionX, OneSubsea, Digital and Data Center Solutions serve different customers and require different operating capabilities. Weak cross-selling or cost overruns could reduce the margin benefits expected from diversification.
Final Thoughts: Should You Invest in SLB in 2026?
SLB enters late 2026 with improving sequential momentum. Revenue beat consensus by about $302 million, adjusted EBITDA margin expanded 83 basis points and Q3 guidance points to another step higher. ChampionX, Digital and Kelvion also create growth paths beyond conventional drilling activity, though organic revenue declined 5% and year-over-year adjusted EPS remained 26% lower.
The Bull Case supports $75 if international recovery, margin expansion and data-center integration strengthen free cash flow. The Bear Case points to $45 if regional disruption, weaker budgets or acquisition execution pressure estimates. Conservative traders may wait for Q3 revenue, EBITDA margin, free cash flow and Kelvion financing details before increasing exposure.
Risk Reminder: Trading and investing in equities like SLB involves a high risk of capital loss. Commodity prices, geopolitical events, earnings misses, acquisition risk, valuation shifts and leveraged trading can produce rapid losses. Conduct independent research before allocating capital.
Related Reading
- Oil Stocks vs. Natural Gas Stocks vs. Energy ETFs in 2026: Which Is the Better Investment?
- Top AI Data Center Stocks to Buy in 2026: Cloud, Servers, and AI Compute Infrastructure
- Top AI Energy Stocks to Buy in 2026: Nuclear, Gas, Fuel Cells, and the AI Power Buildout
- Top Energy Stocks and ETFs to Buy in 2026: The AI Power Crunch Meets Geopolitical Volatility
- Bloom Energy (BE) Price Prediction 2026: Can AI Data-Center Power Push BE Toward $350?
- NVIDIA (NVDA) Price Prediction 2026: Can AI Infrastructure Growth Drive NVDA Toward $420?
