


NuScale Power (SMR) develops small modular reactor technology for utilities, industrial customers and data-center power projects. Its 77-megawatt NuScale Power Module is the building block for VOYGR plants, while licensing, engineering and project-development services are intended to create revenue before module production begins. U.S. regulatory approval gives the company a differentiated position, though the stock remains sensitive to project financing, construction timing and cash consumption.
The latest quarter showed how far commercial scale remains from current financial results. NuScale Power Q2 2026 revenue fell to $75,000 from $8.054 million a year earlier, net loss widened to $47.539 million and six-month operating cash use reached $372.860 million. Cash of $766.460 million provides a development runway, yet the investment case depends on converting ENTRA1, TVA and Romanian project work into funded plants and recurring revenue.
The SMR stock forecast for 2026 now centers on two competing views:
- The funded-project and customer-commitment case: a firm customer commitment, complete financing and a module order could turn regulatory approval into visible commercial backlog and project revenue.
- The deployment-delay and dilution case: extended development schedules and continued cash use could require more capital before NuScale records meaningful plant revenue.
This guide breaks down the SMR stock forecast, 2026 price scenarios, key risks and analyst outlooks, drawing on NuScale Power's August 5, 2026 Q2 2026 earnings release, quarterly filing and market data through September 18, plus how to trade SMR stock futures on BingX TradFi with USDT collateral.
Top 5 Things for NuScale Power Investors to Know in September 2026
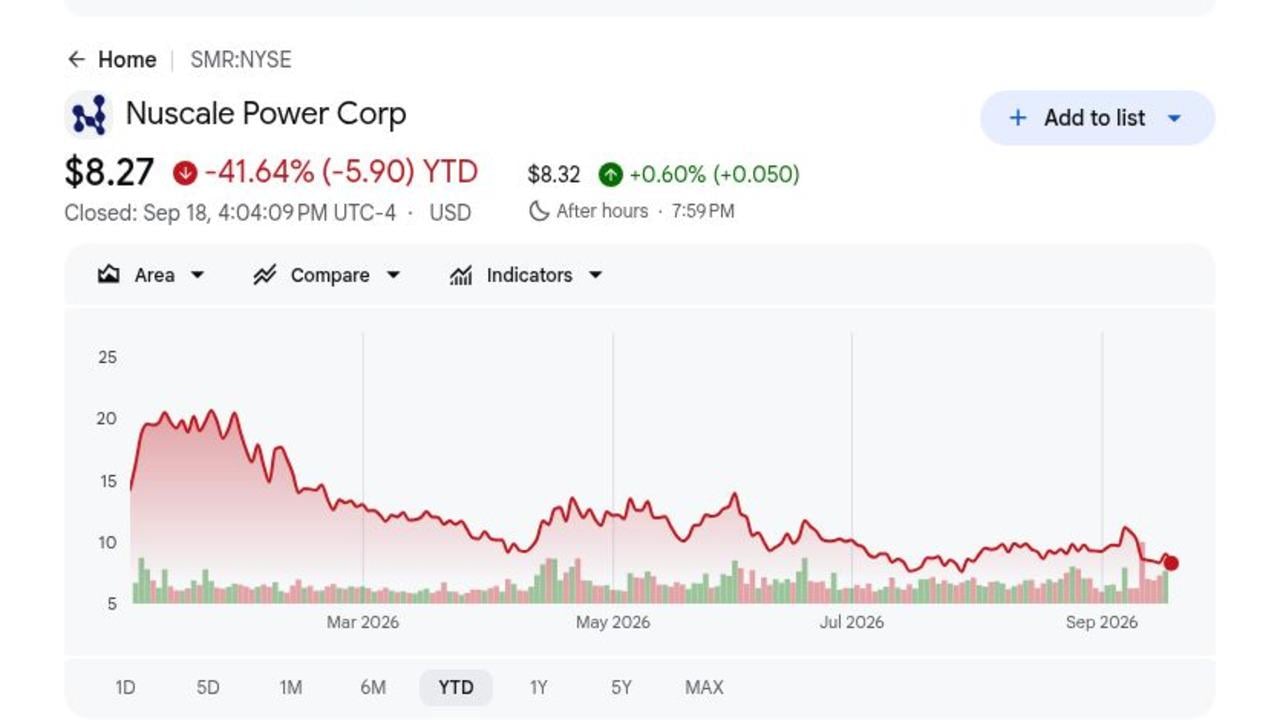
- SMR closed at $8.27 and was down 41.64% in 2026: The September 18 close sat below nearly all positive analyst targets, with UBS's $6 target representing the main bearish outlier. The decline shows that investors are shifting from valuing regulatory progress to demanding funded projects and commercial revenue.
- Q2 revenue fell to just $75,000 from $8.054 million: Project-service revenue declined by $7.979 million year over year as milestone timing remained uneven. NuScale still lacks a recurring commercial revenue base despite years of engineering and licensing work.
- Cash of $766.460 million provides a substantial runway: The balance declined from $836.417 million at year-end, while first-half operating cash use reached $372.860 million. Liquidity gives NuScale more time to commercialize its technology, though the burn rate increases the cost of further delays.
- Net loss widened by $29.898 million to $47.539 million: R&D rose to $18.429 million and G&A reached $26.875 million. The wider loss shows that design, licensing and corporate costs remain high well before module deployments can absorb fixed expenses.
- Analyst targets from $6 to $16 reflect major project-conversion uncertainty: Northland retained a $16 target while UBS cut to $6, leaving a wide $10 spread around the $8.27 share price. The range reflects different expectations for whether ENTRA1, TVA and Romania can move into financeable commercial projects.
What Is NuScale Power (SMR)?
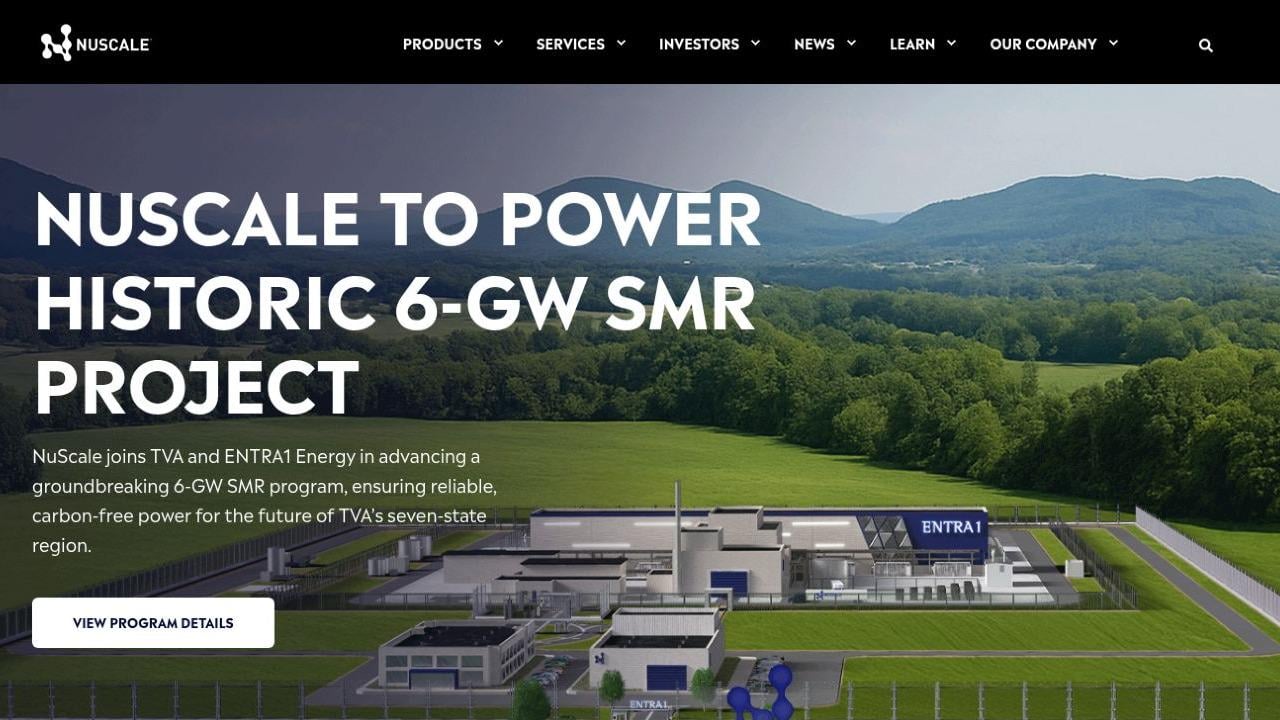
NuScale Power is a nuclear technology developer whose core product is the NuScale Power Module, a 77-megawatt pressurized-water reactor designed to use passive safety systems and factory-oriented manufacturing. Multiple modules can be combined into VOYGR plants sized for utility grids, industrial sites or large data centers. The company expects to earn from technology licensing, engineering services, module-related intellectual property and long-term plant support. It does not currently operate a commercial reactor, so revenue depends on development milestones rather than electricity sales.
The long-term strategy centers on moving approved designs into funded customer projects. ENTRA1 Energy is NuScale’s commercialization partner, TVA is evaluating deployment pathways in the United States and Doosan Enerbility has manufacturing capabilities for major reactor components. In Romania, RoPower Nuclear and Nuclearelectrica have advanced work around a prospective six-module plant at Doicești. These relationships create a route to deployment, though final investment decisions, financing, site licensing and construction contracts remain more important than quarterly engineering revenue.
Read More: Top AI Energy Stocks to Buy in 2026: Nuclear, Gas, Fuel Cells, and the AI Power Buildout
NuScale Power (SMR) Q2 2026 Earnings Overview: Minimal Revenue, Higher Spending and a $766.5M Cash Balance
NuScale reported Q2 revenue of $75,000 versus $8.054 million a year earlier, a $47.539 million net loss versus $17.641 million, and a $0.13 loss per share that matched the prior-year loss per share because the share count increased. R&D expense rose to $18.429 million and G&A reached $26.875 million. Cash remained $766.460 million, though six-month operating cash use expanded to $372.860 million, making project conversion and capital discipline the main tension.
Read More: NuScale Power (SMR) Q2 FY2026 Earnings Overview: $75K Revenue Collapse Drives a 0.96% Price Rally
|
Financial Metric |
Guidance / Consensus |
Reported / Actual |
Surprise |
|
Q2 2026 revenue |
$8.054M in Q2 2025 |
$0.075M |
Contracted. Contracted. Revenue fell $7.979M YoY. |
|
Q2 GAAP loss per share |
$0.13 loss in Q2 2025 |
$0.13 loss |
Flat. Flat per share despite a wider net loss. |
|
Q2 net loss |
$17.641M loss in Q2 2025 |
$47.539M loss |
Widened. Widened by $29.898M YoY. |
|
Q2 research and development |
$11.802M in Q2 2025 |
$18.429M |
Increased. Increased by $6.627M YoY. |
|
Q2 general and administrative expense |
$22.523M in Q2 2025 |
$26.875M |
Increased. Increased by $4.352M YoY. |
|
Cash and cash equivalents |
$836.417M at Dec. 31, 2025 |
$766.460M |
Lower. Lower but still substantial. |
|
Six-month operating cash flow |
$56.107M used in H1 2025 |
$372.860M used |
Cash. Cash use increased by $316.753M YoY. |
- Revenue of $75,000 fell by $7.979 million year over year: The decline mainly reflected milestone timing, but it also shows how little operating revenue currently supports NuScale's cost base. Funded engineering phases need to begin before quarterly sales become meaningful evidence of commercialization.
- Loss per share stayed at $0.13 despite a wider net loss: Net loss increased to $47.539 million from $17.641 million. A larger share count kept the per-share loss flat, showing how dilution can mask worsening absolute losses while reducing each shareholder's claim on future value.
- R&D rose 56% to $18.429 million: Spending increased from $11.802 million as NuScale continued design, licensing and commercialization work. The investment supports its regulatory position, but only creates shareholder value if customers move into funded deployment.
- G&A increased by $4.352 million to $26.875 million: Corporate costs rose from $22.523 million while revenue remained negligible. NuScale needs stronger milestone revenue and tighter overhead growth to show that expenses can scale more slowly than contracts.
- Cash of $766.460 million must support a $372.860 million first-half operating outflow: Cash remains substantial, but operating use was $316.753 million higher than in the first half of 2025. The runway therefore depends on project receipts, development spending and the need for any future capital raise.
NuScale Power (SMR) 2026 Investment Outlook: $20 Bull Case vs. $6 Bear Case
NuScale's 2026 outlook depends on whether development agreements can turn into funded commercial projects. The upside comes from a binding customer commitment and project financing, while delays, cash burn and dilution remain the main risks.
The Bull Case: A Funded SMR Project Pushes SMR Toward $20
The Bull Case assumes ENTRA1 and a utility or data-center customer agree on a firm project plan, arrange the money needed to build it and place an initial order for NuScale modules. Approval from the NRC for the 77 MWe design, continued support from Doosan on manufacturing and progress on the Romania project would make the business look more credible and give investors a clearer idea of when commercial revenue could begin.
A move toward $20 would require a contract with clear capacity, schedule and economics, along with cash use well below the $372.860 million first-half pace. Rising engineering revenue and evidence that customer capital, rather than NuScale equity, funds plant construction would strengthen the case.
The Base Case: Development Progress Keeps SMR Between $10 and $14
The Base Case assumes project studies, licensing and supply-chain work continue advancing without a final plant order in 2026. The $766.460 million cash balance supports further development, though $75,000 of quarterly revenue limits how much value investors can assign to prospective projects.
SMR could trade mainly between $10 and $14 under these conditions. Stable cash, visible engineering milestones and at least one financed next-stage agreement would support the range. Another year of minimal revenue and operating cash use near the first-half pace would weaken the upper end.
The Bear Case: Project Delays and Cash Burn Pull SMR Toward $6
The Bear Case assumes customer financing, site licensing or supply-chain commitments take longer than expected. NuScale continues funding engineering and corporate costs while prospective projects fail to generate meaningful receipts or firm module orders.
A move toward $6 would become more likely if cash declines rapidly from $766.460 million, another capital raise expands the share count or partners delay investment decisions. Faster progress from competing advanced-reactor projects could add further pressure to the valuation.
SMR Stock Price Forecasts for 2026 By Wall Street Analysts
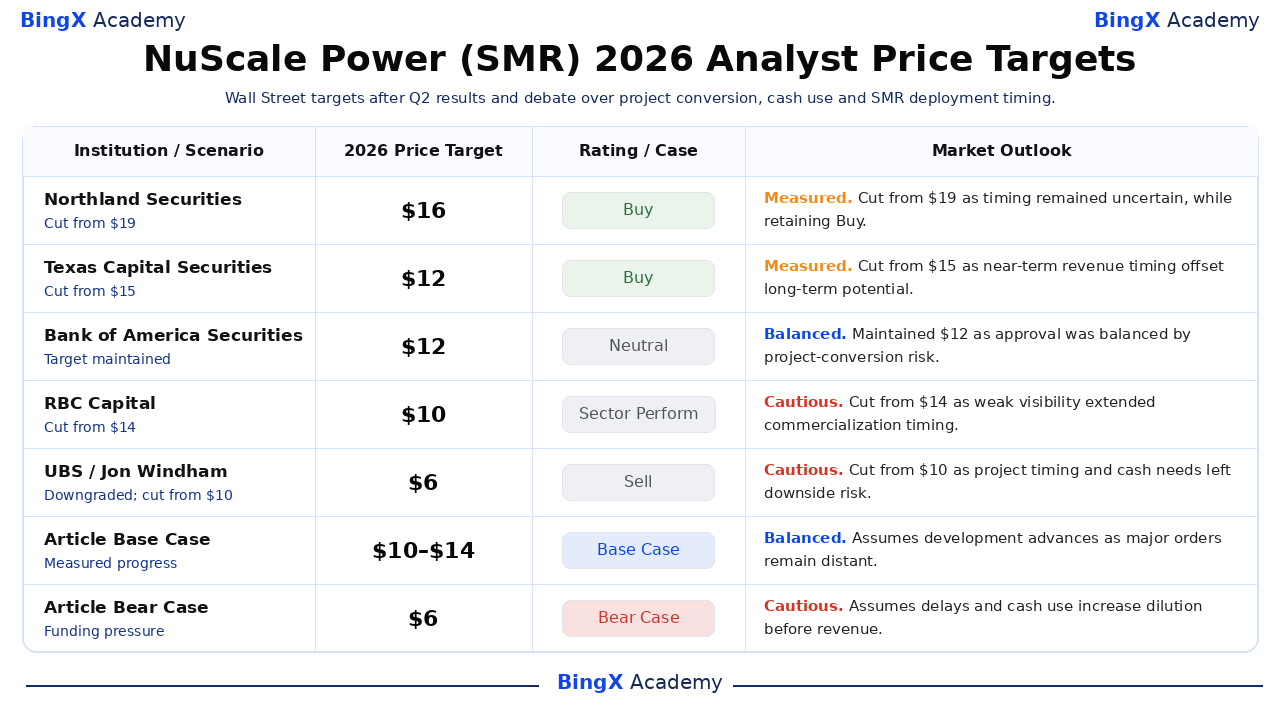
The five dated actions show how analysts weigh current execution against the long-term opportunity. They are third-party reference points rather than a single consensus forecast. The final Base and Bear rows are BingX Academy editorial scenarios and are labeled separately.
|
Institution / Scenario |
2026 Price Target |
Rating / Case |
Market Outlook |
|
Northland Securities / Jeff Grampp |
$16 |
Buy |
Measured. August 6: cut from $19 to $16; Commercialization remained attractive despite weaker near-term visibility. |
|
Texas Capital Securities / Nathaniel Pendleton |
$12 |
Buy |
Measured. August 20: cut from $15 to $12; Slower near-term revenue offset the long-term SMR opportunity. |
|
Bank of America Securities / Rinny Singh |
$12 |
Neutral |
Balanced. August 12: maintained a $12 target; Regulatory advantages were balanced by project-conversion risk. |
|
RBC Capital / Chris Dendrinos |
$10 |
Sector Perform |
Cautious. August 11: cut from $14 to $10; Weak near-term visibility extended commercialization timing. |
|
UBS / Jon Windham |
$6 |
Sell |
Cautious. September 11: cut from $10 to $6; Project timing and cash needs left downside risk. |
|
Article Base Case |
$10–$14 |
Base Case |
Balanced. Assumes development advances as major orders remain distant. |
|
Article Bear Case |
$6 |
Bear Case |
Cautious. Assumes delays and cash use increase dilution before revenue. |
How to Trade NuScale Power (SMR) Stock on BingX
Trade NuScale Power’s project-conversion, regulatory and funding outlook using BingX TradFi and BingX AI tools. Because SMR reacts sharply to project announcements, financing and analyst revisions, traders should define the catalyst and risk limits before entering a position.
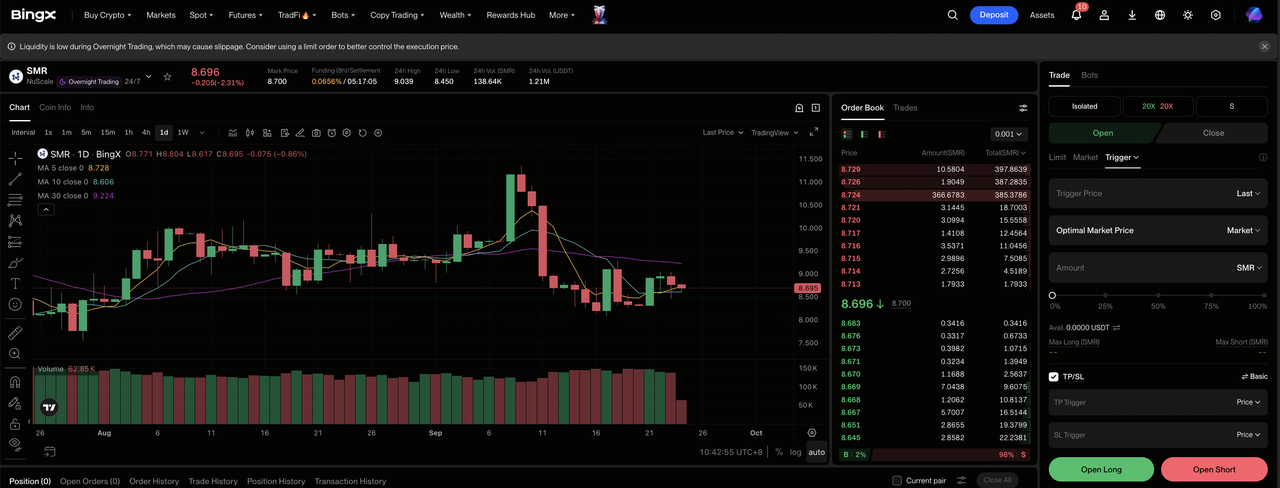
Step 1: Access BingX TradFi. Sign up and navigate to the specialized TradFi section on the BingX exchange dashboard.
Step 2: Select NuScale Power (SMR). Search for and select the SMR-USDT perpetual futures contract.
Step 3: Choose your direction. Select Open Long if funded projects and engineering revenue improve. Select Open Short if delays and cash use increase dilution risk.
Step 4: Select leverage and margin mode. Choose Isolated or Cross-Margin based on your risk tolerance. The 41.64% YTD decline shows why conservative leverage and clear position sizing are important.
Step 5: Execute strict risk protocols. Set Take-Profit and Stop-Loss (TP/SL) levels before or immediately after entering the trade. SMR can react quickly to customer contracts, NRC milestones, financing, cash use and project delays.
Top 5 Risks to Watch for NuScale Power Investors in 2026
NuScale's valuation depends on turning development work into funded commercial projects. Financing delays, high cash use, construction costs and competition could all reduce future value per share.
- Project financing can delay revenue for years: Nuclear projects require customer equity, debt, government support and regulatory approvals. If financing takes longer, engineering revenue and module orders could be pushed further out.
- First-half operating cash use of $372.860 million raises dilution risk: NuScale had $766.460 million of cash, but the outflow shows how quickly that balance can decline. Additional equity or convertible financing could increase the share count before revenue scales.
- First-of-a-kind costs can weaken project economics: Engineering changes, supply-chain inflation and construction delays could raise plant costs. That may make utilities less willing to commit and reduce future licensing economics.
- International projects depend on multiple approvals: The Romania project still requires financing, site work and regulatory progress. Delays could increase development costs and push potential revenue further out.
- Competing power technologies can capture customer spending: Utilities and data-center developers can choose large reactors, gas generation or other advanced reactor designs. Faster-moving competitors could reduce NuScale's potential customer pipeline.
Final Thoughts: Should You Invest in NuScale Power in 2026?
NuScale owns an NRC-approved 77 MWe module design and works with ENTRA1, TVA, Doosan and Romanian partners, giving it a credible route to deployment. Q2 revenue of $75,000 and first-half operating cash use of $372.860 million show that regulatory achievement has not yet become a durable business with predictable revenue or positive operating cash flow.
The Bull Case requires a financed customer project to support $20. The Bear Case reflects delays and dilution that could pull SMR toward $6. Conservative traders may watch cash use, binding contracts, customer financing and licensing milestones before treating development announcements as evidence of commercial scale or assigning full value to a prospective module pipeline.
Risk Reminder: Trading and investing in equities like SMR involves a risk of capital loss. Company execution, competition, financing, valuation changes and leveraged trading can produce rapid losses. Conduct independent research before allocating capital.
Related Reading
- Top AI Energy Stocks to Buy in 2026: Nuclear, Gas, Fuel Cells, and the AI Power Buildout
- Top Energy Stocks and ETFs to Buy in 2026: The AI Power Crunch Meets Geopolitical Volatility
- Oklo (OKLO) Stock Price Prediction 2026: Can Nuclear Expansion Push OKLO Toward $250?
- Bloom Energy (BE) Price Prediction 2026: Can AI Data-Center Power Push BE Toward $350?
- Cheniere Energy (LNG) Price Prediction 2026: Can Higher Gas Exports Push LNG Toward $340?
