
ASML Holding (ASML) supplies the lithography systems that let chipmakers print increasingly intricate circuits. Extreme ultraviolet tools support advanced logic and memory production, while installed-base upgrades and services improve productivity after delivery. AI-related fabrication investment is expanding demand, but complex equipment builds, customer acceptance and export licensing determine how much of that demand becomes profitable near-term sales.
The latest quarter showed stronger system output and installed-base economics. ASML Q3 net sales reached €11.662B (13.06B),installed-basesaleswere€3.289B(3.68B), and gross margin rose to 57.5%. Management also said planned 2027 and 2028 supply would not fully meet customer forecasts. The remaining question is whether ASML can expand deliveries without weakening margins or pushing too much demand into later years.
The ASML stock forecast for 2026 now centers on two competing views:
- The EUV capacity case: Strong advanced-chip demand, Q4 delivery growth and higher tool productivity can support rising sales and margins as the company expands supply.
- The execution and valuation case: Capacity gaps, export controls or a weaker AI investment cycle could leave results below expectations after a sharp share-price advance.
This guide breaks down the ASML stock forecast, 2026 price scenarios, key risks and analyst outlooks, drawing on ASML's October 14 Q3 release and market data through October 19, plus how to trade ASML stock futures on BingX TradFi with USDT collateral.
Top 5 Things for ASML Holding Investors to Know in October 2026
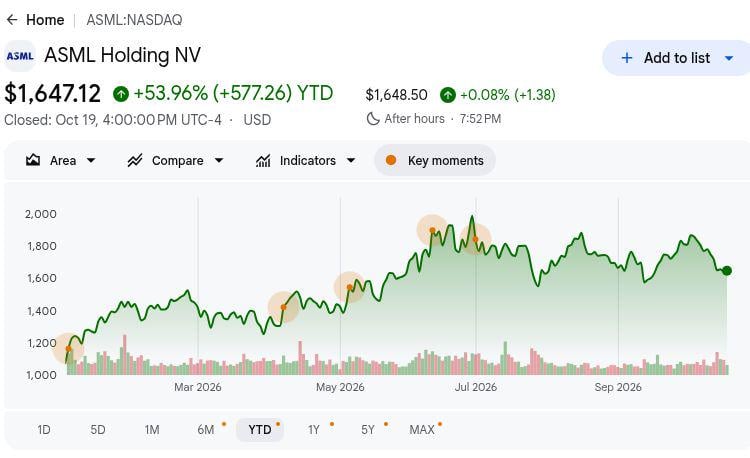
- ASML closed at $1,647.12 on October 19, up 53.96% year to date: The Google Finance reference price still stood below the $1,999.96 52-week high. After a sharp rally, a return to that high requires delivered tools, not long-dated customer interest.
- Q3 sales grew 55% to €11.662B ($13.06B): The result was 25% above the preceding quarter's €9.326B (10.44B),althoughitwasroughly€0.19B(0.21B) below the €11.85B ($13.27B) LSEG estimate. Growth and a modest miss must both be tested against shipments.
- Installed-base revenue reached €3.289B ($3.68B): Service and field-option sales climbed from €2.762B ($3.09B) in Q2, helped by productivity upgrades. Existing machines generated upgrade revenue that helped lift gross margin to 57.5%, cushioning shipment timing.
- Q4 guidance calls for €14.2B–€15.2B (15.90B–17.02B) in sales: Its €14.7B (16.46B)midpointisabout26%aboveQ3.ASMLalsoliftedthelowendofitsfull-yearoutlookto€44B(49.26B). That delivery schedule, not yet recognized revenue, tests the bull case.
- The TSMC photomask initiative targets more than 40% productivity improvement: In its October presentation, ASML described a joint High-NA EUV move toward 12-inch masks for dual-mask exposure and separately reported shipment of the YieldStar 550 metrology system. The mask initiative still needs customer implementation before it becomes revenue.
What Is ASML Holding (ASML)?
ASML Holding is a Dutch semiconductor equipment company that develops lithography systems used to manufacture advanced chips. Its extreme ultraviolet (EUV) machines are essential for producing leading-edge processors, while deep ultraviolet (DUV) systems support a broader range of semiconductor manufacturing processes. ASML also supplies metrology equipment, computational lithography software, and services that improve chipmaking precision and productivity. Its business is closely tied to AI hardware, advanced semiconductor production, and global chip investment cycles.
ASML supplies major semiconductor manufacturers, including TSMC, Samsung Electronics, Intel, SK hynix, and Micron. Its technology roadmap focuses on High-NA EUV, advanced metrology, and greater manufacturing capacity. In October 2026, ASML outlined a TSMC initiative targeting over 40% productivity improvement in dual-mask exposure using 12-inch photomasks. It has also shipped the YieldStar 550 metrology system and is evaluating capacity beyond its planned 30% expansion by 2028 to meet rising customer demand.
ASML Holding (ASML) Q3 2026 Earnings Overview: Strong Margins and Higher Guidance Offset Revenue Miss
ASML reported Q3 2026 net sales of €11.662B (13.06B),up55%yearoveryearbutbelowthe€11.85B(13.27B) consensus estimate. Gross margin improved to 57.5%, supported by €3.289B (3.68B)ininstalled-basesales,whilebasicEPSreached€12.95(14.50). Management raised its full-year revenue outlook to €44B to €45B ($49.26B to $50.38B), with stronger Q4 shipments and customer acceptance now central to the growth outlook.
|
Financial Metric |
Guidance / Consensus |
Reported / Actual |
Surprise |
|
Q3 total net sales |
LSEG €11.85B ($13.27B) |
€11.662B ($13.06B) |
Miss. €0.19B ($0.21B) below consensus; up 55% YoY. |
|
Q3 net income |
Q2 €2.918B ($3.27B) |
€4.960B ($5.55B) |
Higher. Up 70% sequentially. |
|
Q3 basic EPS |
Q2 €7.59 ($8.50) |
€12.95 ($14.50) |
Higher. Up €5.36 ($6.00). |
|
Q3 installed-base sales |
Q2 €2.762B ($3.09B) |
€3.289B ($3.68B) |
Growth. Up 19% sequentially. |
|
Q3 gross margin |
Q2 54.0% |
57.50% |
Higher. Up 3.5 percentage points. |
|
Q3 new systems sold |
Q2 86 |
113 |
Growth. 27 more systems. |
|
Q4 sales outlook |
Q3 €11.662B ($13.06B) |
€14.2B–€15.2B (15.90B–17.02B) |
Higher. Midpoint up 26% sequentially. |
|
FY2026 sales outlook |
Prior €43B–€45B (48.14B–50.38B) |
€44B–€45B (49.26B–50.38B) |
Raised. Low end up €1B ($1.12B). |
- Q3 sales rose 55% year over year, yet missed one estimate: The €11.662B (13.06B)resultcompareswith€7.516B(8.41B) a year earlier and €11.85B ($13.27B) in the LSEG forecast. A shipment shift can move quarterly estimates without ending demand.
- New-system volume increased to 113 from 86: ASML sold 27 more new lithography systems than in Q2, and system sales advanced to roughly €8.4B (9.40B)from€6.6B(7.39B). Higher throughput makes Q4 customer acceptance more consequential.
- Installed-base sales climbed 19% sequentially: The €3.289B (3.68B)resultfollowed€2.762B(3.09B) in Q2, with management citing demand for productivity upgrades above its plan. Those upgrades can raise output from existing customer tools before a new fab receives additional machines; they also helped carry the quarterly gross margin above the prior 54.0% level.
- Gross margin expanded by 3.5 percentage points: Q3 reached 57.5% versus 54.0% in Q2, while net income increased to €4.960B (5.55B)from€2.918B(3.27B). Basic EPS reached €12.95 ($14.50). That margin supports valuation if upgrade mix and system economics persist at scale.
- 2026 guidance rose while planned 2028 supply still trails forecasts: Full-year sales are now expected at €44B–€45B (49.26B–50.38B), versus a prior €43B–€45B (48.14B–50.38B) range. ASML is investigating 2028 output beyond a previously communicated 30% expansion. Customer interest in 2029–30 orders is not booked revenue.
ASML Holding (ASML) 2026 Investment Outlook: $2,500 Bull Case vs. $1,250 Bear Case
ASML's 2026 outlook depends on converting strong EUV demand, installed-base upgrades, and future capacity expansion into sustained earnings growth. Higher system deliveries and improving productivity support the upside, while manufacturing constraints, customer spending cycles, and a 53.96% YTD share-price gain make execution and valuation important considerations.
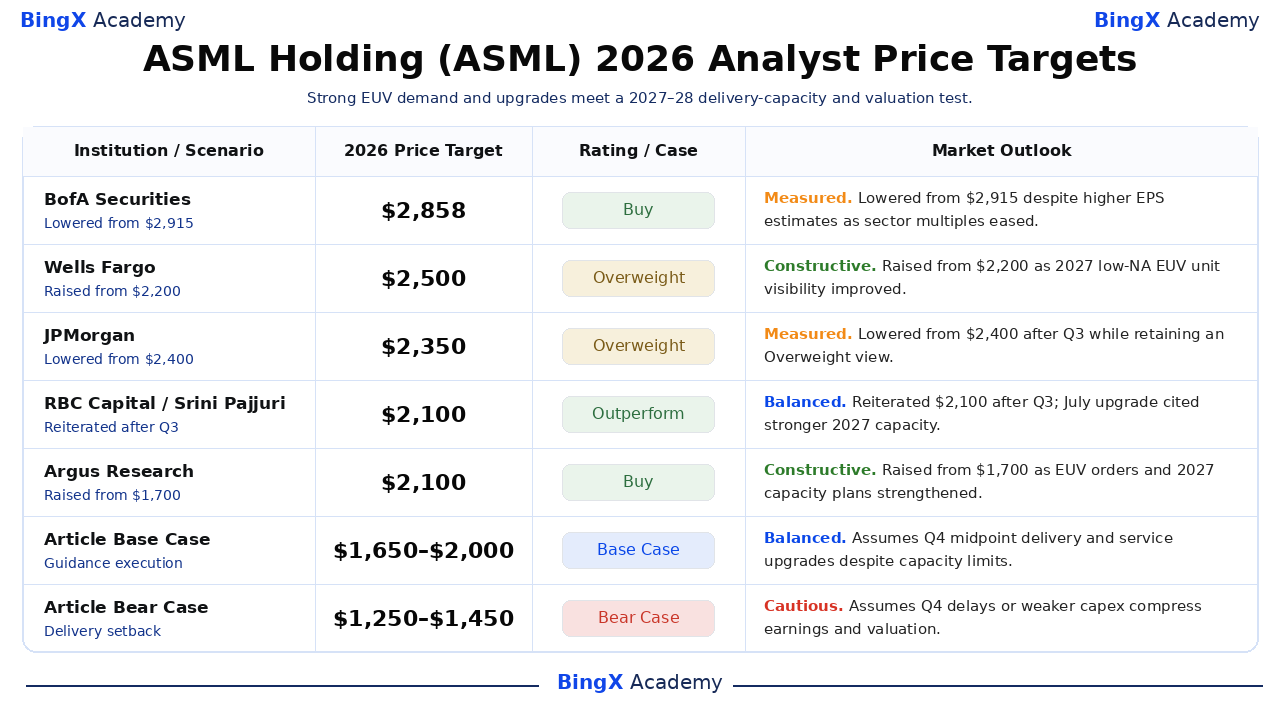
The Bull Case: Strong EUV Demand Pushes ASML Toward 2,250–2,500
The Bull Case assumes Q4 revenue approaches the €15.2B ($17.02B) guidance ceiling, with gross margin holding near 57%. Strong installed-base upgrades and High-NA EUV productivity improvements could support higher system output, while additional 2028 manufacturing capacity helps convert customer demand into future deliveries.
A move toward 2,250–2,500 would require ASML to surpass its $1,999.96 52-week high, execute Q4 shipments, and demonstrate stronger 2027–28 order conversion. Confirmed capacity expansion and sustained margins would provide further support for a higher valuation.
The Base Case: Steady Equipment Growth Keeps ASML Between $1,650 and $2,000
The Base Case assumes Q4 revenue reaches approximately the €14.7B (16.46B)guidancemidpoint,keepingfull-yearsaleswithin€44Bto€45B(49.26B to $50.38B). Installed-base upgrades support margins, while capacity constraints and customer production schedules gradually shift some equipment deliveries into later periods.
ASML could trade between $1,650 and $2,000 if Q4 revenue meets guidance, gross margin remains near 57%, and planned capacity additions progress. Stronger orders could lift shares above the range, while shipment delays or weaker guidance would increase downside pressure.
The Bear Case: Delivery Delays Pull ASML Toward 1,250–1,450
The Bear Case assumes customers delay semiconductor capacity investment or ASML falls short of its ambitious Q4 delivery schedule. Revenue below the €14.2B ($15.90B) guidance floor, weaker margins, or slower High-NA EUV adoption could limit earnings growth. Export restrictions and equipment acceptance delays would add pressure.
A move toward 1,250–1,450 would become more likely if Q4 results miss guidance, 2027 equipment deliveries weaken, or customers cancel rather than postpone orders. Following ASML's strong YTD rally, lower earnings expectations could also trigger a significant valuation correction.
ASML Stock Price Forecasts for 2026 By Wall Street Analysts
These are dated institution targets for ASML's U.S.-listed shares, not promises of a year-end price. Wells Fargo and Argus actions followed Q2, while the BofA and JPMorgan reductions and RBC reiteration reflected the October update. The 2,100–2,858 spread reflects valuation uncertainty; the final two rows are editorial scenarios.
|
Institution / Scenario |
2026 Price Target |
Rating / Case |
Market Outlook |
|
BofA Securities |
$2,858 |
Buy |
Measured. October 15: Lowered from $2,915 despite higher EPS forecasts because sector valuation multiples contracted. |
|
Wells Fargo |
$2,500 |
Overweight |
Constructive. July 16: Raised from $2,200 after stronger results, citing scope for more than 90 low-NA EUV units in 2027. |
|
JPMorgan |
$2,350 |
Overweight |
Measured. October 15: Lowered from $2,400 while retaining Overweight after the October quarter update. |
|
RBC Capital |
$2,100 |
Outperform |
Balanced. October 14: Reiterated $2,100 after the Q3 update; its July upgrade reflected higher low-NA capacity expectations for 2027. |
|
Argus Research |
$2,100 |
Buy |
Constructive. July 15: Raised from $1,700 after Q2, highlighting strong EUV orders and 2027 capacity additions. |
|
Article Base Case |
1,650–2,000 |
Base Case |
Balanced. Assumes Q4 midpoint delivery and service upgrades despite capacity limits. |
|
Article Bear Case |
1,250–1,450 |
Bear Case |
Cautious. Assumes Q4 delays or weaker capex compress earnings and valuation. |
How to Trade ASML Holding (ASML) Stock on BingX
Trade ASML Holding's EUV demand and delivery-capacity outlook using BingX TradFi and BingX AI tools. Because ASML can react sharply to system deliveries, gross margins and chipmaker spending plans, traders should define both the catalyst and risk limits before entering a position.
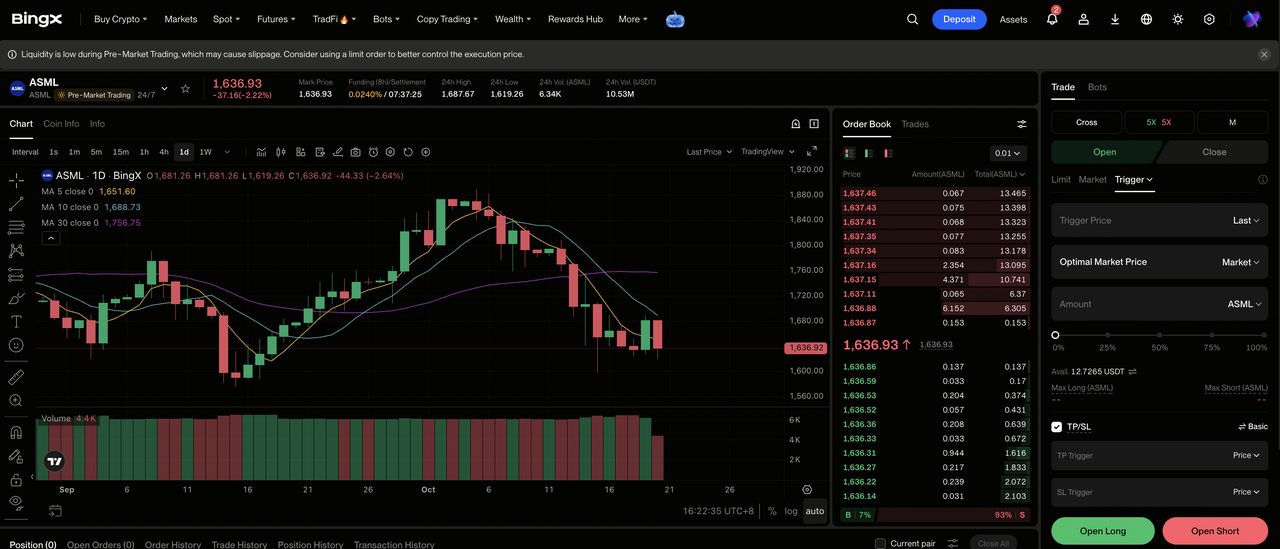
Step 1: Access BingX TradFi. Sign up and navigate to the specialized TradFi section on the BingX exchange dashboard.
Step 2: Select ASML Holding (ASML). Search for and select the ASML-USDT perpetual futures contract.
Step 3: Choose your direction. Select Open Long if you expect Q4 deliveries and EUV capacity plans to strengthen earnings. Select Open Short if you expect customer deferrals or a Q4 guidance miss.
Step 4: Select leverage and margin mode. Choose Isolated or Cross-Margin based on your risk tolerance. ASML's 53.96% year-to-date gain makes conservative leverage and clear position sizing important around earnings.
Step 5: Execute strict risk protocols. Set Take-Profit and Stop-Loss (TP/SL) levels before or immediately after entering the trade. ASML can react quickly to new system-delivery data, capacity commitments, export rules and major chipmaker spending plans.
Top 5 Risks to Watch for ASML Holding Investors in 2026
Multi-year demand may reach earnings later or at a lower margin than expected, while export rules and valuation can amplify the change in per-share value.
- Capacity bottlenecks can defer recognized sales: Management says currently planned 2027 and 2028 supply is short of customer forecasts. Longer tool builds can defer deliveries and near-term EPS despite demand, reducing the value of near-term guidance.
- AI spending could become more selective: Foundries and memory makers invest heavily on assumptions about future AI chip demand. If capital commitments slow, 2029–30 interest may fail to become orders, weakening backlog visibility and valuation.
- Export controls can narrow the addressable market: Advanced equipment sales to China are subject to licenses and shifting restrictions. Tighter licensing can reduce volume and shift mix while reassignment takes time, materially depressing operating leverage.
- High-NA economics still require adoption: The TSMC photomask collaboration describes a productivity goal above 40% for a specific dual-mask step, not a guaranteed broad deployment. Delayed integration would slow tool utilization and future field-option revenue.
- Valuation and currency can magnify disappointment: The U.S. listing had risen 53.96% year to date at October 19. Weaker margins could compress the multiple, while currency changes alter dollar-translated earnings for U.S. investors.
Final Thoughts: Should You Invest in ASML Holding in 2026?
ASML enters the final quarter with a rare combination: €11.662B ($13.06B) in Q3 sales, a 57.5% gross margin, rising installed-base upgrades and customer demand that management says exceeds currently planned supply for the next two years. EUV underpins advanced logic and memory expansion. The issue is when machines and upgrades can be delivered.
The 2,250–2,500 bull case needs upper-end Q4 execution and additional capacity; the 1,250–1,450 bear case reflects delivery or demand setbacks. Neither is a guaranteed forecast. A conservative investor can watch Q4 accepted-system volume, gross margin and firm 2027–28 capacity plans before assigning a durable value to the next demand cycle.
Risk Reminder: Trading and investing in equities like ASML involves a high risk of capital loss. Delivery delays, chipmaker spending changes, export restrictions and valuation shifts can move the shares sharply. Conduct independent research before allocating capital.
Related Reading
- Top AI Chip Manufacturing Stocks to Buy in 2026: TSMC, ASML, and Advanced Chipmaking
- TSMC (TSM) Price Prediction 2026: Can Record AI Demand Lift TSM Stock to $527?
- Intel (INTC) Price Prediction 2026: Can AI CPU Demand Push INTC Toward $145?
- Micron (MU) Price Prediction 2026: Can AI Memory Demand Push MU Toward $2,100?
- SK Hynix (SKHYNIX) Stock Price Prediction 2026: Can AI Memory Leader SKHYNIX Break $1,300?
- Samsung Stock Price Prediction 2026: ₩480,000 Street-High Memory Supercycle or Strike Crisis Trap?
