
UnitedHealth Group (UNH) combines health insurance with care delivery, pharmacy services and healthcare technology. UnitedHealthcare supplies the premium base, while Optum broadens the earnings engine through clinical services, prescription management and analytics. The investment question is whether improved claims management can restore sustainable profitability while a smaller insurance membership base and healthcare funding pressure constrain revenue growth.
The latest quarter showed stronger profitability alongside a still-contracting revenue base. UnitedHealth Group Q3 2026 revenue declined to $112.7 billion, while adjusted EPS increased 60.6% to $4.69. The medical care ratio improved to 88.4%, although favorable reserve development contributed $610 million. The next test is sustaining the raised full-year adjusted EPS floor of $20.50 without relying on another comparable reserve benefit.
The UNH stock forecast for 2026 now centers on two competing views:
- The medical-cost recovery case: Better pricing and integrated care preserve underwriting margins, while Optum improvements turn the premium base into stronger recurring earnings and cash generation.
- The membership pressure case: Enrollment losses, elevated utilization and constrained government funding erode the revenue base, leaving investment and regulatory costs consuming too much of the recovery.
This guide breaks down the UNH stock forecast, 2026 price scenarios, key risks and analyst outlooks, drawing on UnitedHealth Group's October 13 earnings release, prepared remarks and October 21 market close, plus how to buy UNH stock on BingX TradFi with USDT or USDC.
Top 5 Things for UnitedHealth Group Investors to Know in October 2026
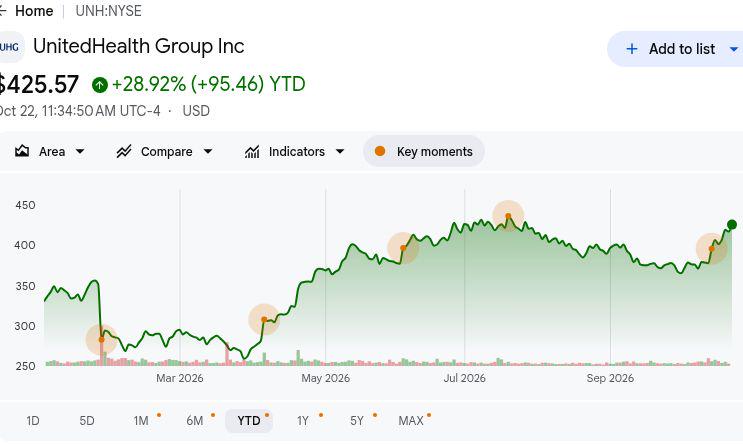
- UNH closed at $416.96 on October 21, up 26.31% YTD: Shares remain above their opening-year level, making the $530 bull scenario dependent on sustained margin recovery. Continued gains require UnitedHealthcare to preserve claims profitability, rather than relying on another unusually favorable reserve adjustment.
- Q3 revenue decreased to $112.7 billion from $113.2 billion a year earlier: Sales also rose from $112.0 billion in Q2, showing sequential progress. However, lower insurance enrollment limited growth, making it important to distinguish improved premium pricing from a broader recovery in customer numbers.
- The medical care ratio improved to 88.4% as claims management strengthened: The Q3 ratio and UnitedHealthcare's 3.3% operating margin provide evidence of improved insurance economics. Pricing adequacy, underlying utilization, and reserve accuracy will determine how much of that improvement translates into repeatable earnings.
- Full-year guidance sets a sustained profitability test: Management targeted adjusted EPS of at least $20.50 for 2026, compared with the previous $19.50 to $20.00 range. Realized medical-cost savings and improved Optum profitability will determine whether that outlook supports sustained per-share earnings growth.
- Operating cash flow of $5.1 billion supports investment and shareholder distributions: UnitedHealth reported a 41.7% debt-to-capital ratio alongside $5 billion in year-to-date buybacks. This provides support for modernization, although reducing leverage while sustaining cash generation will be essential to long-term shareholder value.
What Is UnitedHealth Group (UNH)?
UnitedHealth Group is a U.S. healthcare company operating through UnitedHealthcare and Optum. UnitedHealthcare provides employer-sponsored, Medicare Advantage, Medicaid and individual health plans, earning premiums while paying members' covered medical expenses. Optum delivers clinical care, pharmacy-benefit management, technology and administrative services to patients, employers, governments and healthcare organizations. The company generates revenue through insurance premiums, service fees and pharmacy activities, with 48.3 million UnitedHealthcare consumers illustrating a large customer base whose profitability depends on claims costs, reimbursement and operating efficiency.
UnitedHealth Group's growth strategy focuses on integrated value-based care, simpler health benefits and healthcare technology modernization. In October 2025, Optum expanded its collaboration with Microsoft around Optum Real, an AI-enabled claims and reimbursement platform designed to improve coverage checks and reduce administrative errors. The company has also introduced Avery, a generative AI companion for UnitedHealthcare members, while targeting nearly $1.5 billion in AI-related investment during 2026. With Optum serving over 120 million patients and consumers in Q3, these initiatives aim to improve service productivity and strengthen long-term healthcare margins.
Read More: Top Pharma Stocks to Buy in 2026: Cancer Drugs, Weight-Loss Drugs, mRNA, and New Medicines
UnitedHealth Group (UNH) Q3 2026 Earnings Overview: Medical Cost Recovery Drives 60.6% EPS Growth Despite Lower Revenue
UnitedHealth Group reported Q3 2026 revenue of $112.7 billion, down from $113.2 billion a year earlier, as membership contraction offset pricing improvements. Operating earnings increased to $6.6 billion from $4.3 billion, while adjusted EPS reached $4.69 from $2.92 and the medical care ratio improved to 88.4%, supported partly by $610 million in favorable reserve development. With operating cash flow of $5.1 billion and raised adjusted EPS guidance of at least $20.50, future earnings depend on retaining medical-cost improvements as enrollment contracts.
|
Financial Metric |
Guidance / Consensus |
Reported / Actual |
Surprise |
|
Revenue |
$113.2B Q3 2025 |
$112.7B |
Lower. Down about 0.4% YoY. |
|
Adjusted EPS |
$2.92 Q3 2025 |
$4.69 |
Improved. Up 60.6% YoY. |
|
Medical care ratio |
89.9% Q3 2025 |
88.40% |
Lower. Down 1.5 points. |
|
Operating earnings |
$4.3B Q3 2025 |
$6.6B |
Improved. Up about 53%. |
|
UnitedHealthcare margin |
2.1% Q3 2025 |
3.30% |
Improved. Up 1.2 points. |
|
Optum operating earnings |
$2.5B Q3 2025 |
$3.7B |
Improved. Up about 48%. |
|
Debt-to-capital ratio |
41.2% Q2 2026 |
41.70% |
Higher. Up 0.5 points. |
|
FY2026 adjusted EPS guide |
19.50–20.00 prior |
At least $20.50 |
Raised. Above prior range. |
- Q3 revenue declined about 0.4% to $112.7 billion. Revenue increased from $112.0 billion sequentially despite annual contraction, reflecting pricing and membership changes. Sustained premium adequacy and customer retention will be important to maintaining earnings momentum.
- UnitedHealthcare operating margin improved to 3.3% from 2.1%. Better benefit design and medical-cost management drove performance across the insurance business. Continued pricing discipline and care coordination could support earnings, although utilization and government funding influence profitability.
- Adjusted EPS rose 60.6% to $4.69 despite contracting revenue. The medical care ratio improved, while favorable reserve development contributed $610 million. Better insurance economics supported reported results, but underlying cost control will be important as healthcare demand normalizes.
- Optum Health operating earnings increased to $735 million. Its operating margin reached 3.2%, supporting a recovery from the prior year's $41 million result. Expanding integrated care supports profitability, while returns depend on medical management and appropriate patient-market selection.
- Full-year adjusted EPS guidance reached at least $20.50. The outlook exceeds the prior range, with delivery depending on medical-cost control. Retaining members, improving Optum margins, and maintaining expense discipline will be important to future earnings growth.
UnitedHealth Group (UNH) 2026 Investment Outlook: $530 Bull Case vs. $350 Bear Case
UnitedHealth Group's 2026 outlook depends on whether improved claims management can support earnings without another large reserve benefit. Q3 operating earnings recovered to $6.6 billion, while contracting membership makes premium retention and care efficiency central to valuation. The following editorial scenarios reflect how medical utilization, Optum profitability and capital demands could shape performance through December 2026.
The Bull Case: Medical Cost Recovery and Optum Growth Push UNH Toward $530
Keeping medical costs aligned with premium pricing would lift insurance earnings while a healthier Optum business broadens the recovery. Q3 UnitedHealthcare operating margin reached 3.3%, up from 2.1%, and Optum Health earned $735 million. More consistent care management would retain a larger share of premiums as technology and pharmacy services contribute additional operating profit.
The $530 scenario would gain support if the underlying medical care ratio holds near or below Q3's 88.4% without another reserve benefit. Adjusted EPS exceeding the $20.50 guidance floor and better Optum margins would reinforce that recovery.
The Base Case: Steady Healthcare Margins Keep UNH Between $410 and $455
Profitable insurance and pharmacy operations could preserve earnings even if enrollment recovers slowly. UnitedHealthcare generated $2.8 billion in operating income, while Optum Rx contributed $1.7 billion despite lower prescription volumes. Stable premium adequacy would sustain those earnings supports, but a smaller membership base and continued modernization spending would keep revenue growth and margin expansion measured.
A $410 to $455 range would fit delivery of the raised earnings floor, stable claims management and continued Optum improvement. Better member retention would support the upper end, while higher utilization could absorb enough progress to limit share-price gains.
The Bear Case: Higher Claims and Membership Losses Pull UNH Toward $350
Rising medical utilization would reduce insurance earnings faster than technology efficiencies can offset lost membership revenue. Q3's 88.4% medical care ratio benefited from $610 million in reserve development, while Medicare Advantage enrollment had contracted by 935,000 since year-end. If claims trends worsen as those benefits fade, UnitedHealth would retain less profit from an already smaller insurance base.
The $350 scenario would become more likely if medical costs move back toward the prior year's ratio alongside continued enrollment losses. Optum would then need to contribute more simply to stabilize earnings, leaving less support for buybacks and valuation.
UNH Stock Price Forecasts for 2026 By Wall Street Analysts
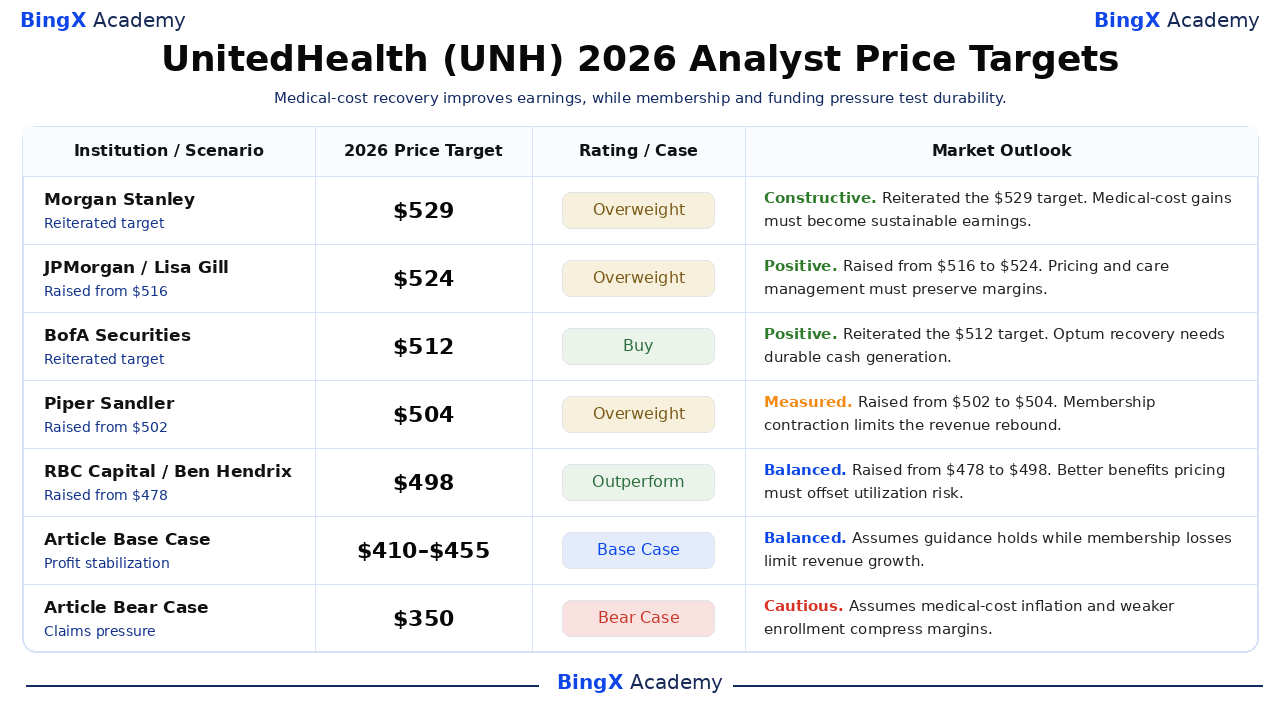
Wall Street's targets reflect differing confidence in UnitedHealth's medical-cost recovery and its ability to sustain Optum profits. The selected dated actions span $498 to $529, generally representing twelve-month horizons that extend beyond 2026. The article's $530 bull, $410 to $455 base and $350 bear cases are separate December 2026 scenarios.
|
Institution / Scenario |
2026 Price Target |
Rating / Case |
Market Outlook |
|
Morgan Stanley |
$529 |
Overweight |
Constructive. October 14, 2026: Reiterated the $529 target. Editorial view: Medical-cost gains must become sustainable earnings. |
|
JPMorgan |
$524 |
Overweight |
Positive. October 16, 2026: Raised from $516 to $524. Editorial view: Pricing and care management must preserve margins. |
|
BofA Securities |
$512 |
Buy |
Positive. October 14, 2026: Reiterated the $512 target. Editorial view: Optum recovery needs durable cash generation. |
|
Piper Sandler |
$504 |
Overweight |
Measured. October 14, 2026: Raised from $502 to $504. Editorial view: Membership contraction limits the revenue rebound. |
|
RBC Capital |
$498 |
Outperform |
Balanced. October 20, 2026: Raised from $478 to $498. Editorial view: Better benefits pricing must offset utilization risk. |
|
Article Base Case |
410–455 |
Base Case |
Balanced. Editorial December 2026 scenario. Assumes guidance holds while membership losses limit revenue growth. |
|
Article Bear Case |
$350 |
Bear Case |
Cautious. Editorial December 2026 scenario. Assumes medical-cost inflation and weaker enrollment compress margins. |
How to Buy UnitedHealth Group (UNH) Stock on BingX
Buy and hold UnitedHealth Group shares through BingX Stocks Trading using USDT or USDC, subject to listing and account eligibility. UnitedHealth offers exposure to health insurance, care delivery, pharmacy services and healthcare technology. Eligible users can size holdings according to their investment goals without using leverage or paying perpetual funding fees.
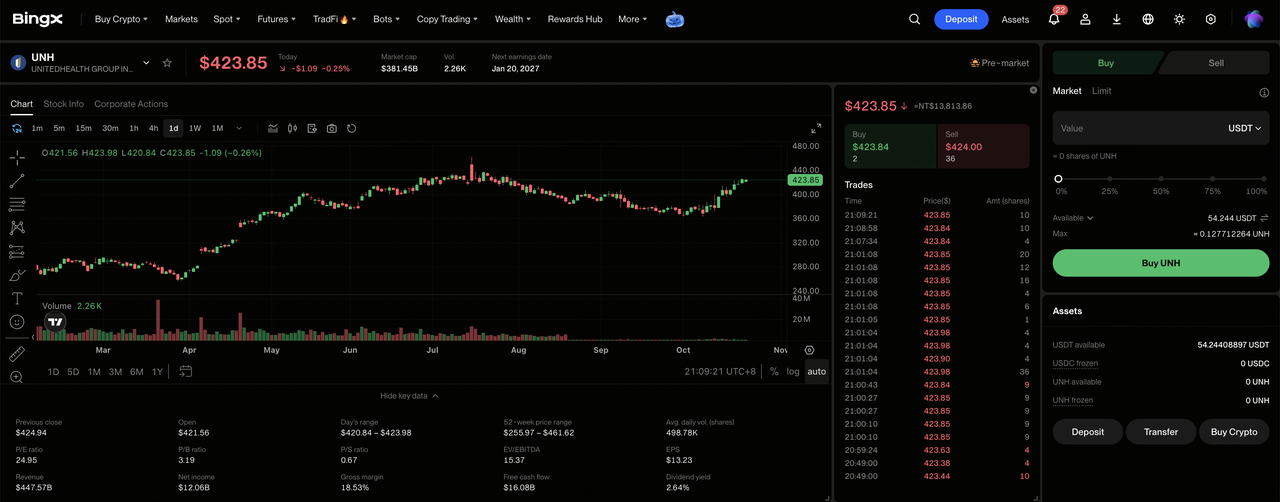
Step 1: Access BingX Stocks Trading. Sign up or log in to BingX, complete the required identity verification, and navigate to “TradFi > Stocks”. Accept the Stock Trading Risk Disclosure if accessing the product for the first time.
Step 2: Prepare USDT or USDC. Ensure your Spot Account has sufficient funds for the purchase. Transfer USDT or USDC from your Fund Account or Wealth Account if needed. Review the selected stock’s minimum order amount and fractional eligibility before choosing the investment size.
Step 3: Select UnitedHealth Group (UNH). Open the Stocks market, search for UnitedHealth Group (UNH), and confirm that the share is available to your account. Review the company identity, current share price, trading session and available order types.
Step 4: Buy UnitedHealth Group Shares. Select “Buy”, enter an allowed investment amount or share quantity, and choose a supported market or limit order. Market orders use available prices during supported sessions, while limit orders require the specified price or better and sufficient liquidity to execute.
Step 5: Review and Manage Your Holdings. Open “Stocks > Positions” to monitor your UNH shares and unrealized profit or loss. Use All Orders to review transactions or sell shares when needed. T+1 settlement generally affects when sale proceeds become withdrawable, rather than when purchased shares can be sold.
Top 5 Risks to Watch for UnitedHealth Group Investors in 2026
UnitedHealth Group's insurance scale, integrated care capabilities, and pharmacy operations support its earnings outlook. However, medical utilization, enrollment losses, funding pressure, and capital requirements could pressure profitability and shareholder returns.
- Weaker enrollment could pressure revenue: UnitedHealthcare served 48.3 million consumers, supported by employer and government health plans. Lower member retention or Medicare Advantage enrollment could reduce premium revenue and insurance operating margins over time.
- Rising medical costs could constrain margins: The Q3 medical care ratio reached 88.4% after favorable reserve development. Higher hospitalization and specialty-drug costs could weaken profitability if premium revenue and care efficiencies grow more slowly.
- Government payment delays could limit revenue growth: Medicaid margins remained pressured, but state funding updates were uneven across markets. Delayed rate adjustments, reimbursements, or contract renewals could reduce future revenue visibility.
- Capital requirements could restrict shareholder returns: UnitedHealth repurchased $5 billion in shares through Q3, while its debt-to-capital ratio reached 41.7%. Higher medical obligations or investment needs could constrain future buybacks and per-share earnings growth.
- Weaker earnings could pressure valuation: UnitedHealth's adjusted EPS reached $4.69, supported by improved claims management and favorable reserve development. Slower enrollment, weaker Optum performance, or rising claims costs could reduce earnings and trigger share-price declines.
Final Thoughts: Should You Invest in UnitedHealth Group in 2026?
UnitedHealth Group's $6.6 billion in quarterly operating earnings and $5.1 billion in operating cash flow demonstrate a recovery in healthcare profitability and cash generation. Better UnitedHealthcare margins and stronger Optum Health earnings support progress beyond premium pricing, while modernization creates opportunities to improve efficiency. Sustaining that growth will depend on controlling medical utilization and retaining profitable membership.
The $530 bull case assumes sustainable insurance margins, continued Optum recovery, and delivery of raised earnings guidance. The $410 to $455 base case reflects stable operations, while the $350 bear case accounts for higher claims and membership pressure. With UNH closing at $416.96 on October 21, investors should watch whether claims improvements translate into durable per-share growth.
Risk Reminder: UnitedHealth Group's insurance scale does not eliminate investment risk. Higher medical costs, enrollment losses, or adverse funding changes could reduce earnings and shareholder returns. Investors should assess valuation, claims performance, and their risk tolerance before buying UNH shares.
Related Reading
- Top Pharma Stocks to Buy in 2026: Cancer Drugs, Weight-Loss Drugs, mRNA, and New Medicines
- Merck (MRK) Price Prediction 2026: Can Pipeline Momentum Push MRK Stock Toward $170?
- Moderna (MRNA) Price Prediction 2026: Can Cancer Vaccine Momentum Push MRNA Stock Toward $180?
- Pfizer Stock Price Prediction 2026: High-Yield Value Opportunity or Structural Value Trap?
- Abbott (ABT) Stock Price Outlook 2026: Can Medical Device Growth Push ABT Above $130?
