GE Aerospace (GE) manufactures aircraft engines and provides maintenance, parts and propulsion systems for airlines, aircraft makers and military customers. Its installed engine fleet generates recurring service demand, while LEAP deliveries and additional casting capacity create routes to expansion. Supplier output, engine durability and cash conversion determine whether that demand produces stronger earnings and shareholder returns.
The latest quarter showed stronger engine demand while cash generation lagged earnings growth. GE Aerospace Q3 2026 revenue rose 16% to $14.118 billion, with commercial-engine sales and services up 21%. Adjusted EPS increased 36% to $2.25, while free cash flow fell 14% to $2.042 billion. The Q4 test is whether higher servicing output can restore cash conversion and support the raised full-year outlook.
The GE stock forecast for 2026 now centers on two competing views:
- The service-growth and cash-recovery case: More shop visits and spare-parts sales support recurring earnings, while improved supplier output helps convert stronger demand into cash.
- The delivery-and-margin pressure case: Slower aftermarket growth, GE9X certification delays and production costs could absorb profit gains before the larger order book generates cash.
This guide breaks down the GE stock forecast, 2026 price scenarios, key risks and analyst outlooks, drawing on GE Aerospace's October 20 Q3 earnings release, SEC filing and October 26 market data, plus how to buy GE Stocks on BingX TradFi with USDT or USDC.
Top 5 Things for GE Aerospace Investors to Know in October 2026
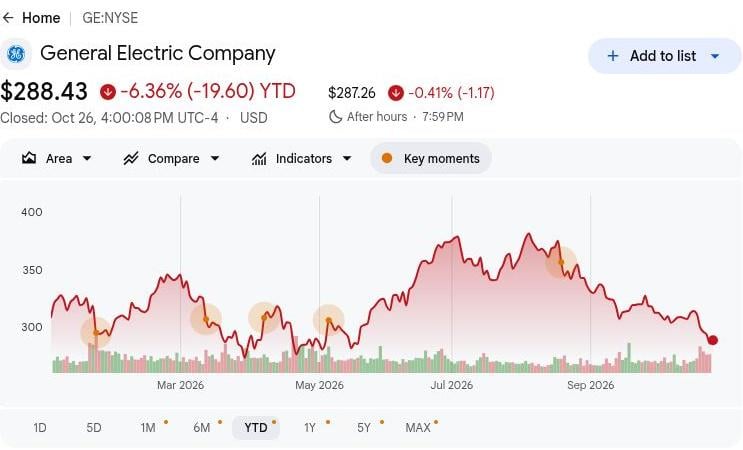
- GE closed at $288.43 on October 26, down 6.36% YTD: Shares remain below their opening-year level, making the $350 bull scenario dependent on stronger cash conversion. Continued gains require commercial services to generate durable earnings, rather than relying on engine-order announcements alone.
- Q3 revenue increased to $14.118 billion from $12.181 billion: Sales also rose from approximately $13.3 billion in Q2, showing sequential progress. Within that result, equipment sales grew faster than services, making it important to distinguish delivery growth from recurring aftermarket profitability.
- Commercial services backlog exceeded $170 billion as orders expanded: The Q3 pipeline and October Turkish Airlines agreement provide evidence of continuing engine demand. Shop capacity, supplier deliveries, and contract economics will determine how much of that pipeline translates into earnings and cash.
- The proposed CPP acquisition provides an additional capacity opportunity: GE signed an agreement to acquire Consolidated Precision Products to expand mission-critical castings production. Future transaction completion and increased component output will determine whether the planned expansion develops into sustained delivery growth.
- Year-to-date free cash flow supports investment but requires Q4 recovery: GE generated $6.728 billion through September alongside $1.002 billion of gross capital investment. This provides support for production expansion, although meeting the $9.1 billion to $9.4 billion annual cash outlook remains essential.
What Is GE Aerospace (GE)?
GE Aerospace is a global aircraft propulsion, services and systems company serving commercial aviation and defense customers. Its Commercial Engines & Services business combines new engine deliveries with maintenance, spare parts and long-term service agreements. Defense & Propulsion Technologies supplies military engines, aircraft systems and related technologies for government and aerospace customers. The company generates revenue across the engine lifecycle, with approximately 50,000 commercial and 30,000 military engines in its installed base supporting demand beyond the initial equipment sale.
GE Aerospace's growth strategy focuses on expanding servicing capacity, improving engine durability, and developing next-generation propulsion. In 2026, GE collaborated with NASA, BETA Technologies and Boeing on a hybrid-electric flight above 30,000 feet, demonstrating technology rather than launching a commercial engine. The company is also seeking additional casting capacity through its announced agreement to acquire Consolidated Precision Products and investing more than $3 billion annually in research and development. With Q3 commercial services backlog exceeding $170 billion, these initiatives aim to strengthen long-term service revenue and improve delivery economics.
Read More: Top Defense Stocks to Buy in 2026: Primes, Missiles, Drones, Space, and AI-Enabled Warfare
GE Aerospace (GE) Q3 2026 Earnings Overview: Service Growth Lifts Earnings Despite Weaker Cash Flow
GE Aerospace reported Q3 2026 GAAP revenue of $14.118 billion, up 16% year over year, supported by 21% growth in Commercial Engines & Services revenue to $10.342 billion. Non-GAAP operating profit increased 30% to $2.988 billion, while non-GAAP free cash flow declined 14% to $2.042 billion, separating earnings improvement from immediate cash generation. With adjusted EPS at $2.25 and full-year free-cash-flow guidance raised to $9.1 billion to $9.4 billion, future returns depend on service throughput, supplier capacity and cash conversion.
|
Financial Metric |
Guidance / Consensus |
Reported / Actual |
Surprise |
|
GAAP revenue |
$12.181B Q3 2025 |
$14.118B |
Improved. Up 16% YoY. |
|
Adjusted revenue |
$11.305B Q3 2025 |
$13.285B |
Improved. Up 18% YoY. |
|
Operating profit |
$2.299B Q3 2025 |
$2.988B |
Higher. Up 30% YoY. |
|
Adjusted EPS |
$1.66 Q3 2025 |
$2.25 |
Higher. Up 36% YoY. |
|
CES operating margin |
28.0% Q3 2025 |
27.90% |
Lower. Down 0.1 percentage point. |
|
Free cash flow |
$2.362B Q3 2025 |
$2.042B |
Lower. Down 14% YoY. |
|
FY2026 adjusted EPS |
7.65–7.85 prior guide |
8.00–8.10 |
Raised. Midpoint increased $0.30. |
|
FY2026 free cash flow |
8.9B–9.2B prior guide |
9.1B–9.4B |
Raised. Both endpoints increased $200M. |
- Q3 GAAP revenue increased 16% to $14.118 billion. Commercial orders reached $15.265 billion, reflecting strong equipment demand alongside additional service commitments. Sustained airline maintenance demand and engine deliveries will be important to maintaining commercial revenue momentum.
- Commercial Engines & Services revenue rose 21% to $10.342 billion. Higher shop-visit revenue and spare-parts sales drove performance. Continued airline maintenance and fleet expansion could support earnings, although equipment mix and component inflation influence profitability across the engine lifecycle.
- Adjusted EPS rose 36% to $2.25 despite commercial-margin pressure. Commercial operating margin fell to 27.9%, while group operating margin reached 22.5%. Higher service volumes supported profitability, but production efficiency will be important as new-engine deliveries expand across customer fleets.
- Annual research spending supports current and future engine capabilities. Management cited over $3 billion of annual R&D alongside its planned CPP casting acquisition. The investments support propulsion development, with returns depending on certification and profitable production at commercial scale.
- Commercial services backlog exceeded $170 billion at Q3. The pipeline supports future servicing activity, although revenue recognition depends on maintenance schedules and completed work. Increasing shop output, improving component availability, and collecting cash will be important to future earnings growth.
GE Aerospace (GE) 2026 Investment Outlook: $350 Bull Case vs. $250 Bear Case
GE Aerospace's 2026 outlook depends on whether stronger engine servicing can translate into cash alongside higher earnings. The raised $9.1 billion to $9.4 billion free-cash-flow outlook shows confidence, while weaker quarterly cash generation makes working-capital conversion central to valuation. The following editorial scenarios reflect how servicing demand, supplier output and certification progress could shape performance through December 2026.
The Bull Case: Service Growth and Cash Recovery Push GE Toward $350
Increasing shop output and collecting more cash would give GE a direct route to stronger shareholder returns. Commercial services revenue grew 17% in Q3, while free cash flow fell 14%, showing that earnings momentum has not fully reached cash generation. Extending servicing growth would improve conversion while spare-parts demand continues supporting commercial profits.
The $350 scenario would gain support if commercial services sustain growth near 17% and full-year free cash flow reaches the $9.4 billion upper guide. Holding commercial margins near 27.9% would help turn higher throughput into durable earnings.
The Base Case: Steady Servicing Keeps GE Between $290 and $320
Continued maintenance demand could keep GE's earnings progressing even if equipment deliveries remain costly. Commercial operating profit reached $2.887 billion, helping absorb production investment while the segment margin edged lower. The base case assumes servicing continues funding expansion, producing moderate underlying progress while leaving supplier bottlenecks and GE9X certification timing unresolved through year-end.
A $290 to $320 range would fit adjusted EPS within $8.00 to $8.10 and achievable full-year cash guidance. Stronger collections would support the upper end, while additional delivery costs could absorb enough service growth to limit share-price upside.
The Bear Case: Slower Servicing and Delivery Delays Pull GE Toward $250
Slower aftermarket growth would expose GE more fully to equipment costs and delayed cash conversion. Commercial services supplied an important earnings increase, while segment margins slipped and GE9X shipment revenue awaited midseal certification. If shop output slows or component shortages persist, GE could lose that profit cushion before new-engine economics improve and cash catches up.
The $250 scenario would become more likely if service growth weakens alongside cash generation below the $9.1 billion annual floor. Equipment deliveries would then need to contribute more simply to stabilize cash, leaving less support for per-share growth and valuation.
GE Stock Price Forecasts for 2026 By Wall Street Analysts
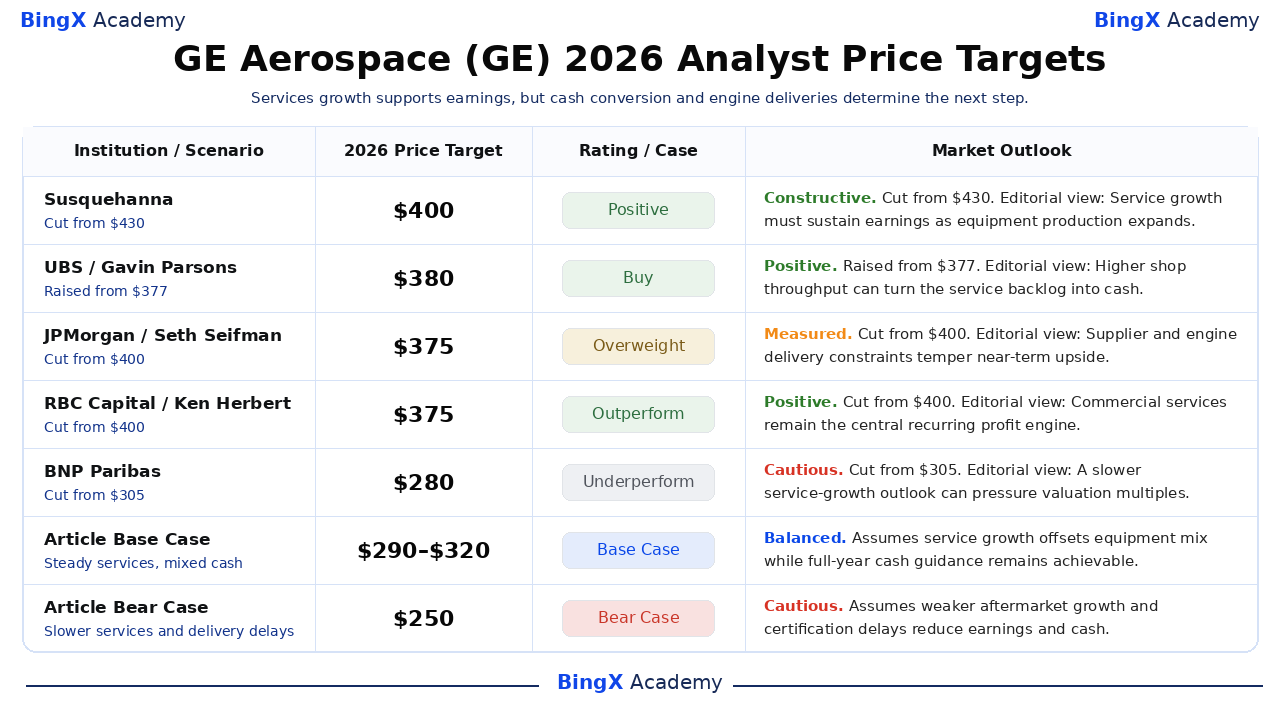
These named, dated third-party targets refer to NYSE-listed GE and generally cover a roughly 12-month horizon extending beyond 2026. The selected $280 to $400 range reflects differing views on service growth, delivery costs and valuation. Business interpretations below are editorial; the final two rows are this article's separate year-end scenarios.
|
Institution / Scenario |
2026 Price Target |
Rating / Case |
Market Outlook |
|
Susquehanna |
$400 |
Positive |
Constructive. October 21, 2026: Charles Minervino cut the target from $430 to $400 and maintained Positive. Editorial interpretation: Service growth must sustain earnings as equipment production expands. |
|
UBS |
$380 |
Buy |
Positive. October 21, 2026: Gavin Parsons raised the target from $377 to $380 and maintained Buy. Editorial interpretation: Higher shop throughput can turn the service backlog into cash. |
|
JPMorgan |
$375 |
Overweight |
Measured. October 21, 2026: Seth Seifman cut the target from $400 to $375 and maintained Overweight. Editorial interpretation: Supplier and engine delivery constraints temper near-term upside. |
|
RBC Capital |
$375 |
Outperform |
Positive. October 21, 2026: Ken Herbert cut the target from $400 to $375 and maintained Outperform. Editorial interpretation: Commercial services remain the central recurring profit engine. |
|
BNP Paribas |
$280 |
Underperform |
Cautious. October 21, 2026: Matthew Akers cut the target from $305 to $280 and maintained Underperform. Editorial interpretation: A slower service-growth outlook can pressure valuation multiples. |
|
Article Base Case |
290–320 |
Base Case |
Balanced. Assumes service growth offsets equipment costs while full-year earnings and cash guidance remain achievable through December. |
|
Article Bear Case |
$250 |
Bear Case |
Cautious. Assumes slower aftermarket growth and certification delays pressure earnings and cash conversion. |
How to Buy GE Aerospace (GE) Stock on BingX
Buy and hold GE Aerospace shares through BingX Stocks Trading using USDT or USDC, subject to listing and account eligibility. GE offers exposure to commercial aircraft engines, aftermarket services and defense propulsion. Eligible users can size holdings according to their investment goals without using leverage or paying perpetual funding fees.
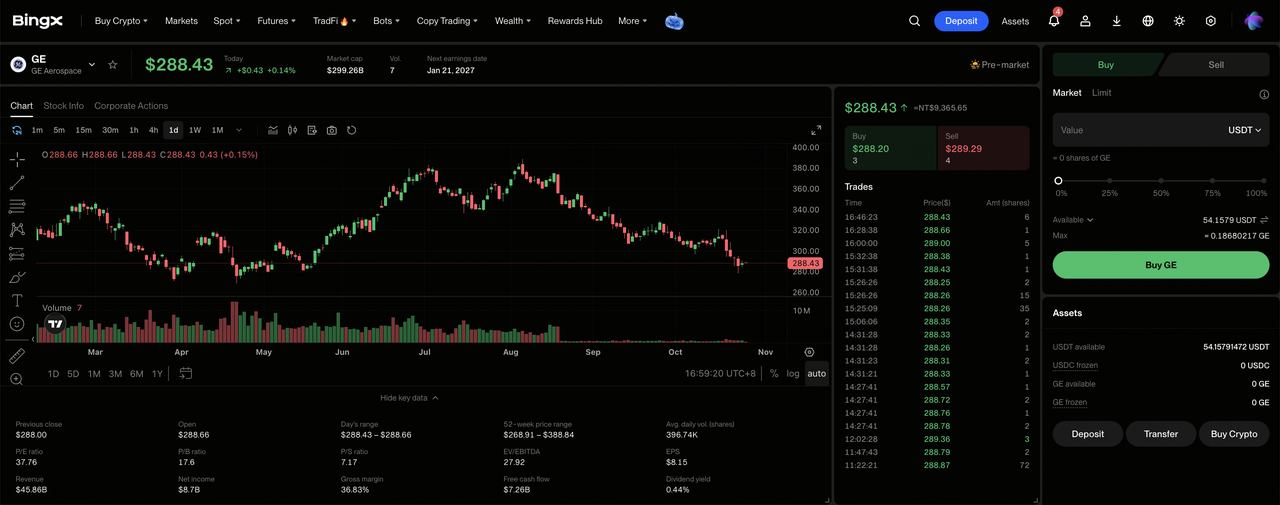
Step 1: Access BingX Stocks Trading. Sign up or log in to BingX, complete the required identity verification, and navigate to “TradFi > Stocks”. Accept the Stock Trading Risk Disclosure if accessing the product for the first time.
Step 2: Prepare USDT or USDC. Ensure your Spot Account has sufficient funds for the purchase. Transfer USDT or USDC from your Fund Account or Wealth Account if needed. Review the selected stock’s minimum order amount and fractional eligibility before choosing the investment size.
Step 3: Select GE Aerospace (GE). Open the Stocks market, search for GE Aerospace (GE), and confirm that the share is available to your account. Review the company identity, current share price, trading session and available order types.
Step 4: Buy GE Aerospace Shares. Select “Buy”, enter an allowed investment amount or share quantity, and choose a supported market or limit order. Market orders use available prices during supported sessions, while limit orders require the specified price or better and sufficient liquidity to execute.
Step 5: Review and Manage Your Holdings. Open “Stocks > Positions” to monitor your GE shares and unrealized profit or loss. Use All Orders to review transactions or sell shares when needed. T+1 settlement generally affects when sale proceeds become withdrawable, rather than when purchased shares can be sold.
Top 5 Risks to Watch for GE Aerospace Investors in 2026
GE Aerospace's installed engine fleet, growing services backlog, and defense relationships support its earnings outlook. However, aftermarket demand, production costs, certification timing, and cash conversion could pressure profitability and shareholder returns.
- Weaker maintenance demand could pressure revenue: Q3 commercial services revenue grew 17%, supported by shop visits and spare-parts demand. Lower airline maintenance volumes or parts orders could reduce recurring earnings and commercial operating margins.
- Lower commercial margins could weaken profitability: Q3 commercial operating margin fell to 27.9% from 28.0%. Higher component and engineering costs could weaken profitability if service revenue and spare-parts sales grow more slowly.
- Certification delays could limit equipment revenue growth: GE delivered GE9X engines in Q3, but recognition awaited upgraded midseal certification. Delayed regulatory clearance or customer aircraft deliveries could reduce future revenue visibility.
- Production investment could weaken shareholder returns: GE spent $337 million on property, equipment and software during Q3, supporting manufacturing capacity. Lower utilization or additional component costs could limit cash generation and reduce shareholder returns.
- Weaker cash conversion could pressure valuation: GE's Q3 free cash flow reached $2.042 billion, trailing earnings growth. Slower collections, weaker servicing output, or rising production costs could reduce cash returns and trigger share-price declines.
Final Thoughts: Should You Invest in GE Aerospace in 2026?
GE Aerospace's $2.988 billion in quarterly non-GAAP operating profit and $6.728 billion in year-to-date free cash flow highlight its earnings and investment capacity. Commercial servicing and defense propulsion provide profit support, while planned casting expansion creates opportunities to increase deliveries. Sustaining that progress will depend on converting maintenance demand into cash and protecting margins as engine production expands.
The $350 bull case assumes sustained servicing growth, resilient margins, and cash recovery toward the upper guidance. The $290 to $320 base case reflects steady maintenance demand, while the $250 bear case accounts for delivery delays and weaker cash. With GE closing at $288.43 on October 26, investors should watch whether rising service profits translate into sustainable shareholder returns.
Risk Reminder: GE Aerospace's installed engine fleet does not eliminate investment risk. Weaker maintenance demand, supplier shortages, or certification delays could reduce earnings and cash generation. Investors should assess valuation, cash conversion, and their risk tolerance before buying GE shares.
Related Reading
- Top Defense Stocks to Buy in 2026: Primes, Missiles, Drones, Space, and AI-Enabled Warfare
- Top Space Stocks to Buy Ahead of SpaceX IPO
- RTX Corporation (RTX) Price Prediction 2026: Can Aerospace and Defense Growth Push RTX Toward $260?
- Lockheed Martin (LMT) Price Prediction 2026: Can Record Backlog Push LMT Toward $700?
- Rocket Lab (RKLB) Price Prediction 2026: Can New Rocket and Defense Growth Push RKLB Toward $150?
